As a lawyer, what’s your superpower? What perspectives can you bring to a boardroom table that other professionals may overlook? How can you help a board of directors lean into risk, while maintaining boundaries?
In September 2026, the American Bar Association held its Business Law Section Fall Meeting in Chicago, Illinois. I had the opportunity to attend a panel entitled “From Legal Advisor to Boardroom Decision-Maker: The Lawyer as a Value-Creating Director,” which focused on three leaders in industry, who have had the opportunity to add “board member” to their resumes. The discussion was moderated by Katayun Jaffari of Cozen O’Connor, chair of the firm’s Corporate Governance Group, co-chair of its Capital Markets & Securities Group, and chair of its ESG Practice. The program featured insights from panelists Tanuja Dehne, managing director at DSG Global and independent board director; Sherrin Ross Ingram, founder and CEO of the International Center for Strategic Planning and independent board director; and Michelle Hong, counsel at Stradley Ronon and independent board director.
What’s Your Superpower?
To kick off the panel discussion, Jaffari asked each panelist to discuss the superpower that they bring to the boardroom. Dehne described her superpower as “leaning towards the edge.” As a corporate M&A and securities attorney, she is able to “push the edges” and lean into risk while knowing the boundaries. She also highlighted time management and communications as transferable skills from the legal profession that have served her well in the boardroom. Ingram’s superpower as a litigator is her “ability to challenge, to ask the probing questions.” She described lawyers as particularly well suited to ask those probing questions, because that is how we are trained. Hong comes from a trusts and estates legal background, and she highlighted her ability to think both inside and outside of the box in making risk-weighted judgments.
Understanding the Blind Spots
The panelists were asked to consider how lawyers can understand their own blind spots as they pertain to boardroom decision-making. As a lawyer turned strategic advisor, Ingram enjoys unpacking biases and the underlying assumptions that form those biases. She thinks that questioning biases and helping others understand their own biases is a huge part of the value that lawyers can bring to an organization and a board. Dehne emphasized that you cannot get comfortable and must keep consistently learning and building. Hong highlighted the value of reviewing the board materials and then going for a walk or taking a shower to let your mind wander and find the strategic questions to ask.
Dehne also noted that a person does not get invited to be a board member because of their title as “lawyer”; rather, they earn that invitation as a well-rounded executive, and it takes time to grow into that role. Ingram added on that “there is a preconceived notion on how you are going to show up [as a lawyer]. You want to challenge that notion from day one.” In that context, the panel discussed that lawyers must shift from problem solver to challenge tester in a board role. A board member is expected to work with management but also to challenge assumptions. Ultimately, the board has to step back and let management solve the problems and do the work—a potentially difficult role shift for lawyers who are used to being the problem solvers in their organization.
The Importance of Guardrails
When the panel explored the boundaries that help separate the role of a lawyer from that of a board member, the main takeaway from the discussion was that lawyers need to stop focusing primarily on risk, which is “lawyer speak,” Ingram said. One way to make this leap is to reframe risk as assumptions. Ingram thinks that all assumptions are risk because they are unproven, and every strategic decision is built on assumptions. Dehne pointed out that “we live in crisis,” and, in this volatile world, boards must make swift decisions in gray space. She went on to point out the importance of shifting from defense (risk identification) to offense.
A Lawyer’s Path to the Boardroom
The panelists provided the following tips for anyone who might be looking to make the jump from lawyer to director:
Make it obvious on your LinkedIn profile that you are interested in board work, as many boards use search firms to identify potential directors.
Branding matters. Know your “why,” your brand, and your positioning. It is important to be able to articulate the value you can bring from day one. If you have not really thought your future role as director through, you are doing yourself a disservice.
When forming your value proposition, pay attention to why people are coming to you. Listen to what people are already saying about you. Massage this into a narrative that you can repeat.
Governance and strategic experience are an asset.
Understand a potential board’s governance and processes for adding new directors, evaluating directors, and term limits. Ensure those align with what you are looking for in a board role.
Key Takeaways
For those looking to parlay their legal skills into opportunities in the boardroom, it is clear that a legal career helps build key competencies that lend themselves well to a director role. The panel made clear that, while lawyers generally bring value, a prospective director should be thoughtful and able to articulate their unique value and skills. As a director, a lawyer should be able to take off the lawyer hat, ask the probing questions, lean into risk (instead of just identifying it), and ultimately let others (i.e., the management team) work to solve the problem.
Benjamin R. Norman Daniel L. Colston Agustin M. Martinez Gabrielle E. Supak Sabrina Y. Greer
Brooks, Pierce, McLendon, Humphrey & Leonard LLP 2000 Renaissance Plaza 230 North Elm Street Greensboro, NC 27401 336.271.3155 www.brookspierce.com
Jennifer M. Rutter
FBT GIBBONS LLP 300 Delaware Avenue, Suite 1015 Wilmington, DE 19801 302.518.6320 www.fbtgibbons.com
Marc E. Williams
Nelson Mullins Riley & Scarborough LLP 949 Third Avenue, Suite 200 Huntington, WV 25701 304.526.3500 www.nelsonmullins.com
Michael W. Tankersley
Alston & Bird LLP 2200 Ross Ave., Suite 2300 Dallas, TX 75201 214.679.2369 www.alston.com
Christopher C. Palermo
Harris Beach Murtha Cullina PLLC 445 Hamilton Avenue White Plains, NY 10061 212.687.0100 www.harrisbeachmurtha.com
§ 1. Introduction
This edition of Recent Developments describes developments in business courts and summarizes significant cases from a number of business courts with publicly available opinions.[1] There are currently functioning business courts of some type in cities, counties, regions, or statewide in twenty-six states: (1) Arizona; (2) Delaware; (3) Florida; (4) Georgia; (5) Illinois; (6) Indiana; (7) Iowa; (8) Kentucky; (9) Maine; (10) Maryland; (11) Massachusetts; (12) Michigan; (13) Nevada; (14) New Hampshire; (15) New Jersey; (16) New York; (17) North Carolina; (18) Ohio; (19) Pennsylvania; (20) Rhode Island; (21) South Carolina; (22) Tennessee; (23) Texas; (24) Utah; (25) West Virginia; and (26) Wyoming.[2] States with dedicated complex litigation programs encompassing business and commercial cases, among other types of complex cases, include California, Connecticut, Minnesota, and Oregon.[3] The California and Connecticut programs are expressly not business court programs as such.[4]
§ 2. Recent Developments
§ 2.1. Business Court Resources
American College of Business Court Judges. The American College of Business Court Judges (ACBCJ) provides judicial education and resources, in terms of information and the availability of its member judges, to those jurisdictions interested in the development of business courts.[5] The ACBCJ’s Twentieth Annual Meeting took place in Newport Beach, California, from February 25, 2026, to February 27, 2026.[6]
Section, Committee, and Subcommittee Resources.The ABA Business Law Section provides a Diversity Clerkship Program that sponsors current first or second-year law students of diverse backgrounds in summer clerkships with business and complex court judges.[7] The ABA Business Law Section has created a pamphlet, Establishing Business Courts in Your State, which is available among other resources in the online library for the Business and Corporate Litigation Committee’s community web page.[8] The Business and Corporate Litigation Committee’s Subcommittee on Business Courts provides documents and/or hyperlinks to business court resources.[9] This includes links to public sources and legal publications, as well as business court related materials and panel discussions presented at ABA Business Law Section meetings. The Section also has established a Business Courts Representatives (BCR) program,[10] where a number of specialized business, commercial, or complex litigation judges are selected to participate in and support Section activities, committees, and subcommittees. These BCRs attend Section meetings, and many have become leaders within the Section. Judge Daniel Collins of the U.S. Bankruptcy Court, District of Arizona in Phoenix and Judge David Cunningham of the Los Angeles Superior Court serve as BCRs for the 2024-2026 term while Judge Kathleen M. Miller of the Superior Court of Delaware and Judge Brian Stern of the Rhode Island Superior Court serve as BCRs for the 2025-2027 term.[11] Finally, this publication has included a chapter on updates and developments in business courts every year since 2004.
Other Resources. “The National Center for State Courts (NCSC) and the Tennessee Administrative Office of the Courts (AOC) developed an innovative training curriculum[12] and faculty guide[13]—along with practical tools—to help state courts establish and manage business court dockets more efficiently and effectively.”[14] The Business Courts Blog,[15] created by Lee Applebaum and now guided by Doug Toering, aims to serve as a national library to those interested in business courts, with posts on past, present, and future developments. This includes posts on reports and studies going back twenty years, as well as recent developments in business courts.[16] In 2025, articles and reports addressed various aspects of business courts.[17] There are also various legal blogs with content relating to business courts in particular states.[18]
§ 2.2. Developments in Existing Business Courts
§ 2.2.1. Florida’s Complex Business Litigation Courts
Following 2023’s expansion from six business court divisions to seven, with a few exceptions, little has changed in Florida’s business courts. Judge Chad K. Alvaro was appointed to preside over the Ninth Judicial Circuit’ new (for 2023) business court division in Osceola County (Division 23), as well as the pre-existing business court division in Orange County (Division 43).[19] In the Eleventh Judicial Circuit, Judges Thomas Rebúll (Division 43) and Lisa Walsh (Division 44) continued to preside over the business court divisions.[20] However, in early 2025, a new administrative order establishing certain new procedures for the business court divisions was entered, which also indicated that revised Complex Business Litigation Rules and Procedures for the Eleventh Circuit were to be published (though that has not yet occurred).[21] The new administrative order specifies which types of cases are subject to mandatory and discretionary assignment to the complex divisions, as well as which cases shall not be assigned, and certain case management, assignment, and transfer procedures related to situations in which the number and complexity of cases already assigned to the divisions warrants suspension of further transfers of cases. In the Seventeenth Judicial Circuit, newly-appointed Chief Judge Carol-Lisa Phillips (Division 26)[22] continued to preside over one business court division and was joined by Judge David A. Haimes (Division 07),[23] who now presides over the other division following the retirement of Chief Judge Jack Tuter in May of 2025.[24] In the Thirteenth Judicial Circuit, Judge Darren Farfante (Division L) continued in his role presiding over the business court.[25]
§ 2.2.2. Georgia State-wide Business Court
The Georgia State-wide Business Court—which started accepting filings on August 1, 2020—celebrated its fifth anniversary in 2025. The Court issued a press release with administrative data showing that, as of July 31, 2025: 124 cases had been filed in the Court since its inception; 96 cases closed with a 299-day average disposition time and 10-day average wait time for orders on ripe motions; 1,010 orders issued; 108 hearings conducted; 3 jury trials held; and about $1 billion in controversy.[26] The Honorable William “Bill” Grady Hamrick, III and his team reflected on the milestone. Judge Hamrick said that passing the 100-cases-filed mark in spring 2025 was especially meaningful given the Court’s limited jurisdiction. He also conveyed that the Court expected AI generated briefing to become a recurring issue.[27]
Two pieces of legislation relevant to the Georgia State-wide Business Court were enacted in 2025. First, HB 86—part of the state’s judicial-compensation reform—amends provisions of the Georgia Code relating to annual salaries of certain state officials, among them, the judge of the Georgia State-wide Business Court.[28] Second, HB 179, as relevant, provides for digital recording of Business Court proceedings, including trials.[29]
§ 2.2.3. Iowa Business Specialty Court
The Iowa Supreme Court adopted an Amended Memorandum of Operation on August 19, 2025, modifying the Business Court’s operation to improve its operations and enhance access to the court.[30] The 2025 amended memorandum replaced the January 18, 2022, Amended Memorandum of Operation in its entirety.[31] The 2025 amended memorandum continues to specify the types of cases that are eligible for the Business Court.[32] However, the Iowa Supreme Court clarified that medical malpractice and dissolution of marriage cases are ineligible for the Business Court docket.[33] And it clarified that legal malpractice cases are also ineligible unless a case arises from an underlying dispute that would otherwise meet the eligibility criteria.[34] While continuing to outline the procedural mechanics on transferring matters to and from the Business Court, the 2025 amended memorandum included a change that allows a presiding business court judge to transfer a case back to the regular docket if the judge determines the case no longer meets the eligibility criteria for the Business Court’s docket.[35] Any decision to transfer the case back to the regular docket is not subject to review or appeal.[36]
§ 2.2.4. Maryland Business and Technology Courts
In April 2025, the Maryland Standing Committee on Rules of Practice and Procedure proposed new Rule 15-1601, which would for the first time establish a comprehensive procedural framework for derivative actions in Maryland courts. Proposed at the recommendation of Senior Appellate Judge James Eyler and members of the Maryland State Bar Association Business Law Section, the rule is modeled on Federal Rule of Civil Procedure 23.1 and Delaware law. It would require plaintiffs to plead with particularity the facts supporting their entitlement to bring a derivative cause of action, and the efforts made to obtain the desired action from the entity, mandate that the plaintiff fairly and adequately represent the interests of the business entity, require court approval for any settlement or voluntary dismissal, and authorize an award of reasonable attorneys’ fees. The proposed rule applies to derivative actions against any business entity, including corporations, limited liability companies, and limited partnerships, and fills a significant gap in Maryland’s procedural framework, which previously contained no statute or rule specifically governing the initiation and maintenance of such actions.
§ 2.2.5. Michigan Business Courts
Appointment of Business Court Judges. The business court legislation became effective January 1, 2013.[37] The terms for the business court judges are six years.[38] On March 6, 2025, the Michigan Supreme Court announced who was reappointed as business court judges as well as new appointments to the business courts.[39]
Statutory Developments. House Bill 4840 overwhelmingly passed the Michigan House of Representatives. That bill clarifies that shareholder litigation and litigation among LLC members under Mich. Comp. L. §§ 450.1489 and 450.4515 would be assigned to the business court, regardless of whether the company is a party to the suit. It also clarifies that enforcement of business court judgments would occur in the business courts. The bill has advanced to the Michigan senate.
Conferences. On April 10, 2025, the LLC & Partnerships Committee, the Corporate Laws Committee, and the Commercial Litigation Committee co-sponsored a program on succession planning, shareholder/LLC member litigation, estate planning, drafting, valuation, and tax. The program included helpful insight from eight business court judges as well as distinguished attorneys.[40]
The 19th meeting of the American College of Business Court Judges occurred in Traverse City from April 30 to May 2, 2025. Michigan Court of Appeals Judge (and former business court judge) Christopher Yates presided as President, and Oakland County Business Court Judge Michael Warren was elected as a Director.
On September 12, 2025, four current or former business court judges spoke at the annual Business Law Institute, presented by the State Bar of Michigan’s Business Law Section and Michigan Institute for Continuing Legal Education.
Then on October 23, 2025, the Michigan Judicial Institute hosted a program for the Michigan business court judges and invited mediators.[41] The subject was “Business Court Mediation: Advanced Strategies and Techniques for Settling Cases.”
Publications. The Michigan Business Law Journal publishes a regular column, Touring the Business Courts. In 2025, three columns were published: Spring 2025[42]; Summer 2025[43]; and Fall 2025.[44] These included interviews with Judge James S. Jamo (Ingham County), Judge Carol Ann Kuhnke (Washtenaw), and Judge Matthew W. Antkoviak (Allegan) as well as summaries of developments in Michigan’s business courts.
Business Court Statistics. The Michigan State Court Administrative Office has established a “dashboard” that allows the user to obtain a trove of information on Michigan courts. The user can manipulate the information. One can sort by business court case type (BC) and run information for the entire state or just for particular counties. The dashboard can also show the method of disposition.[45] The most comprehensive, “one-stop” source of information about the Michigan business courts may be found at https://www.courts.michigan.gov/administration/trial-court/trial-court-operations/business-court/. Updates on Michigan’s business courts (and business courts throughout the country and, in some cases, worldwide) may be found at www.businesscourtsblog.com.[46]
§ 2.2.6. New York Commercial Division
Business Courts Generate Tax Revenues for State Governments.For many years, bar associations and many other organizations and individuals throughout the United States have supported the provision of adequate resources to the Judiciary to enable it to fulfill its Constitutional responsibilities. For many years, these bar associations have been met with the perception that the courts are a “cost center” that incurs expenses for its operations but does not generate revenues. The New York County Lawyers Association (NYCLA) has now submitted written testimony to the New York State Joint Legislative Budget Hearing which demonstrates that that perception is not always true. Instead, as NYCLA’s written testimony demonstrates, New York’s business court attracts businesses and business activities to New York State and thereby adds jobs and increases tax revenues.
In its unprecedented and potentially transformative written testimony, NYCLA has asked the New York State Legislature to take these very substantial economic benefits into account when it makes decisions about funding the New York State Courts. This is the first time that a major bar association has urged the Legislature to consider what NYCLA described as “The Judiciary’s Magnificent Contributions to Economic Development and Tax Revenue in New York State.”
NYCLA’s written testimony was approved by NYCLA’s Board of Directors on February 11, 2026. NYCLA’s testimony was submitted on February 26, 2026, to the New York State Joint Legislative Budget Hearing on Economic Development in connection with the Fiscal Year 2027 Budget Request of the New York State Unified Court System.
In its written testimony, NYCLA briefly describes its mission and activities, the Commercial Division of the New York State Supreme Court, the Commercial Division’s contributions to economic development and generation of tax revenues, and the national and international trend toward creation of business courts as economic development vehicles. NYCLA’s written testimony contains a link to a 12-minute film about the Commercial Division which features court leaders, Commercial Division Justices, more than a dozen Chief Legal Officers of major corporations, leaders of business organizations, and prominent practitioners.
§ 2.2.7. North Carolina Business Court
New Judge Joins North Carolina Business Court. On February 17, 2025, the Honorable Matthew T. Houston was designated as a Special Superior Court Judge for Complex Business cases (the process that appoints a judge to the North Carolina Business Court). Judge Houston’s chambers are located in Raleigh. Prior to joining the Business Court, Judge Houston served as a Special Superior Court Judge presiding over civil and criminal sessions of court throughout North Carolina. Before he began his judicial service, Judge Houston was a partner at K&L Gates LLP.
§ 2.2.8. Texas Business Court
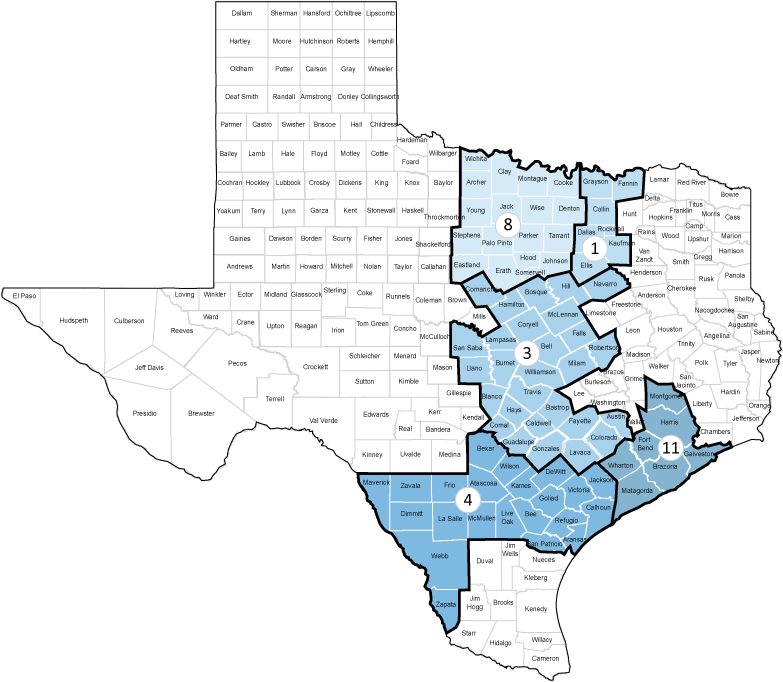
2025—The first full year of operation of the Texas Business Court and Fifteenth Court of Appeals. The Texas Business Court, created by the 2023 Texas Legislature’s enactment of House Bill 19 (HB 19 (2023)), opened its doors on September 1, 2024. The court is staffed by ten judges appointed to the court by Governor Abbott in June of 2024 to serve five multi-county Business Court divisions encompassing the state’s major business and population centers.[47] Six additional Business Court Divisions, covering the remainder of the state, were also created in 2023 but remain inactive, having not been funded by the Texas Legislature at this point.
The 2023 Texas Legislature also created the Fifteenth Court of Appeals (15th COA)[48] as the state’s first specialized appellate court, with statewide geographic reach, that serves as the exclusive destination for appeals of orders and decisions of the Business Court.[49] That court also opened its doors on September 1, 2024, with three justices appointed by Governor Abbott.[50] Unlike the Business Court judges, who are subject to reappointment by the governor at the expiration of their two-year terms on August 31, 2026, and every two years thereafter, the 15th COA justices are standing for election to six year terms on a statewide basis, commencing with the November 2026 general election, and are each opposed by a Democrat candidate.
The Business Court received a total of 56 case filings (averaging 14 per month) during its first four months of operation in 2024. The court received 230 case filings in 2025, averaging 15 per month during the first six months of the year and 23 per month during the second six months.[51] The Eleventh and First Divisions based in Houston and Dallas, respectively, continued to receive the lion’s share of filings (99 in 2025 for the Eleventh, 65 for the First). The Business Court judges issued 55 opinions in 2025 applicable to 45 individual cases.[52] Of those cases only two represented decisions on the merits disposing of the case, which are discussed below.
The Business Court addressed the imbalance of case filings received in the Eleventh Division (Houston) by making random assignments of 29 of those cases to judges from the Third (Austin—10 cases), Fourth (San Antonio—12 cases) and Eighth (Fort Worth—7 cases) Divisions in reliance upon Texas Government Code (TGC) Sec. 25A.009(f): “(f) To promote the orderly and efficient administration of justice, the business court judges may exchange benches and sit and act for each other in any matter pending before the court.”
The statute is further reflected in Business Court Local Rule 2:
The administrative presiding judge may reassign cases for the purpose of equalizing the docket. The trial and all in-person hearings in a reassigned case will remain in the same Division regardless of the judge assigned, absent the agreement of all parties. When a case is reassigned for any reason, the assigned judge’s forms, templates, and division-specific guidelines and procedures, if any, govern.[53]
It is important to note that these cases have not been transferred out of the Eleventh Business Court Division where they were initially filed; the cases continue in the Eleventh Division and the assigned judges are sitting as judges of that Division. In-person hearings and trial settings are occurring in chambers and courtrooms physically located in the Eleventh Division unless the parties agree otherwise. While the Business Court is early in its life as an active trial venue, several instances have already occurred where the parties have agreed to move the situs of trials or hearings for convenience or to obtain a more suitable location.
Business Court Legislation in the 2025 Texas Legislature. HB 19 (2023) enacted by the 2023 Texas Legislature to create the Business Court was a 30-page bill that has been described as making the most significant changes in the Texas court system in a century. It provided the necessary foundation to support the 2025 “Y’all Street” phenomenon, leading to three stock exchanges establishing branches in Texas and the development over the past 18 months of unprecedented competition among Delaware, Texas and Nevada, among others, to serve as preferred issuers of corporate charters for publicly traded companies and preferred venues for resolution of their disputes.
House Bill 40 (HB 40 (2025)),[54] the Business Court Improvements Act, enacted in the final hours of the final day of the 2025 Texas Legislature, clocked in at a robust 45 pages, a 50% increase over 2023. It has had a decidedly less seismic effect on the Texas judiciary and commercial litigation practice. A majority of HB 40 (2025) consists of amendments to Texas Government Code (TGC) Chapters 24 and 25A, and the Texas Civil Practice and Remedies Code (TCPRC), to add numerous references to the Business Court in statutes governing Texas courts generally.
The balance of HB 40 (2025) clarifies and makes technical corrections and modest improvements in the law applicable to the existence and functioning of the Business Court, including, among other things, provisions that:
Confirm that the Business Court’s subject matter jurisdiction includes:
Actions arising from or relating to the ownership or use of intellectual property and protection of trade secrets; (TGC Sec. 25A.004(d)(4), (5))
Actions relating to domestic and international arbitral proceedings subject to TCPRC Chs. 171 or 172, the Federal Arbitration Act or pursuant to arbitration agreements, which may provide for the Business Court to decide questions of law (which may then then be appealed to the 15th COA), if a claim included in the arbitral proceeding is described in TGC Sec. 25A.004(b) or (d); (TGC Sec. 25A.004(d-1)) and
Actions described in the Texas Business Organizations Code (TBOC) where Texas district courts are granted general or exclusive jurisdiction over certain matters;[55] (TGC Sec. 25A.004(b))
Reduce the required amount in controversy for Business Court jurisdiction over disputes relating to “qualified transactions” and other business, commercial and investment agreement claims from $10 million to $5 million; (TGC Secs. 25A.001(14), 25A.004(d))
Confirm that in determining whether an action satisfies the $5 million “qualified transaction” and “amount in controversy” requirements, related transactions and claims are to be aggregated. (TGC Secs. 25A.001(14), 25A.004(i))
Direct the Texas Supreme Court to adopt rules for the Business Court that will support the prompt and final determination of jurisdictional questions;[56] (TGC Sec. 25A.0041)
Direct the Texas Supreme Court to adopt rules that will allow a civil action commenced before September 1, 2024, that is within the subject matter jurisdiction of the Business Court to be transferred to the Business Court upon an agreed motion of a party and permission of the Business Court; [57] (TGC Sec. 25A.021)
Provide for Business Court cases to be transferred for pretrial proceedings in the state’s multidistrict litigation program and for the judicial panel on multidistrict litigation to transfer cases to the Business Court for pretrial proceedings if the Business Court has jurisdiction; (TCPRC Sec. 74.162)
Authorize active judges and justices having the requisite qualifications (35 or older, 10 years of experience in complex civil business litigation or service as a judge of a court with civil jurisdiction) to serve as visiting judges of the Business Court, and authorize Business Court judges to serve as visiting judges of district courts located in their divisions, when approved by the Chief Justice of the Texas Supreme Court; (TGC Sec. 25A.014)
Move Montgomery County, located in the inactive Second Division of the Business Court (which is adjacent to Harris County (Houston) and is the home of large public companies, such as Exxon Mobil Corporation and Occidental Petroleum), to the active Eleventh Division of the Business Court that includes Harris County; (TGC Sec. 25A.003(d), (m)) and
Move Bastrop County, also located in the inactive Second Division (but which is adjacent to Travis County (Austin) and is the home of large public companies, such as Starlink and Agilent), to the active Third Division of the Business Court that includes Travis County.[58] (TGC Sec. 25A.003(d), (e))
Senate Bill 29 (SB 29 (2025))[59] provides the Business Court with the first instances in which it is given exclusive jurisdiction to hear specific types of cases. Section 9 of the Bill adds a new TBOC Section 21.4161, applicable to a corporation having voting shares listed on a national securities exchange (as defined), or that has made an affirmative election to be governed by TBOC Section 21.419. It empowers such a corporation that adopts a resolution to form a committee of independent and disinterested directors under TBOC Section 21.416(g) to “petition a court having jurisdiction to hold an evidentiary hearing to determine whether the directors appointed to the committee are independent and disinterested . . .” with respect to specified transactions. New TBOC Section 21.4161(b) provides that the referenced petition “shall be filed in the business court unless the corporation’s principal place of business in this state is located in a county not contained within an operating division of the Business Court . . . .”
Section 14 of the Bill amends TBOC Section 21.554 to provide that the board of directors of a corporation having voting shares listed on a national securities exchange that receives a demand relating to a threatened derivative proceeding should respond by petitioning “the court having jurisdiction” to make a finding as to whether the directors or committee responding to the allegations are “independent and disinterested” with respect to the allegations. If no derivative proceeding has yet been instituted, Section 21.554 provides that the petition is to be filed by the corporation “in the business court unless the corporation’s principal place of business in this state is located in a county not contained within an operating division of the business court . . . .”
Does the Texas Business Court Comply with the Texas Constitution? The 2024 edition of this article reported that while the 15th COA had received a prompt challenge asserting its failure to comply with the Texas Constitution, resolved by an August 2024, 9-0 opinion of the Texas Supreme Court in In Re Marian Brown[60] confirming that court’s validity, as of mid-2025 no party to a Business Court proceeding had yet sought to assert that it suffered any constitutional weakness. Maintaining a lookout for constitutional challenges to the Business Court is not too difficult—they are required to be filed in the Texas Supreme Court, and may not be filed in a trial court, by Section 4(a) of HB 19 (2023), which provides: “The Texas Supreme Court has exclusive and original jurisdiction over a challenge to the constitutionality of this Act or any part of this Act and may issue injunctive or declaratory relief in connection with the challenge.”[61]
The disinterest of top Texas trial lawyers in raising such questions while vigorously seeking to keep their clients out of the Business Court was attributed to (i) the clarity provided by the In Re Marian Brown decision and a 1950 Texas Supreme Court opinion[62] that confirmed the constitutionality of a similar legislatively created court, (ii) 1985 amendments to Article V, Section 8 of the Texas Constitution confirming the broad and complete authority of the Texas Legislature to make changes in district court jurisdiction,[63] and (iii) a concise, well-argued October 2024 Texas Lawyer article by Chief Justice (Ret.) Tom Phillips and Matthew Hilderbrand that concluded “In our view, there should be no doubt that the business court is well within the legislative prerogative to create.”[64]
The constitutional pass received by the Business Court may have come to an end in the late Fall of 2025 when the plaintiffs in two cases removed by the defendants to the Eleventh Division of the Business Court from district courts in Houston countered with motions seeking remand of those proceedings to the originating district courts and gave notice of their intent to challenge the constitutionality of the Business Court if their remand motions failed (which they have at this point): Unico Commodities, LLC, v. Castleton Commodities International LLC[65] and Brown v. Exxon Mobil Corporation.[66]
The uncertainty suggested by use of the word “may” above is intentional. While the plaintiffs in each case have made filings in the Business Court and with the Texas Attorney General asserting the unconstitutionality of the Business Court, neither has thus far made the required filing in the Texas Supreme Court, the only Texas court having jurisdiction to hear that claim. The plaintiffs’ filings provide only summary briefing to support their positions. Their arguments based in the Texas Constitution do no more than repeating positions that opponents of the Business Court argued to the 2023 Texas Legislature, unsuccessfully. Tellingly, neither the plaintiffs’ Business Court filings nor any other legal writing in Texas over the past two years addresses, much less calls into question, any of the arguments supporting Business Court constitutionality referenced above.
Observers of these two proceedings have suggested that (i) in Unico, plaintiff’s counsel may not have been aware of Section 4(a) of HB 19 (2023) giving the Texas Supreme Court exclusive authority to hear a constitutional challenge to the Business Court, and (ii) in Brown, the assertion of constitutional objections may reflect an early-stage tactical move by plaintiff’s counsel rather than a strong intention to pursue a constitutional challenge. In the meantime, it appears that the judges in each case (Judge Dorfman of the Eleventh Division in Unico, Judge Sweeten of the Third Division in Brown (sitting by assignment in the Eleventh Division)) have thus far declined to any take action on the constitutional challenges, essentially ignoring them, in view of the court’s complete lack of authority to hear such claims.
The constitutional challenges do not appear to have resulted in any slowing of the rate of case filings in the Business Court or public expressions of concern by Texas lawyers active in Business Court practice. Given the precedent of In re Dallas County, where the Texas Supreme Court determined the 15th COA’s constitutionality in three months’ time, start to finish, if either plaintiff does move forward with the required filing in the Texas Supreme Court, a decision would be expected on a similarly expedited timetable.
§ 2.2.9. Wisconsin Commercial Docket Pilot Project
Update following 2024 Termination of the Commercial Docket Pilot Project. For 2025, Wisconsin still has not reactivated steps toward another business court pilot program. In 2024, the Wisconsin Supreme Court voted 4-3 to conclude Wisconsin’s Commercial Docket Pilot Project, which began in 2017. Twenty-six Wisconsin counties participated in the program during its 5-year run: Waukesha, Dane, Racine, Kenosha, Walworth, Brown, Door, Kewaunee, Marinette, Oconto, Outagamie, Waupaca, Ashland, Barron, Bayfield, Burnett, Chippewa, Douglas, Dunn, Eau Claire, Iron, Polk, Rusk, St. Croix, Sawyer, and Washburn.
The Project was originally approved in 2017 for a three-year term and was extended in 2022 for an additional two years, with an end date of July 30, 2024. On May 30, 2024, the Business Court Advisory Committee filed a petition seeking to extend the Project until July 1, 2026. The Supreme Court voted to solicit public comments regarding the Committee’s petition and temporarily extended the Project while disposition of the petition was pending. Those comments were considered at a public hearing on September 24, 2024. Following that hearing, the Court met in an open administrative conference where they voted to deny the petition and terminate the Project. On October 7, 2024, the Court ordered that no additional cases shall be assigned to the commercial court docket, but cases already assigned to the commercial court docket shall continue under the existing interim rules pending further order of the Court. Chief Justice Annette Kingsland Ziegler, Justice Rebecca Grassl Bradley, and Justice Brian Hagedorn dissented. The Court has not since issued any orders regarding dissolution of the Project. Although there is some discussion about proposing a new pilot program to the Court, there were no new developments during 2025.
No 2025 Opinions. The Wisconsin Commercial Docket did not publish any written decisions in 2025 since the Pilot Program concluded in 2024.
§ 2.2.10. West Virginia Business Court Division
The Supreme Court of Appeals of West Virginia has adopted a process for managing and resolving business-related litigation through the establishment of a Business Court Division. The Division is governed by West Virginia Trial Court Rule 29.
The Division consists of up to seven (7) active or senior status circuit court judges appointed by the Chief Justice of the Supreme Court of Appeals. Each appointment is for a term of seven (7) years. The Chief Justice designates a judge of the division every three years to serve as its chair, presiding over the Division’s activities and reporting to the Supreme Court of Appeals.
The West Virginia Business Court Division rules specifically define business litigation as:
(1) the principal claim or claims involve matters of significance to the transactions, operations, or governance between business entities; and
(2) the dispute presents commercial and/or technology issues in which specialized treatment is likely to improve the expectation of a fair and reasonable resolution of the controversy because of the need for specialized knowledge or expertise in the subject matter or familiarity with some specific law or legal principles that may be applicable; and,
(3) the principal claim or claims do not involve: consumer litigation, such as products liability, personal injury, wrongful death, consumer class actions, actions arising under the West Virginia Consumer Credit Act and consumer insurance coverage disputes; non-commercial insurance disputes relating to bad faith, or disputes in which an individual may be covered under a commercial policy, but is involved in the dispute in an individual capacity; employee suits; consumer environmental actions; consumer malpractice actions; consumer and residential real estate, such as landlord-tenant disputes; domestic relations; criminal cases; eminent domain or condemnation; and administrative disputes with government organizations and regulatory agencies, provided, however, that complex tax appeals are eligible to be referred to the Business Court Division.
Business Litigation transferred to the division by the Chief Justice is assigned a presiding and a resolution judge by the Division’s chair. The case remains in the county of origin, but the presiding judge may conduct hearings and trials in any circuit courtroom within the assignment region.
In the past year, two new judges have joined the Business Court Division. Judge Jennifer Bailey of Kanawha County was appointed following Judge Maryclaire Akers’ decision to step down from the Division, and Judge Jeffrey D. Cramer of Marshall County assumed a seat after the expiration of Judge Andrew Dimlich’s term. During this period, six motions to refer cases to the West Virginia Business Court Division were filed, of which the Supreme Court of Appeals approved two. At present, eighteen cases remain pending before the Division. The most significant recent decisions involving the Business Court Division are summarized below.
§ 2.2.11. Wyoming Chancery Court
The year 2025 marked the Wyoming Chancery Court’s first full year operating with a full-time judge and dedicated staff. Benjamin Burningham (co-editor of this publication) was sworn in on January 2, 2025, and assumed responsibility for all pending and newly filed chancery matters.
During the year, the court resolved 48 cases, an increase from 36 in 2024 and 27 in 2023, continuing the court’s steady growth. With full-time staff and a manageable caseload, the court resolved cases in an average of 116 days from filing and issued written decisions on motions within an average of 10 days following the close of briefing or oral argument. These metrics reflect the court’s ongoing emphasis on expedited resolution.
In addition to resolving cases promptly, the court launched a public outreach campaign. Judge Burningham delivered presentations to bar associations, law firms, chambers of commerce, and civic organizations to increase awareness of the court’s role in Wyoming’s business and legal landscape.
The court’s procedural rules saw no significant amendments in 2025. However, the Chancery Court Division of the Permanent Rules Advisory Committee undertook a comprehensive, year-long review of the court’s rules and procedures and has proposed updates for adoption in 2026.
§ 3. 2025 Cases
§ 3.1. Arizona Commercial Court
Bingham Restoration LLC v. State Farm Mutual Automobile Insurance Company[67](Assignability of post-loss insurance rights under anti-assignment provisions). This order addresses whether an insured’s right to demand appraisal and right to bring a bad faith lawsuit in a first-party context may be validly assigned to a third-party restoration company when the applicable insurance policies contain anti-assignment provisions. Plaintiffs Bingham Restoration and Dry Star Restoration obtained post-loss assignments of benefits from State Farm’s insureds after performing emergency mitigation services.
The court acknowledged that under Farmers Insurance Exchange v. Udall, 245 Ariz. 19 (App. 2018), a post-loss breach of contract claim is assignable even in the face of an anti-assignment provision, but it held that the Udall framework does not extend to the right to demand appraisal or to pursue a claim for breach of the duty of good faith and fair dealing. The court reasoned that an assignment of “benefits and rights under the policies,” as Plaintiffs characterized it, amounts to an impermissible assignment of the policies themselves. The court further held that even if such claims were theoretically assignable, the claims at issue had not yet accrued at the time of the assignment, and an assignment of a chose in action cannot carry with it an assignment of a right of action for a tort that has not yet been committed, citing City of Phoenix v. Johnson, 51 Ariz. 115 (1938). The court also rejected Plaintiffs’ attempt to invoke collateral estoppel based on a prior trial court ruling in a separate case, holding that the prior decision involved different insureds, was not binding precedent, and did not preclude re-litigation. Summary judgment was granted in favor of State Farm.
Temco LLC v. Micela Properties Inc.[68](Alter ego, constructive trust, and fraud in residential construction dispute). This order addresses multiple claims arising from a cost-plus residential construction management agreement in which the homeowners alleged that the contractor and its principal diverted construction funds for personal use. The court granted summary judgment in favor of the homeowners on claims for breach of contract, breach of the covenant of good faith and fair dealing, fraud, alter ego, and constructive trust, while denying claims for unjust enrichment, consumer fraud, and unpled punitive damages.
On the contract claims, the court rejected the defendants’ argument that the parties’ course of dealing had modified the written agreement, crediting emails from the homeowners that demanded compliance with the original contract terms. The court found that management and cancellation fees totaling over $500,000 were unenforceable penalties under Dobson Bay Club II DD, LLC v. La Sonrisa de Siena, LLC, 242 Ariz. 108 (2017). On the alter ego claim, the court found undisputed evidence that the individual defendant commingled personal and corporate funds in a single bank account and used homeowner funds to purchase a rental property for one of his entities—satisfying the “intermingling of corporate and personal assets” standard under Chapman v. Field, 124 Ariz. 100 (1979). The court imposed a constructive trust on the rental property purchased with diverted funds, invoking A.R.S. § 33-1005, which creates a trust obligation with respect to funds held by a contractor. Notably, the court concluded that no trial on damages was necessary because the defendants failed to come forward with any documentation to dispute the plaintiffs’ damage calculation.
RMOJO Higley LLC v. Caffeine Sunset Inc.[69](Compelling arbitration under a related agreement’s broad arbitration clause). This order addresses whether a promissory note that contains no arbitration clause—but includes a forum-selection provision and integration clause—is nonetheless subject to mandatory arbitration by virtue of a broad arbitration clause found in a related operating agreement executed on the same date. Plaintiff Rmojo and Defendant Caffeine Sunset entered into four interrelated documents on May 19, 2022, to facilitate Rmojo’s purchase of a 49% membership interest in an LLC formed to operate a coffee franchise: a Term Sheet, an Operating Agreement, an Intellectual Property Licensing Agreement, and the Promissory Note at issue. The Operating Agreement contained a broad arbitration provision covering “any and all disputes and controversies arising under or in connection with this Agreement.”
Applying the framework set forth in Sun Valley Ranch 308 Ltd. Partnership v. Robson, 231 Ariz. 287 (App. 2012), the court first determined that the arbitration clause was broad, then evaluated the four factors for compelling arbitration of claims under a related, non-arbitration agreement: (1) the documents incorporated or referenced each other; (2) the Note and Operating Agreement related to the same subject matter—the purchase of membership interests; (3) the Operating Agreement’s arbitration exceptions did not apply; and (4) all four documents were executed on the same day by the same parties. Accordingly, the court granted the motion to compel arbitration.
§ 3.2. Delaware Superior Court Complex Commercial Litigation Division
Textron Inc. v. Endurance Am. Ins. Co.[70] (Holding that insurer did not have right to recoupment of payment under reservation-of-rights letter or voluntary payment doctrine). This case involves an insurance coverage dispute stemming from a personal injury lawsuit referred to as the Grace Action, in which a passenger sued Textron alleging that he was injured in an off-highway vehicle made by Textron’s indirect subsidiary. Textron had an insurance policy with Endurance for $25 million in generally liability coverage in limits excess of $75 million. Textron initially notified its insurers, including Endurance, of the Grace Action and that it expected a settlement value in the range of $15 to $20 million. Textron failed to, however, notify Endurance that it was accused of engaging in discovery misconduct in the Grace Action specifically related to its failure to produce evidence of a better-designed option for the off-highway vehicle before settling the matter for $105 million.
Endurance argued that it should be able to recoup its voluntary payment of the settlement amount because Textron’s discovery misconduct caused the exposure in excess of the policy limits. Textron filed a motion for judgment on the pleadings for a declaration that Endurance had no right to recoupment for its payment. The Court agreed with Textron and granted the motion because the insurance policy had no express contractual right permitting Endurance to recoup the payment, and because the voluntary payment doctrine does not apply where Endurance had “full knowledge of the facts” when it made the settlement payment. The Court noted that Endurance’s remedy was to file a lawsuit to determine coverage before agreeing to pay the settlement, or to refuse to pay the settlement and defend itself in a subsequent coverage action.
Movora LLC v. Gendreau[71](Entering judgment in plaintiffs’ favor relating to purchase agreement indemnification provision). In this post-trial opinion, the Court entered judgment in favor of plaintiffs and awarded more than $40 million in damages for defendants’ breach of a membership interest purchase and exchange agreement (the “MIPA”) pursuant to its indemnification provision. This matter arises out of a purchase dispute in which the company being acquired was defending a patent infringement suit throughout the duration of the acquisition. The suit eventually settled for $70 million after execution of the MIPA. The MIPA contained an indemnification provision relating to the ongoing patent infringement suit, pursuant to which the plaintiffs sought indemnification for the settlement payment.
The Court held that plaintiffs proved that the defendants breached the MIPA by not providing indemnification for the settlement after analyzing the plain text of the indemnification provision which contained broad language that was not temporally limited. The Court did not, however, find that plaintiffs could recover for portions of the settlement related to certain licenses because they were purely forward-looking and therefore, not recoverable under the MIPA’s definition of damages. The Court further rejected defendants’ argument that public policy prevents the indemnification of willful misconduct and noted that Delaware is a contractarian state that cautions against voiding otherwise valid indemnity contracts as contrary to public policy.
JanCo FS 2, LLC v. ISS Facility Servs., Inc.[72](Proof of damages for breach of contract must be tied to the particular breach rather than a total figure for multiple claimed breaches and fraud claims). This case involves a purchase agreement dispute in which the seller was accused of fraudulently inducing the buyer into signing the purchase agreement because the business was worth less than disclosed. In the post-trial opinion, the Court found that the seller breached one provision of the purchase agreement but failed to prove any damages for that breach and that the buyer breached the agreement by failing to pay certain post-closing purchase price adjustments.
Specifically, the buyer argued that the seller provided false or misleading financial statements, breached several sections of the purchase agreement, and committed fraud and willful misconduct by concealing the decline of the business. The Court ultimately found that the only breach of the purchase agreement that the buyer proved was that the seller breached the “Absence of Changes Representation” which required the buyer to prove some adverse effect but did not require the adverse effect to be a material one. Post-trial, the Court found that there was some adverse effect as evidenced by an increase in temporary labor costs and other issues. The Court held, however, that the seller did not tie its damages calculation to that specific breach and therefore, failed to prove its damages to a reasonable certainty as required under Delaware law.
§ 3.3. Florida’s Complex Business Litigation Courts
De Simone v. Orlando, et al.[73] (Court lacks personal jurisdiction over dispute alleging plaintiff was defrauded by defendant in Switzerland notwithstanding defendant’s alleged intent to use proceeds of fraud in Florida). Plaintiff Claudio De Simone (“De Simone”)—a resident of Switzerland—alleged that he was defrauded by a trusted business associated, Defendant Salvatore Orlando (“Orlando”)—another resident of Switzerland, and tricked into making a $600,000 loan for the purpose of constructing a certain restaurant in Miami, Florida. Orlando moved to dismiss on the basis of a lack of personal jurisdiction, and by attached declaration swore to his lack of contacts with Florida. De Simone failed to refute Orlando’s declaration and instead focused on his threadbare allegations of a fraudulent scheme and conspiracy to use his funds for the Miami restaurant. The Court determined that, even if it were to accept De Simone’s tort allegations as true, it would nonetheless lack personal jurisdiction because the substantial and essential aspects of the underlying torts (i.e., the lies and resulting transactions which purportedly occurred in Switzerland and other foreign jurisdictions) occurred outside of Florida, and Orlando otherwise lacked sufficient minimum contacts with Florida. The sole Florida connection—that Orlando and the restaurant purportedly had an agreement for Orlando to commit the underlying torts for the Miami restaurant’s partial and eventual benefit—was deemed insufficient to meet the jurisdictional requirement that Orlando be alleged to have committed a substantial aspect of the tort in Florida. “In other words,” the Court found, “conspiracy-imputed jurisdiction still requires that the ‘key events’ underlying the torts upon which the civil conspiracy is based occur in Florida.”[74] On that basis, De Simone’s claims against Orlando were dismissed without prejudice to re-file in an appropriate jurisdiction.
§ 3.4. State-wide Business Court in Georgia
Lincoln Parkway, LLC v. Krystal Restaurants LLC[75] (Grant of motion for judgment on the pleadings under contract interpretation). This lease dispute arose from Krystal’s exercise of a one-time early-termination option in the third amendment to a commercial lease for property on Lincoln Parkway in Atlanta. The third amendment extended the lease through mid-2028 and provided for annual rent abatements and a $348,466 refurbishment allowance for improvements, with up any unused portion (up to $245,976) automatically credited to base rent. It also permitted Krystal to terminate the lease effective June 30, 2025, on timely, “irrevocable” notice and payment of a termination fee. The termination fee, in turn, was calculated based on the unamortized value of leasing commissions, improvement allowances, and any free or abated base rent or base-rent credits. Krystal timely invoked the option, but the parties disagreed over the amount due. Lincoln calculated the fee at over $700,000 by including the full refurbishment allowance—even though no improvements were made and no refurbishment funds had been paid. Krystal disputed the calculation, contending that only amounts actually dispersed to Krystal or incurred by Lincoln in making improvements could be counted. Krystal tendered just under $350,000—less than half of what Lincoln sought. Lincoln then sued for anticipatory repudiation, breach of contract, and declaratory relief. Both sides moved for judgment on the pleadings.
The court denied Lincoln’s motion and granted Krystal’s. Looking to the third amendment, the court recognized that “granted” and “incurred” in the termination-fee provision could support the parties’ competing readings. But the context of the third amendment, as a whole, made clear that those terms referred only to portions of the refurbishment allowance and rent concessions disbursed or realized. The court explained that Lincoln’s contrary interpretation would render the provision’s reference to unamortized value “as of the Termination Date” surplusage. It would also make most of the improvement-allowance language redundant. And it would either double count or eliminate the unused refurbishment allowance by sweeping that amount into both the improvement-allowance and rent-credit components of the fee. Finally, to the extent any ambiguity remained, the court construed the termination-fee provision against Lincoln as its drafter. Krystal had thus timely paid the correct termination fee and neither breached nor repudiated the lease. The court dismissed the complaint and held that Krystal, as the prevailing party, was entitled to recover reasonable attorneys’ fees under the lease.
North American Field Service LLC v. Ole Mexican Foods, Inc.[76](Good cause for additional discovery requests).This case stems from a payment dispute for electrical services performed at three of the defendant’s facilities in Texas, Tennessee, and Georgia. In discovery, the defendant sought leave to serve an additional 430 requests for admissions past Business Court Rule 6-2(b)’s presumptive limit of just 50 RFAs. The court granted the request, in part. It began by rejecting the defendant’s argument that Rule 6-2(b) is constitutionally and statutorily infirm because it allows for less requests than the Georgia Civil Practice Act does, thereby putting the defendant on different footing than civil litigants in other courts. The court found that Rule6-2(b) does not violate due process or the equal protection clause because it applies equally to all parties before the court, and because the Civil Practice Act is silent on how many RFAs a party may serve, Rule6-2(b) did not conflict with that provision either. The court went on, however, to evaluate whether good cause supported the defendant’s additional requests. The court found a deviation from the presumptive limit was proper for 167 of the 480 proposed requests. The court recognized this was “a considerable increase” from the 50 RFAs typically allotted. But the court viewed that increase justified to narrow the issues, given the number of parties, claims, and defenses at issue. Notably, in deciding whether to exercise its discretion, the court examined each of the proposed requests to decide which were supported by good cause and which were not.
Steuer, M.D. v. Tomaras, M.D.[77](The court’s third jury trial). This action centers on a dispute over a neurosurgery practice. The case went to a 14-day trial in March. It was one of only three jury trials conducted in the court since its opening in 2020. The jury returned a verdict, but the parties separately reached a settlement agreement. The court entered a consent final judgment against the defendants in an amount of just over $4 million.
§ 3.5. Iowa Business Specialty Court
Kern v. Seed Savers Exch., Inc.[78](Granting motion to dismiss because conversion claim was time-barred). Plaintiff Judith Kern sued Defendant Seed Savers Exchange, Inc. (“SSE”) alleging that SSE wrongfully converted her deceased husband’s personal effects. SSE had fired her husband and barred him from his office in 2007. He left behind various materials that he had accumulated since he founded SSE. When he asked for these documents after his termination, SSE refused to hand them over. Kern continued to seek the documents after her husband’s death. But SSE refused to provide them without any conditions, and the parties continued to negotiate until Kern sued SSE in 2024. SSE moved to dismiss arguing that Kern’s claim was time-barred.
The Business Court concluded Kern’s claim was time-barred under Iowa Code § 614.1(4), which provides a five-year limitations period for certain civil claims. It determined Kern’s conversion claim accrued when her husband originally demanded his materials in 2007 after termination. The Business Court determined that even assuming SSE became a bailee of the materials, Kern’s claim still accrued when SSE refused to return the materials and SSE claimed to own the materials. The Business Court also rejected Kern’s argument that the discovery rule tolled the limitations period.
In re J. Bruce McDonald Generation Skipping Trust[79](Ruling on petition to invoke jurisdiction over trust and order obligations). Trustee U.S. Bank asked the Business Court to declare its legal obligations after a district court’s prior order required it to pay out certain funds contained in a trust subaccount even though the Iowa Trust Code and the trust’s spendthrift provisions required U.S. Bank to retain the funds. In earlier litigation that did not include U.S. Bank, a judgment creditor sought to garnish funds held in a trust subaccount of which Michael McDonald was a beneficiary after it received a judgment against McDonald. A district court ruled that placing the funds in a trust subaccount constituted distribution and allowed garnishment. Neither party appealed that order. In a later related appeal, the Iowa Court of Appeals concluded issue preclusion prevented it from reconsidering that order, but it also concluded the trust spendthrift provisions generally protect trust money from collection until the beneficiary actually receives it. Thus, U.S. Bank who held a trust subaccount for beneficiary McDonald faced conflicting obligations.
The Business Court held that U.S. Bank was required to comply with the prior garnishment order and disburse the funds to the judgment creditor. The Business Court explained that an appellate court had already determined that the earlier district court order carried preclusive effect because McDonald failed to appeal the distribution issue. But the Business Court clarified that its ruling applied only to the funds previously held in the subaccount and did not undermine the trust’s spendthrift protections more broadly. The Business Court concluded the spendthrift provision would protect the remaining trust principal and income from creditors unless and until the trustee chose to distribute them to McDonald.
Iowa Pathology Assocs., P.C. v. Abbott[80](Issuing findings of fact and conclusions of law after trial on claims that employees established competing business while employed). Plaintiffs Iowa Pathology Associates, P.C. (“IPA”) and a related entity sued Defendants who were four physician-shareholders of IPA, alleging Defendants secretly developed a competing business while still working at IPA thereby breaching their employment agreements, violating a common-law duty of loyalty, and committing civil conspiracy. The Business Court found that before announcing their departure, Defendants incorporated a new entity, developed a business plan, secured business space, retained consultants, obtained regulatory approvals, and established operational infrastructure. Plaintiffs claimed these actions constituted active participation in a competing business and sought damages for lost profits. Defendants counterclaimed, alleging various contract and tort claims.
After trial, the Business Court ruled in favor of Defendants on Plaintiffs’ claims. The Business Court explained that employees may organize a new enterprise before resignation so long as they remain loyal during their employment. The Business Court found Defendants did not solicit IPA’s clients or employees before their departure. It emphasized that Defendants continued working full time for IPA, maintained production levels, and did not begin processing laboratory work for the new business until their employment ended. Thus, the Business Court concluded Defendants’ actions were preparatory acts necessary to establish a new business rather than participation in a competing enterprise. The Business Court then rejected Defendants’ counterclaims except for their claim of unjust enrichment related to a signing bonus paid while Defendants were shareholders of IPA.
§ 3.6. Maine Business and Consumer Docket
LeFevre v. LeFevre[81] (Shareholder litigation closely held corporations). The Maine Business and Consumer Docket’s decision in LeFevre, provides important guidance regarding shareholder litigation in closely held corporations. The dispute arose between a minority shareholder and his sons, who controlled two family-owned businesses as majority shareholders, directors, and officers. The plaintiff alleged that the defendants used corporate assets for personal purposes, paid excessive compensation to family members, restricted his access to corporate information, and excluded him from company affairs. After the companies rejected his statutory demand to investigate and pursue claims against the defendants, the plaintiff commenced both direct and derivative claims for conversion, breach of fiduciary duty, unjust enrichment, fraud, removal of directors, and appointment of a custodian.
The court’s most significant holding concerned standing. Although claims alleging injury to a corporation ordinarily must be brought derivatively, the court emphasized the realities of closely held corporations and permitted the plaintiff to pursue direct claims alongside derivative claims. Relying on Moore v. Maine Industrial Services, Inc., 645 A.2d 626, 629-30 (Me. 1994), the court reasoned that where controlling shareholders allegedly caused and benefited from the misconduct, and the minority shareholder was effectively the sole injured party, strict adherence to derivative-action requirements could produce inequitable results. The court also rejected the defendants’ attempt to rely on the corporation’s demand-response letter as a basis for dismissal, holding that a plaintiff does not adopt the truth of an attached document when the complaint expressly challenges its accuracy and adequacy.
The court denied the motion to dismiss as to the conversion, fiduciary duty, unjust enrichment, and related statutory claims, but dismissed the fraud counts for failure to satisfy M.R. Civ. P. 9(b). Although the plaintiff alleged that improper expenditures and compensation were disguised in corporate records as legitimate business expenses, the complaint failed to identify with sufficient particularity what action the plaintiff or the corporations would have taken absent the alleged misrepresentations. The decision underscores that minority shareholders in closely held corporations may pursue parallel direct and derivative claims, internal investigations generally will not defeat claims at the pleading stage, and fraud claims remain subject to heightened pleading requirements notwithstanding Maine’s notice-pleading standard.
§ 3.7. Maryland Business and Technology Courts
Doe v. MedStar Health, Inc.[82](Class certification in data-privacy litigation).In this putative class action, the plaintiffs alleged that MedStar Health collected and shared patient website browsing data, including data from its myMedStar patient portal, by placing cookies on its web properties and transmitting that data to Google and Facebook for marketing purposes. The plaintiffs asserted claims for violation of Maryland’s Wiretap Act, intrusion upon seclusion, publication of private facts, and negligence.
The Circuit Court for Baltimore City denied class certification on multiple grounds. First, the proposed class was not ascertainable as to patients who merely visited publicly accessible websites because no administratively feasible method existed to identify them.Second, the plaintiffs failed to establish typicality and adequacy because all remaining class representatives used the patient portal, yet the proposed class included members who only visited public webpages.Third, common issues did not predominate for three of the four claims due to individualized inquiries, such as browser configurations and whether disclosures were “highly offensive.”Fourth, the novelty of the plaintiffs’ legal theories precluded a finding that class treatment was a superior method of adjudication.
This opinion reflects the court’s careful application of Maryland Rule 2-231 in emerging data-privacy litigation, underscoring the challenges of demonstrating ascertainability, typicality, predominance, and superiority in technology-driven claims.
Hartman v. Silver Star Properties REIT, Inc.[83](Stockholder rights, charter construction, and corporate governance in a non-traded REIT). Following a six-day bench trial, the Circuit Court for Baltimore City addressed a complex intra-corporate dispute within Silver Star Properties REIT, Inc., a Maryland public non-traded REIT. The plaintiff, Silver Star’s founder, former CEO, and current director, sought, among other things, a declaration requiring immediate liquidation under a charter termination provision, an order compelling an annual meeting, and a declaration voiding a stockholder rights plan (also commonly known as a “poison pill”).
On the liquidation claim, the court construed the charter’s ambiguous termination provision and found, based on Silver Star’s own SEC filings, that the ten-year liquidation deadline had passed. However, the court declined to order immediate liquidation on equitable grounds—including the plaintiff’s own misconduct, Maryland’s strong public policy disfavoring dissolution, and the board’s judgment that liquidation was not in stockholders’ best interest—instead ordering a stockholder vote within six months on whether to liquidate or defer.
Regarding the stockholder rights plan/poison pill, the court upheld its validity, finding that the board adopted it in good faith in response to the plaintiff’s hostile actions and that MGCL § 2-201(c) expressly authorizes such plans. The court further held that the board validly ratified the plan’s triggering under MGCL § 2-703(b)(1), which permits ratification of defective corporate acts with retroactive effect. Finally, the court made express credibility findings adverse to the founder and reserved ruling on a bylaw amendment pending a related appeal.
Kakar v. Privilege Underwriters Reciprocal Exchange[84](Insurer’s duty to defend under a homeowner’s policy against a defamation suit). The Circuit Court for Montgomery County granted summary judgment in favor of the plaintiff, Arvinder Kakar, declaring that his homeowner’s insurance carrier, Privilege Underwriters Reciprocal Exchange (“PURE”), owed him a duty to defend against a defamation lawsuit brought by his former business, Octo Platform Holdings, LLC (“Octo”). The plaintiff sold his company to Octo, served as an employee and director, and subsequently, approximately one year after his employment and board service ended, made allegedly defamatory statements to IBM intended to derail IBM’s acquisition of Octo.
The PURE policy required the insurer to provide a defense “even if the suit is groundless, false or fraudulent” for claims of “personal injury,” including defamation. PURE initially denied coverage based on the absence of an “occurrence” and four policy exclusions. At the motions hearing, however, PURE conceded the “occurrence” issue and relied solely on the four exclusions: the Business Exclusion, the Directors E&O Exclusion, the Contracts or Agreements Exclusion and the Expected or Intended Injury Exclusion.
Relying on Maryland’s broad “potentiality of coverage” doctrine from Brohawn v. Transamerica Insurance Co., the court held that the insurer was obligated to defend and systematically rejected all four exclusions. The Business Exclusion failed because the plaintiff was no longer engaged in any business pursuit when the statements were made. The Directors E&O Exclusion was inapplicable because he had resigned from the board ten months prior. The Contracts or Agreements Exclusion also failed because the underlying lawsuit alleged defamation per se beyond mere contractual non-disparagement breaches. Finally, the Expected or Intended Injury Exclusion was unavailing because, under Virginia law governing the underlying claims, liability could rest on negligence as well as knowing defamation. The court entered judgment for the plaintiff on both the declaratory judgment and breach of contract claims.
The Spruce House Partnership (AI) LP v. CohnReznick LLP[85] (Auditor liability and summary judgment in a professional liability dispute). The Circuit Court for Baltimore City granted summary judgment in favor of CohnReznick LLP, the auditor for GTT Communications (“GTT”), dismissing all three counts: (a) intentional misrepresentation, (b) concealment, and (c) negligent misrepresentation, brought by The Spruce House Partnership, an investment firm that made substantial investments in GTT, including an initial purchase of 4 million shares worth $143 million and a subsequent $170 million commitment related to GTT’s acquisition of Interoute.Spruce House ultimately recorded its GTT shares as worth $0 and abandoned them entirely before GTT filed for bankruptcy on October 31, 2021. Spruce House alleged that CohnReznick issued false audit reports and failed to detect material accounting irregularities. However, the court found that Spruce House’s forensic accounting expert offered only speculative opinions that did not amount to conclusions based on the factual record, and that plaintiffs failed to establish that GTT’s financial statements were materially misstated.
Applying New York law, the court found the claims failed on multiple independent grounds. First, there was no direct communication between CohnReznick and Spruce House, which conducted its due diligence without ever speaking to the auditor. Second, the plaintiffs could not demonstrate reliance because Spruce House’s own principal, Mr. Sternberg, acknowledged in deposition testimony that acting on material nonpublic information about GTT’s financial deficiencies would have been impractical due to insider trading prohibitions, stating that “your choices are very limited at that point in time” and “[y]ou don’t have the option of selling.” The other principal, Mr. Stein, stated that “[i]t’s hard to speculate” what actions Spruce House might have taken in response to an adverse opinion on GTT’s financials. Third, the parties lacked the privity or near-privity required under New York law for negligent misrepresentation claims against auditors.
The court further observed that the alleged wrongdoing was attributable to GTT itself, the SEC’s cease-and-desist order made no reference to CohnReznick, highlighting the court’s rigorous application of summary judgment standards in complex financial and professional liability disputes involving sophisticated investors.
Smith v. Bozzuto Management Company[86] (Debt-collection licensing and statutory interpretation under the MCALA). The Circuit Court for Montgomery County granted Bozzuto Management Company’s motion to dismiss with prejudice in this putative class action brought by a residential tenant. The plaintiff alleged that Bozzuto engaged in unlicensed debt collection activities in violation of the Maryland Collection Agency Licensing Act (“MCALA”) and included a lease provision permitting late fees ten days after the rent due date, in alleged violation of a fifteen-day grace period under Md. Code Ann., Com. Law § 14-1315(f).
The court rejected the plaintiff’s assertion that Bozzuto, as a property management company collecting rent on behalf of an owner, is a “debt collection agency” requiring licensure. Adopting a “primary purpose/incidental nature” test and relying on legislative history, the court concluded that the MCALA was enacted to regulate entities whose primary business is purchasing or collecting consumer debts—not property managers for whom rent collection is merely incidental.[38] The court further found that because Bozzuto signed the lease directly with the plaintiff, it was not collecting rent “for another” within the meaning of the statute, providing an independent basis for its holding.
The court also held that the fifteen-day late fee grace period in Commercial Law § 14-1315(f) does not apply to residential leases, which are neither “goods” nor “services” under the statute. Even assuming Bozzuto qualified as a debt collector, the court found dismissal warranted because the plaintiff failed to allege actual injury—the payment of rent in exchange for use of an apartment does not constitute a cognizable “loss”—and because disgorgement is a remedy reserved exclusively to the Maryland Attorney General’s Consumer Protection Division.
§ 3.8. Michigan Business Courts
Biotech Clinical Laboratories, Inc. v. RSL Medical Marketing, LLC.[87](Liquidated-damages clause unenforceable as penalty). This dispute arose out of a marketing agreement between Biotech Clinical Laboratories, Inc. (“Biotech”) and RSL Medical Marketing, LLC (“RSL”) for the provision of marketing services by RSL in exchange for monthly compensation.
The parties’ agreement contained a restrictive covenant and a liquidated-damages provision, which required Biotech, in addition to any equitable relief, to pay RSL liquidated damages equal to three times the contractor’s last twelve months of compensation for “any breach” of the agreement, including failure to pay earned compensation. After the relationship deteriorated, Biotech sued RSL over a marketing agreement, and RSL asserted a counterclaim for breach of contract seeking to enforce a liquidated damages clause tied to alleged breaches of restrictive covenants. Both parties argued they were entitled to summary disposition on defendant’s counterclaim for breach of contract.
The Oakland County Business Court granted summary disposition in favor of Biotech, determining that the clause was an unenforceable penalty under Michigan law. The court explained that liquidated damages are enforceable only when they reasonably approximate damages that are difficult to calculate at the time of contracting. Here, the provision applied the same large damages amount to any breach of the agreement, including breaches where actual damages, such as unpaid compensation, would be readily ascertainable. Because the fixed amount would be excessive in relation to foreseeable damages in several possible breach scenarios, the court concluded the provision functioned as a penalty rather than a valid liquidated damages clause and therefore could not be enforced.
A123 Systems, LLC v. Voltari Marine Electric Inc., Voltari Electric Inc., and Voltari Power Systems Inc.[88] (Personal jurisdiction in international supply contract dispute). Plaintiff A123 Systems, LLC, a Delaware limited liability company headquartered in Novi, Michigan, did not meet its burden of demonstrating that the court had jurisdiction over defendants: Voltari Power Systems Inc. (“VPS”), a Canadian corporation with its principal place of business in Quebec, Canada; Voltari Marine Electric Inc. (“VME”), a Canadian corporation with its principal place of business in Ontario, Canada; and Voltari Electric Inc. (“VEI”), a Florida corporation with its principal place of business in St. Petersburg, Florida. Accordingly, the court granted the defendants’ motion for summary disposition pursuant to Mich. Ct. R. 2.116(C)(1) for lack of personal jurisdiction.
The underlying dispute involved fourteen purchase orders issued in 2021 and 2022 for the sale of the plaintiff’s battery-related products to the defendants, who would then utilize the parts in their production of electric boats. Plaintiff alleged that defendants failed to pay approximately $1.58 million in outstanding invoices and contractual interest (1.5% per month) after defendants acknowledged the debt but declined to resolve it.
The purchase orders were issued by VPS to plaintiff’s parent company, Wanxiang A123 Systems Asia Co. Ltd. (“Wanxiang A123”), a Chinese company, for batteries Wanxiang A123 manufactured in China and shipped from China to Canada. Wanxiang A123 issued invoices to VPS in Quebec, and invoice payments were made by VPS to Wanxiang A123’s bank account in China. Plaintiff handled all aspects of the contract negotiations with VPS; coordinated the manufacture of the battery products through its parent company Wanxiang A123; was the point of contact with VPS regarding their business partnership, products, purchase orders, invoices, and outstanding balances; and was the sales office that worked directly with VPS to order, source, and ship the products manufactured by Wanxiang A123.
Plaintiff’s complaint alleged that the Michigan court had personal jurisdiction over defendants because they transacted business within the state under Mich. Comp. L. § 600.715. Specifically, the complaint alleged that defendants solicited business within the state and negotiated and entered into contracts for the purchase of goods within the state.
The Oakland County Business Court first concluded that plaintiff failed to present evidence that defendants were present within the state on a regular basis. They did not have a physical location, employees, agents, or a bank account in Michigan. As a result, defendants were not subject to the exercise of general personal jurisdiction under Mich. Comp. L. § 600.711.
As to limited (or long-arm or specific) jurisdiction under Mich. Comp. L. § 600.715, the court found that VPS had transacted business within Michigan and, therefore, the court could exercise limited personal jurisdiction over VPS under Mich. Comp. L. § 600.715. However, plaintiff failed to provide any evidence of a transaction with VEI and VME. Accordingly, the court could not exercise limited personal jurisdiction over VEI and VME under Michigan’s long-arm statute.
With respect to VPS, the court then proceeded to the second step of the analysis, whether the exercise of personal jurisdiction over it would offend due process, which requires that a defendant have a certain minimal contact with the state so that the suit does not offend the traditional notions of fair play.
The court applied Michigan’s three-part test. First, the defendant must have purposefully availed itself of the privilege of conducting activities in the state. Second, the cause must arise from the defendant’s activities in the state. Third, such activities must be substantially connected with the state to make the exercise of jurisdiction reasonable.
The court found that VPS had purposefully availed itself of the privilege of conducting activities in the state. It initiated contact with the plaintiff to solicit business, executed a non-disclosure agreement, engaged in ongoing negotiations with Michigan based personnel, traveled to Michigan for meetings, and sought investment from the plaintiff in the Voltari business. These contacts showed that VPS deliberately reached into Michigan to pursue a business relationship.
With respect to the second factor, however, the court determined that plaintiff’s cause of action, which concerned breached purchase orders and unpaid invoices, did not arise from any activities in the state. The purchase orders and invoices involved products manufactured in China, shipped to Canada, and payable in China, and the alleged breach did not stem from any Michigan-related conduct.
Finally, the court held that exercising jurisdiction would be unreasonable. The transactions occurred outside the state, key witnesses were located elsewhere, and VPS had no presence in the state. Because the alleged breach was not substantially connected to the state, requiring VPS to litigate there would impose a substantial burden. Accordingly, the court found the third prong unsatisfied and granted summary disposition for lack of personal jurisdiction.
Zakaria v. Gjokaj.[89](Summary disposition on contractor fraud, statutory conversion, and breach of construction contract).The Wayne County Business Court granted summary disposition in favor of plaintiffs pursuant to Mich. Court R. 2.116(C)(10) on their breach of contract claim because there was no genuine issue as to any material fact. In March 2022, plaintiffs contracted with defendant Gjokaj and his company, Renaissance Building Services, LLC (“Renaissance”), to build a medical facility. Plaintiffs sued for breach of contract, alleging that defendant Renaissance breached the agreement and left the job unfinished. As a result, plaintiffs allege they paid $499,449.39 over the contract price to complete the project and that they paid $363,600 to subcontractors whom Renaissance allegedly failed to pay.
Renaissance did not dispute that it breached the contract but argued that plaintiffs breached first by providing deficient engineering specifications, excusing its performance. The court rejected this defense because Renaissance produced no admissible evidence supporting that claim and relied only on conclusory assertions. Because Renaissance admitted breaching the agreement and failed to present evidence creating a genuine issue of material fact, the court granted summary disposition in plaintiffs’ favor on the breach of contract claim.
The court also granted summary disposition on plaintiffs’ claims under the Michigan Building Contract Fund Act, Mich. Comp. L. § 570.151 et seq., fraudulent misrepresentation, and statutory conversion. Gjokaj admitted that he retained project funds, failed to pay subcontractors in full, commingled project funds with funds from other jobs, and diverted approximately $221,000 to another project. He also admitted submitting false lien waivers and sworn statements to obtain loan proceeds, including representations that certain subcontractors had been paid when they had not. An affidavit from the title company’s settlement agent further indicated that payments were made based on inaccurate submissions and that approximately $495,000 remained unaccounted for. Because defendants presented no evidence creating a genuine issue of material fact, the court granted summary disposition in plaintiffs’ favor on those claims as well.
Get Health Physical Therapy, LLC v. Yousif[90](Dismissing fiduciary duty claim against nonmember; denying motion otherwise). The Macomb County Business Court granted in part and denied in part defendants’ motion for summary disposition brought under Mich. Ct. R. 2.116(C)(7), (8), and (10) in a lawsuit based on nine causes of action arising from the alleged diversion of patients and misappropriation of funds from a physical therapy business. Plaintiffs, Get Health Physical Therapy, LLC (“Get Health”) and two of its members, filed suit asserting various claims against Yousif, a co-member, members of Yousif’s family, and several competing entities.
Defendants moved for summary disposition under Mich. Ct. R. 2.116(C)(7) (i.e., statutory bar to claim), arguing that most of the claims were barred by the statute of limitations. The court denied defendants’ motion, finding that they failed to establish when the claims accrued. Defendants argued the claims arose from checks issued between 2018 and 2021, but the court found that assertion conclusory and unsupported. The court also noted that some claims, including breach of fiduciary duty and trade secret misappropriation, are governed by a discovery rule. Because discovery had not yet occurred and the record did not establish the accrual dates, it concluded that summary disposition based on the statute of limitations was premature.
Under Mich. Ct. R. 2.116(C)(8) (i.e., failure to state claim), defendants challenged the sufficiency of plaintiffs’ breach of fiduciary duty and unjust enrichment claims. The court denied dismissal of the fiduciary duty claim against Narmin, finding that LLC members owed fiduciary duties under the operating agreement, but dismissed the claim against Nivin because she was not a member of the LLC. The court also denied dismissal of the unjust enrichment claims, holding that the complaint sufficiently alleged defendants received benefits from company funds or diverted patients and that retention of those benefits would be inequitable under Michigan’s notice-pleading standard.
The court also denied defendants’ motion under Mich. Ct. R. 2.116(C)(10), finding that summary disposition was premature because discovery had not yet begun in the case, notwithstanding that discovery had closed in a related earlier action.
The court granted defendants’ motion for summary disposition only as to plaintiffs’ breach of fiduciary duty claim against Yousif, and denied the motion in all other respects.
Priority Waste, LLC v. Bischer Technologies, LLC[91](Granting summary disposition on account-stated claim). The Macomb County Business Court granted defendant’s/counter-plaintiff’s, GRIT Technologies’ motion for partial summary disposition under Mich. Ct. R. 2.116(C)(10) on its counterclaim for account stated arising from unpaid IT services invoices.
Plaintiff/counter-defendant Priority Waste entered into a Master Services Agreement with GRIT for managed IT services. After alleging GRIT failed to provide adequate support, Priority Waste withheld payment, and GRIT suspended services for nonpayment of invoices. Priority Waste then sued GRIT for conversion, breach of contract, and injunctive relief arising from an alleged breach of a managed IT services agreement. GRIT counterclaimed for breach of contract (collection), breach of contract (poaching), and account stated for unpaid invoices and moved for partial summary disposition on its account-stated claim.
The court granted GRIT’s motion for partial summary disposition. It concluded that GRIT established a prima facie case under Mich. Comp. L. § 600.2145 by attaching to its counterclaim an affidavit and account reflecting the balance owed. Priority Waste failed to file a counter-affidavit denying the account within the statute’s 10-day period and instead submitted an affidavit more than 50 days later. The court rejected Priority Waste’s attempt to cure the untimely filing by seeking leave to amend its answer, explaining that the statute requires the affidavit to be filed within the prescribed period.
The court further found that Priority Waste’s late affidavit contained only conclusory assertions disputing the invoices and alleging that GRIT breached the parties’ agreement. Because an account stated constitutes a new and independent contract based on assent to the balance due, disputes over the underlying service agreement were irrelevant. Having failed to timely or substantively rebut GRIT’s prima facie evidence of the account stated, it determined that Priority Waste could not create a genuine issue of material fact, and summary disposition on GRIT’s counterclaim on account stated was warranted.
Independent Bank v. Adelaide Pointe Boaters Services, LLC.[92](Denying receiver and requiring evidentiary hearing where material factual disputes existed regarding default, collateral value, and risk to lender’s collateral). Plaintiff, Independent Bank, filed suit seeking contract damages, judicial foreclosure of several mortgages, and the appointment of a receiver for a large mixed-use development in Muskegon, Michigan. Defendants were the borrower entities involved in the Adelaide Pointe development, along with affiliated management entities, a guarantor, and the trustee of the guarantor’s asset protection trust. Plaintiff alleged that defendants defaulted on more than $28 million in loans used to finance the project after failing to repay matured promissory notes and failing to pay property taxes and contractors. Relying on cross-default provisions and receivership clauses in the loan documents, plaintiff declared all loans in default and moved ex parte for the immediate appointment of a receiver to preserve and manage the collateral.
Defendants argued that the receivership motion was a bad-faith attempt to circumvent a recently executed forbearance agreement and that no emergency or threat to the bank’s collateral existed. They maintained that any alleged defaults were known or cured and that the bank’s actions had worsened the project’s temporary cash flow issues.
The Kent County Business Court concluded that although the loan documents allowed the lender to seek appointment of a receiver upon default, receivership remains an equitable remedy and the court must independently evaluate whether it is warranted. Applying Michigan law governing receiverships, the court emphasized that the remedy is harsh and generally reserved for extreme circumstances to prevent loss or deterioration of property. Because the parties presented sharply conflicting evidence regarding the existence of uncured defaults, the value and stability of the project, the effect of a recent forbearance agreement, and whether the lender’s collateral was actually at risk, the court concluded that these factual disputes could not be resolved on affidavits alone. The court therefore denied without prejudice plaintiff’s motion to appoint a receiver and determined that an evidentiary hearing would be required before deciding whether receivership was appropriate, leaving all foreclosure and contract claims pending.
§ 3.9. New Hampshire Commercial Dispute Docket
CMG CIT Acquisition, LLC D/B/A CoreMedical Group v. Perron[93](Preliminary injunction based on noncompete agreement). There were no business court decisions in New Hampshire in 2025 that addressed novel issues or broke any new ground. This decision granted a preliminary injunction in a case involving a confidentiality and noncompete agreement, and it covers the ground comprehensively in terms of the elements required to obtain such relief. It is worthy of a citation for no other reason.
Atlantic Anesthesia, P.A. v. Ira Lehrer, et al.[94](Common interest doctrine and crime fraud exception). Five years ago, this business court decision addressed the common interest doctrine and the crime-fraud exception to the attorney-client privilege. As reported then, the decision made the following rulings:
In this case, the court addressed an issue on which the New Hampshire Supreme Court had not yet ruled: whether the “common interest” provision within the attorney client privilege rule of evidence (“in a pending action and concerning a matter of common interest”) applied in the circumstances.
There was no pending action, but the defendants and a third party had communicated regarding the subject of the later litigation, and the defendants sought to protect discovery of their communications with that third party pursuant to the “common interest” rule.
The court ultimately determined that it need not resolve the issue of whether this doctrine can apply to communications before there is a “pending action,” because it further determined that the crime-fraud exception to the privilege applied in the context of an alleged breach of fiduciary duty. In doing so, the court concluded that the New Hampshire Supreme Court would find persuasive the reasoning of decisions from other jurisdictions finding sufficient parallels between fraud and the intentional breach of fiduciary duties to trigger the exception to the privilege rule.
Atlantic Anesthesia, P.A. v. Ira Lehrer, et al.[95](Common interest doctrine and crime fraud exception). The New Hampshire Supreme Court recently reversed the business court decision, ruling that the common interest doctrine did not apply in advance of actually anticipated or pending litigation:
The doctrine is codified in New Hampshire Rule of Evidence 502(b)(3), which provides that the privilege extends to communications “by the client or the client’s representative or the client’s lawyer or a representative of the lawyer to a lawyer or a representative of a lawyer representing another party in a pending action and concerning a matter of common interest therein.” N.H. R. Ev. 502(b)(3). The language of the rule unambiguously provides that it applies when: (1) there was an action pending at the time the communications were made; and (2) the communications pertained to a matter of common interest. Id. at p. 20 (cleaned up).
With respect to the crime-fraud exception to the attorney-client privilege, the Supreme Court determined that this exception was not triggered by allegations of breach of fiduciary duty, but limited specifically to crimes or frauds:
The essence of fraud is a fraudulent misrepresentation. To establish common law fraud under New Hampshire law, a plaintiff must prove that the defendant made a representation with knowledge of its falsity or with conscious indifference to its truth with the intention to cause another to rely upon it. In addition, the plaintiff must prove that it justifiably relied upon the representation, to its detriment. Accordingly, the appropriate inquiry is not, as framed by the trial court, whether there was a reasonable basis for believing that the physician defendants breached their fiduciary duties and that WDH tortiously interfered with Atlantic/NAPA-NH’s contractual relations and that each used the services of attorneys to accomplish the breach and the tortious interference. Rather, the appropriate inquiry is whether there is a reasonable basis to conclude that the physician defendants and WDH intended to use the services of their attorneys to assist them in making a false representation to Atlantic/NAPA-NH upon which they intended Atlantic/NAPA-NH to rely to its detriment. Id. at p. 28 (cleaned up).
§ 3.10. New Jersey’s Complex Business Litigation Program
Jack Jaffa v. Abraham Kraus, et al.[96](Preliminary injunction and appointment of receiver). In this dispute concerning plaintiff’s purported ownership interests in multiple New Jersey healthcare facilities, the New Jersey Superior Court reaffirmed the exacting standards governing injunctive relief in New Jersey. The Court rejected Plaintiff’s request for a preliminary injunction restraining defendants from transferring assets outside the ordinary course of business, as well as his request for appointment of a custodial receiver to oversee the finances of the subject nursing homes.
Plaintiff Jack Jaffa alleged that in 2018, he entered into agreements with non-party Joseph Schwartz concerning the ownership of three New Jersey healthcare facilities, and that Schwartz thereafter entered into management agreements with the defendant entities wherein the defendant entities assumed operational control of the facilities. Plaintiff alleged that defendants continued to direct proceeds to Schwartz-controlled entities, thereby depriving Plaintiff of his alleged contractual ownership interest, and sought a preliminary injunction to preserve his claimed interests. Defendants countered that Plaintiff relinquished his ownership rights by virtue of a 2019 Memorandum of Understanding (“MOU”) and associated termination agreements. Defendants also argued that Plaintiff’s requested preliminary injunction would disrupt the long-standing operational status quo, jeopardize the facilities’ stability and treatment of patients, and serve only Plaintiff’s monetary interests—not any urgent equitable right.
In denying Plaintiff’s motion for preliminary injunction and appointment of a receiver, the court began by emphasizing that “a preliminary injunction is an extraordinary remedy that involves ‘the most sensitive exercise of judicial discretion.”’ The court highlighted that Plaintiff did not bring the action until nearly six years after defendants began managing the facilities, and that defendants had been providing care to New Jersey residents for years while operating the nursing homes profitably and in compliance with contractual and regulatory obligations. The court also stressed that Plaintiff’s feared harm—the loss of monetary receipts—was not a unique real property or possessory interest that rose to the level of irreparable injury justifying extraordinary relief, and that the documentary evidence (notably the 2019 MOU) negated Plaintiff’s claim that he retained a settled ownership or contractual interest in the subject facilities. Thus, the court concluded that Plaintiff failed to establish any of the elements (reasonable probability of ultimate success of the merits, a settled legal right to the ultimate relief sought, that irreparable harm will occur absent injunctive relief, and that the balance of hardships favors Plaintiff) necessary for issuance of a preliminary injunction or any further equitable relief.
§ 3.11. New York Supreme Court Commercial Division
Slice Wireless Services, LLC v. Yakubov[97](Compliance with Commercial Division rules). The procedural rules for the Commercial Division, located at 22 N.Y.C.R.R. § 202.70, are intended to ensure the most efficient, prompt, and fair resolution of complex commercial disputes. Attorneys practicing in New York’s Commercial Division courts ignore those rules at their peril. In this case, Judge Robert R. Reed of the New York County Commercial Division denied plaintiff’s motion to compel discovery because plaintiff failed to comply with New York Commercial Division Rule 14 (22 N.Y.R.R. 202.70) and the court’s individual part rules. The court held that plaintiff’s failure to abide by the rules deprived the court of its ability to supervise disclosure in an orderly manner.
PFNGT LLC v. Liquid Capital LLC[98] (Motion for summary judgment in lieu of complaint granted in part). New York’s Commercial Division courts are attractive venues for clients seeking to resolve their commercial disputes and enforce their contractual agreements quickly and efficiently. Here, the plaintiff lender filed a motion for summary judgment in lieu of complaint, pursuant to CPLR 3213, against the borrower, guarantor and pledgor under a loan agreement and accompanying promissory note. Judge Joel M. Cohen of the New York County Commercial Division granted plaintiff lender’s motion for summary judgment against the borrower and the guarantor, finding that the plaintiff had established that: (1) the borrower had executed the loan agreement and promissory note; (2) the note contained an unconditional promise to repay the plaintiff in accordance with the loan agreement; (3) the guarantor had unconditionally and irrevocably guaranteed payment of the note; and (4) the borrower defaulted. The court rejected defendants’ arguments that the note and guaranty were not instruments for the payment of money only because they contained additional provisions requiring the borrower and guarantor to provide certain financial disclosures and comply with all laws. The court concluded, “[t]hese ancillary clauses do not affect or limit Guarantor’s or Borrower’s unconditional obligation to make payment.” Although the court denied plaintiff’s motion against the pledgor, holding that the right to enforce the security interest was independent from the obligation to pay on the note, the court held that if payment on the note and guaranty is not forthcoming, plaintiff may move separately against the collateral. Thus, the plaintiff was able to obtain a court order enforcing its contractual agreement within a matter of months of its initial filing.
DOIT Hospitality Delaware LLC v. Reuben Bros. Ltd.[99] (Absent parties’ consent, good cause required to permit remote deposition). Particularly after the COVID pandemic, parties and their counsel may wrongly assume that they can unilaterally take depositions or produce witnesses for depositions virtually. Absent parties’ consent, New York’s Commercial Division courts require a showing of good cause to take a deposition remotely. In this case, one of the plaintiffs resided in India. Defendant insisted that the plaintiff be produced in-person in New York. Plaintiffs argued that a virtual deposition should be allowed because the Indian witness would not be able to obtain an appointment for a visa interview, let alone get a visa, in time to travel to New York for his deposition. Commercial Division Judge Robert R. Reed of the New York County Commercial Division noted that the Commercial Division Rules permit the court to order a remote deposition upon consent of the parties or upon a motion showing good cause but concluded that extensive wait time for a visa appointment or interview did not constitute good cause to permit a remote deposition. The court found good cause particularly lacking where the plaintiff failed to make any showing that it had taken any steps needed to assist in obtaining the travel visa for a key witness in a case it commenced three years before the motion was decided. The court ordered the plaintiff to produce the witness for an in-person deposition in New York within 180 days and further ordered that if the plaintiff failed to do so, the complaint would be stricken for non-compliance.
Ader v. Ader[100] (Awarding of sanctions for filings containing artificial intelligence hallucinations). Judges in New York, as elsewhere, have significant discretion to impose sanctions, including in cases involving court filings containing artificial intelligence hallucinations. In Ader, defense counsel included an AI-hallucinated citation and quotation in opposition to plaintiff’s summary judgment brief, and then included multiple new-AI-hallucinated citations and quotations in defendant’s brief opposing plaintiff’s motion for sanctions, including four citations that did not exist, seven quotations that did not exist in cited cases, and three citations that did not support the propositions for which they were offered. In granting plaintiff’s motion for sanctions, Judge Joel M. Cohen of the New York County Commercial Division noted that to fail to impose sanctions just because the legal propositions were accurate would “create [] the risk that a fake citation may make its way into a judicial decision, forcing courts to expend their limited time and resource to avoid such a result.” Judge Cohen ordered defendants and their counsel, jointly and severally, to pay attorney’s fees, costs, and out-of-pocket expenses incurred in connection with the motion for sanctions, as well as fees attributable to addressing defendant’s unvetted AI citations and quotations in the summary judgment motion. In addition, the court ordered that its opinion be provided to the Grievance Committee for the Appellate Division, First Department, and the Office of Attorney Ethics in New Jersey, where defense counsel was also admitted. As Judge Cohen noted, counsel have a responsibility to ensure that their representations to the court are accurate.
Linkable Networks, Inc. v. Mastercard Inc.[101] (Standard for motion to seal records). This case addressed the standard for sealing or redacting court records on a showing of “good cause.” Judge Robert R. Reed of the Commercial Division, New York County noted that Section 216.1(a) of the Uniform Rules for Trial Courts permits courts to seal documents only upon a written finding of good cause. The court noted that “[i]n the business context, courts permit records to be sealed when trade secrets are involved or when disclosure of information contained in documents ‘could threaten a business’s competitive advantage’” but also noted that under New York law, there is a “clear presumption that the public is entitled to access to judicial proceedings and court records.” The court found that, where most if not all of the documents sought to be sealed were used as trial exhibits, the parties had failed to overcome the “broad presumption of public entitlement” to court records.
§ 3.12. North Carolina Business Court
Shively v. ACI Learning Holdings, LLC[102](Personal jurisdiction). This case arose out of the termination of Plaintiff Shively’s employment with ACI Learning Holdings (“ACI”) and Shively’s execution of and attempt to enforce the provisions of a severance agreement (the “Agreement”). Shively alleged that ACI and affiliates failed to purchase Shively’s equity interests in ACI pursuant to the Agreement. The defendants moved to dismiss the action for lack of personal jurisdiction, contending that they lacked minimum contracts with North Carolina such that the Court’s exercise of personal jurisdiction would offend due process.
The ACI defendants are Delaware entities with their principal places of business in Colorado and Shively is a North Carolina resident. The parties’ contractual relationship was a critical factor in the Court’s analysis regarding whether ACI purposefully availed itself of the State. ACI offered a severance agreement to a known North Carolina resident, such severance agreement was accepted in North Carolina, and such North Carolina resident performed required consulting services in North Carolina. Although some factors weighed against the exercise of personal jurisdiction, and notwithstanding the Agreement’s Delaware choice of law provision, the Court concluded that defendants had sufficient minimum contacts with this State to support personal jurisdiction. This opinion has since been cited by two other Business Court judges for the proposition that personal jurisdiction will be extended where the defendant willingly instigated and entered into an agreement with a North Carolina individual (or entity) when the defendant knew the agreement would be performed within North Carolina.[103]
rFactr, Inc. v. McDowell[104](Defamation claims at summary judgment). This case concerns a dispute among rFactr, Inc., a technology company (“rFactr”), rFactr executives Richard Brasser (“Richard”) and Greg Gentner (“Greg”), and former investor Chris McDowell (“Chris”). rFactr, Richard, and Greg sued Chris and his wife Caroline McDowell (“Caroline” and collectively, the “McDowells”) for defamation, alleging that Caroline told a potential client of rFactr that Richard and Greg were under criminal investigation. During a stay in the litigation due to criminal charges against Richard and Greg, Richard and his wife Megan Brasser (“Megan,” and collectively, the “Brassers”) created online fundraisers, videos, and social media posts. Megan posted numerous videos alleging that the McDowells were plotting to bring about personal, financial, and physical harm to the Brassers. The McDowells filed counterclaims against the Brassers for defamation per se and subsequently moved for summary judgment on the same.
At summary judgment, the Court emphasized that for statements to be defamatory per se, such statements must be slanderous or libelous on their face, when stripped of all insinuations. A statement cannot be defamatory by implication. And, to recover for defamation, the allegedly false statements must be “of or concerning the plaintiff.” The Court considered each online post separately, rather than the aggregate effect of all posts taken together. In doing so, the Court emphasized that for defamatory words to be actionable, they must refer to some ascertained or ascertainable person, and such person must be the defamed plaintiff. If the words used contain no reflection on any ascertainable individual, no averment can make them defamatory.
Regarding one social media post, the Court held that such post, at best, revealed that the subject lived in “Richmond” and had some connection to Richard. From the perspective of an ordinary person, this information alone did not contain a reflection of any particular individual. A different post concerned a “Chris,” who was with his partner “up in Richmond,” an otherwise undescribed location. The Court determined that it could not, as a matter of law, determine that an ordinary reader would identify the McDowells in the context of the post, particularly because the name “Chris” is a fairly common name. Ultimately, the information provided in the Brassers’ videos and posts were descriptors, but the Court held that they did not include information sufficient to determine that the statements were “of or concerning” the McDowells. The Court therefore denied the motion for summary judgment with respect to all of the alleged defamatory statements.
State of N.C. v. E.I. Du Pont de Nemours & Co.[105](Subject matter jurisdiction and common law authority of the Attorney General). This case concerns the State of North Carolina’s (the “State”) allegation that defendants contaminated North Carolina’s land, air, and water with polyfluoroalkyl substances (PFAS). At issue in this decision is the defendants’ motion to dismiss for lack of subject-matter jurisdiction, predicated on the North Carolina General Assembly’s repeal of N.C.G.S. § 114-2(8)(a) in December 2024, several years after this case was filed.
The Court first determined that, prior to the repeal of N.C.G.S. § 114-2(8)(a), the statute conferred upon the Attorney General (“AG”) the authority to originate and maintain the action. In light of the repeal, the Court considered whether the AG has the common law authority to maintain the action. Based on the Court’s decision, which cited back to English common law, it appears well settled in the eyes of the Court that the AG has the power to prosecute all actions necessary for the protection and defense of the property and revenue of the people of North Carolina. North Carolina has a quasi-sovereign interest in its natural resources, which is a form of property interest. The Court determined that, under the common law, the AG had and continues to have the power to originate and maintain suits for the protection and defense of North Carolina’s natural resources. As a result, the repeal of § 114-2(8)(a) did not strip the AG of the authority to initiate the action, as the AG has common law authority to originate and maintain environmental actions such as this one.
Wilmington Trust, Nat. Ass’n v. TM Northlake Mall, L.P.[106](Receivership sale and objections).In this case, the appointed receiver, Spinoso Real Estate Group, DLS, LLC moved for approval to sell a shopping mall pursuant to N.C. Gen. Stat. § 1-507.46. Spinoso took over management of the Northlake Mall in Charlotte in 2021, restoring tenancy at the mall and positioning it for sale. Spinoso eventually entered into a purchase agreement to sell the mall for $39 million, $5 million due upfront, no due diligence period, and closing to be completed within 10 days of court approval of the sale. Two parties objected to the sale: Ryan Investment Group, LLC, who claimed Spinoso failed to advertise the sale adequately and undervalued the property, and the Estate of Amari Spencer, who also claimed Spinoso undervalued the property, meaning there would not be sufficient assets to compensate them if they succeed in their pending premises liability lawsuit arising out of a shooting at the mall in 2022.
Because the North Carolina receivership statute is silent as to the standard courts should apply when deciding whether to approve a proposed sale of receivership property, and there was no applicable North Carolina case law on the subject, the court looked to federal bankruptcy law for guidance, using the “business judgment test” used by bankruptcy courts. This test assesses only whether the trustee’s judgment was reasonable and whether a sound business justification exists supporting the sale and its terms. The court found that the proposed sale was reasonable and justified. The court noted that Spinoso had worked with a marketing company and provided notice to 11,000 interested purchasers. Likewise, the court found the sale price to be reasonable, given the current declining demand and sale prices for shopping malls. Both the primary secured creditor and the debtor also endorsed the sale, believing the price to be fair. Finally, the court concluded that because the Estate’s claims for damages in its lawsuit were over ten times the sale price, there was little realistic chance that any sale would occur that would be able to satisfy all the secured and unsecured creditors. Therefore, there was no basis to stop the sale.
JT Russell & Sons, Inc. v. Russell[107](Survival of derivative claims after inquiry by court-appointed panel, claim for removal of directors, and motion to strike).The Court addressed intra-family shareholder disputes within a closely held corporation and clarified the role of a court-appointed special litigation panel (“SLP”) under N.C.G.S. § 55-7-44. After a shareholder asserted derivative counterclaims alleging fiduciary breaches and misuse of corporate assets, the corporation invoked an SLP process. The Court held that where an independent panel conducts a reasonable, good-faith inquiry and determines that pursuing derivative claims is not in the corporation’s best interest, dismissal is mandatory. Applying that framework, the Court found the panel’s investigation—supported by document review, witness interviews, and independent counsel—was sufficiently thorough and its conclusions well-founded, and therefore dismissed the derivative claims with prejudice.
The Court, however, drew a sharp distinction between derivative claims and direct claims. It denied the motion to dismiss the shareholder’s claim for judicial removal of directors under N.C.G.S. § 55-8-09, emphasizing that such claims are evaluated solely on the pleadings at the Rule 12(b)(6) stage. Allegations that directors unlawfully amended bylaws, seized control of the board, and engaged in self-dealing were sufficient to state a claim for this “extraordinary remedy,” even if those allegations overlapped with issues considered by the SLP. Notably, the court refused to consider the panel’s report in assessing the direct claim, underscoring the procedural divide between SLP-based dismissal and traditional pleading standards.
Finally, the Court denied the corporation’s motion to strike large portions of the pleading, reiterating the disfavored nature of Rule 12(f) motions and the broad relevance standard. The decision highlights both the strength of the SLP mechanism in terminating derivative litigation and its limits: while an SLP can effectively foreclose derivative claims, it does not insulate directors from direct claims based on alleged misconduct or corporate governance violations.
Hart v. First Oak Wealth Mgmt., LLC[108](Securities law; statute of limitations; fraud; constructive fraud; conspiracy). Between 2009 and 2014, Plaintiff Stephen Hart, an accredited investor under Regulation D of the Securities Act of 1933, invested in several private offerings through DMW Advisors, LLC, working with Defendants Joseph Davis III and Airis Abolins. In several of these transactions Davis was either on the board of directors or in management of the companies in which DMW was investing Hart’s money. By 2014, Hart informed Davis and Abolins that he wanted to pursue a more conservative investment strategy and did not want to invest in private offerings any longer. By 2017, multiple lawsuits had begun to be filed against Davis and DMW, alleging fraud arising out of their investments. Davis also became the target of multiple investigations by regulators. That year, Abolins formed First Oak Wealth Management, LLC with another advisor. First Oak purchased DMW’s public accounts but left all private holdings, including Hart’s, with DMW. Davis informed Hart via email that First Oak had purchased DMW’s accounts and that Hart’s account would transfer to First Oak unless he affirmatively opted out. However, Davis did not clarify that First Oak would not be transferring any private investments. In April 2018, after Hart inquired with Abolins about his private investments, Abolins informed Hart that they had not been transferred to First Oak. Ultimately, Hart did not confirm the whereabouts of his private accounts until he spoke with Davis in January 2019. Meanwhile, First Oak itself came under federal and state investigation for its association and representations to clients regarding its relationship with Davis.
Hart filed suit in October 2021 against First Oak, Davis, and Abolins, alleging common law fraud, constructive fraud, negligent misrepresentation, violations of the North Carolina Investment Advisers Act, and civil conspiracy. Hart claimed that the defendants’ private investments were contrary to his express desire for a more conservative investment strategy. The defendants moved for summary judgment on statute of limitations grounds. The Court granted the defendants’ motions with respect to the fraud, negligent misrepresentations, and Investment Advisers Act claims. The Court concluded that “obvious red flags” had appeared even before First Oak was formed, causing the limitations period to begin running well before 2017. The Court explained that Hart failed to take any further action despite: Davis’s obvious conflicts of interest; several of Hart’s investments being risky and worthless; multiple public lawsuits and investigations into Davis; and Hart learning no later than April 2018 that his private investments were not with First Oak. Thus, Hart’s claims were barred by the applicable 3-year statute of limitations.
However, the Court denied summary judgment with respect to the constructive fraud claim, which in North Carolina has a 10-year limitations period. With constructive fraud, a plaintiff is entitled to rely on the fiduciary’s duty to disclose the truth when deciding whether to conduct his own inquiry. The Court concluded that the defendants were fiduciaries and that a jury could find that the defendants had deterred Hart from suspecting or investigating the alleged fraudulent conduct at issue. Thus, the date the statute of limitations began to run was a question for the jury. The Court also concluded that a jury could find that the defendants worked together to keep Hart from learning the truth about his investments. Thus, the civil conspiracy claim survived as well.
CRH Eastern, LLC v. Berastain[109](Rule 12(b)(6) motion to dismiss claims arising from employee departures and competition).This case arose from the plaintiff’s allegations that former executives and employees formed a competing company after leaving the plaintiff, deleted information from the plaintiff’s project-management platform, and used the plaintiff’s confidential information to compete. Certain defendants moved to dismiss under Rule 12(b)(6).
The Court allowed a tortious interference claim against the competing company to proceed based on allegations that it knowingly induced the former executives to violate restrictive covenants, but dismissed tortious interference claims based on customer, vendor, and subcontractor relationships because the complaint failed to identify specific contracts or business opportunities lost as a result of the alleged conduct. The Court held that allegations concerning customer lists and subcontractor/vendor lists, together with detailed information associated with those relationships, identified the plaintiff’s alleged trade secrets with sufficient particularity. The Court, however, dismissed the plaintiff’s trade secret misappropriation claim to the extent that it was based on a generalized category of “business operation information,” concluding that those allegations were too vague to identify a trade secret. The Court further held that allegations that a former employee had access to the plaintiff’s trade secrets and used them while working for the competing company were sufficient to support trade secret misappropriation claims against the competing company, the former employee, and the entity that later acquired the competing company.
The Court denied dismissal of a claim under North Carolina’s computer trespass statute based on allegations that the former employees had deleted jobs from the project-management platform, copied company data, and returned company-issued laptops that had been damaged, encrypted, or wiped. The Court further reasoned that the statute did not foreclose the possibility of vicarious liability because the competing company allegedly profited from the computer trespass.
Tanger Props. Ltd. P’ship v. Ace American Ins. Co.[110](Choice of law regarding interpretation of insurance contract and UDTPA). The Court denied insurers’ motion to dismiss in a COVID-19 business interruption coverage dispute, allowing all claims to proceed past the pleading stage. The case centers on whether “all-risk” commercial property policies cover pandemic-related losses suffered by Tanger Properties, a North Carolina–based operator of outlet centers nationwide. A key issue was choice of law: although the insurers argued that another state’s law should apply under lex loci contractus, the Court held that N.C.G.S. § 58-3-1 required application of North Carolina law due to a “close connection” between the state and the insured interests, emphasizing Tanger’s headquarters in North Carolina, in-state operations, and the insurers’ awareness of those ties.
Applying North Carolina law—significant because North Carolina is uniquely favorable to insureds on pandemic coverage—the Court declined to dismiss the breach of contract and declaratory judgment claims. It also allowed the plaintiff’s UDTPA claim to proceed, rejecting the insurers’ argument that post-litigation conduct (i.e., failure to reconsider denial after the North Carolina Supreme Court’s decision in North State Deli) cannot form the basis of unfair claims practices. The Court noted the absence of controlling North Carolina authority on this issue and found it sufficient at the Rule 12(b)(6) stage that the plaintiff plausibly alleged statutory violations based on the insurers’ refusal to reevaluate coverage in light of intervening law.
Finally, the Court denied dismissal of the claim for breach of the implied covenant of good faith and fair dealing, addressing a nuanced limitations issue. Construing policy language in favor of the insured, the Court held that Florida’s longer statute of limitations potentially applied via a contractual provision, and that factual development was necessary to determine accrual. More broadly, the opinion underscores the continued viability of COVID-19 business interruption claims in North Carolina, particularly where choice-of-law principles permit application of its comparatively policyholder-friendly jurisprudence.
WP Church, LLC v. Whalen[111](Disqualifying counsel from jointly representing LLC and its sole manager in derivative action alleging self-dealing and misappropriation against sole manager). This order determined that a law firm may not simultaneously represent both an LLC and its sole manager in a derivative action alleging self-dealing and misappropriation of company funds against the manager. The complaint asserted that the manager diverted millions in company assets to affiliated businesses and personal expenses, creating a direct conflict between the company’s interests and the manager’s defense. The Court also relied on its prior preliminary injunction findings indicating a likelihood of conflicted transactions involving company assets and affiliated entities.
Applying Rules 1.7 and 1.13 of the North Carolina Rules of Professional Conduct, the Court concluded that dual representation is impermissible where derivative claims allege serious wrongdoing such as self-dealing and diversion of corporate assets. The Court rejected arguments premised on client consent and absence of direct adverse claims, finding no adequate evidence of informed waiver and noting that purportedly consenting parties were not sufficiently disinterested. The Court therefore disqualified the law firm from representing the company, struck filings made on its behalf, and permitted continued representation only of the manager.
Moore v. Brooks[112](Personal jurisdiction; legal services).In this case, the North Carolina Business Court examined personal jurisdiction in the context of an out-of-state attorney providing legal services to North Carolina residents. Scott Robinson, a resident and practicing attorney in Wyoming, performed legal services for Drue Moore, a North Carolina resident, from approximately 2009 to 2025, helping Moore set up several Wyoming LLCs, including Winthrop Intelligence, LLC. Robinson later became the manager and attorney of Winthrop, a position he held until January 2025. Robinson also drafted several trust documents for Moore and his family, received and forwarded property tax notices to Moore for his North Carolina residence, and received checks from Moore to pay several life insurance premiums. Robinson, however, never traveled to North Carolina. Robinson and Moore’s relationship deteriorated suddenly in 2024, after Robinson and Winthrop’s CFO, Robert Brooks, came to believe that Moore had been taking unauthorized distributions from Winthrop for several years, amounting to millions of dollars. Robinson and Brooks met with Moore in Arizona to discuss the matter and formulate a repayment plan for Moore. Robinson also gave Brooks broad authority to negotiate a return of the money to Winthrop with Moore. Brooks regularly communicated with Moore regarding these repayments, expressing his displeasure that Moore was not cooperating with the repayment plan. When negotiations failed, Robinson attempted (unsuccessfully) to transfer property from the various trusts to Winthrop. Eventually, after receiving an ultimatum from Brooks to transfer the property, Moore took his own life. Afterward, Robinson contacted his widow, Kelly Moore, telling her that her late husband had embezzled millions of dollars from Winthrop and had not cooperated with returning the money.
On March 7, 2025, Kelly Moore, on behalf of herself and Moore’s Estate, filed an amended complaint against Robinson, his law firm, and others, seeking, among other things, a declaratory judgment and damages for intentional infliction of emotional distress, conversion, unjust enrichment, and breach of fiduciary duty. Robinson and his firm moved for dismissal for lack of personal jurisdiction. The Court agreed that personal jurisdiction was lacking. The Court rejected a bright-line rule that an attorney-client relationship with a North Carolina resident subjects an out-of-state attorney to the jurisdiction of the North Carolina courts. Rather, the nature of the attorney-client relationship must be examined individually. Here, the Court focused on the fact that Robinson did not market his services towards North Carolina or solicit Moore. Instead, Moore had reached out to Robinson in Wyoming to set up the Wyoming LLCs and avail himself of Wyoming’s law. Additionally, any harm suffered by the North Carolina beneficiaries of the Moore trusts when Robinson attempted to transfer property out them was too attenuated to create sufficient minimum contacts. The Court also concluded that performing routine legal services, such as transmitting property tax and insurance bills to Moore for payment and filing annual reports with the North Carolina Secretary of State, did not rise to the level of purposeful availment of the forum for Robinson or his law firm, nor did Robinson’s single email to Kelly Moore after Moore’s death. Finally, the Court rejected the plaintiffs’ attempt to establish an agency relationship between Brooks and Robinson. Although Robinson had authorized Brooks to have wide latitude in negotiating with Moore, that authorization was on behalf of Winthrop and did not create an agency relationship between Brooks and Robinson individually. Ultimately, the plaintiffs failed to make a prima facie showing that jurisdiction existed with respect to Robinson, and their claims against him and his firm were dismissed.
Oak Grove Technologies, LLC v. Seventh Dimension, LLC[113](Rule 12(b)(6) motion to dismiss counterclaims and third-party claims arising from government subcontract dispute).The Court applied North Carolina’s notice-pleading standard to contract, tort, and statutory counterclaims and third-party claims arising from a government subcontracting dispute. It allowed certain breach of contract claims to proceed where the pleading identified specific contractual obligations and alleged concrete failures tied to those duties. The Court dismissed other breach theories that were pleaded in general terms without factual detail. It also allowed a limited declaratory judgment claim to proceed where there was a live dispute over whether a government-directed pricing reduction required a corresponding adjustment to subcontract rates, while dismissing requested duplicative declaratory relief tied to a separate contract interpretation theory that was already resolved through dismissal of the related breach claim.
The Court dismissed the fraud, fraudulent inducement, and negligent misrepresentation claims in full, reasoning that the counterclaimants failed to plead reasonable reliance or actionable misrepresentations in an arm’s-length relationship between sophisticated contracting parties. It held that statements about cooperation, partnership, or future performance were not actionable absent factual allegations showing that they were false when made or made with a present intent not to perform. The Court also dismissed most of the unfair and deceptive trade practices claim because it depended on dismissed tort theories and lacked independent factual support, allowing it to proceed only to the extent that it was based on separately pleaded defamation allegations against one third-party defendant.
§ 3.13. Rhode Island Superior Court Business Calendar
Soares v. Anon Prods.[114] (Successor liability). The plaintiffs, Brian and Susan Soares, asserted claims of liability for mesothelioma allegedly caused by asbestos-containing talc products, including Johnson & Johnson’s baby powder. They alleged that Susan’s use of these products over decades led to her diagnosis of malignant pleural mesothelioma in 2023. The defendants, subsidiaries of Johnson & Johnson, sought dismissal of the claims, arguing that Texas law, which limits successor liability, should apply due to the corporate restructuring under Texas law. However, the Rhode Island Superior Court denied the motion to dismiss, finding that Rhode Island law, which provides broader exceptions to the general rule against successor liability, should apply.
Under Rhode Island law, exceptions to the general rule against successor liability include the “mere continuation” and “de facto merger” theories. These theories allow for liability to transfer to a successor corporation if certain factors are met, such as continuity of management, shareholders, and business operations, or if the predecessor corporation ceases operations and the successor assumes its obligations. The court noted that Rhode Island’s interest in providing remedies for injuries and wrongs, as enshrined in its constitution, outweighed Texas’s interest in this case. Additionally, the court found that the plaintiffs had adequately alleged fraudulent transfers of assets among Johnson & Johnson subsidiaries to hinder or delay talc-related litigation, which could also establish successor liability under both Rhode Island and Texas law.
The court emphasized that even if Texas law were applied, the plaintiffs’ claims would not necessarily fail, as Texas law also recognizes an exception for fraudulent transfers intended to escape liability. The court concluded that the plaintiffs had sufficiently pled facts to support their claims under Rhode Island law, and the motion to dismiss was denied as to the remaining defendants.
Karten v. Proclamation Ales, LLC.[115](Membership interest agreement, breach of fiduciary duty). Karten and Witham formed Proclamation Ales LLC in 2013. In 2016 they executed a Membership Interest Agreement and Operating Agreement. In 2020, Witham terminated Karten as manager because Karten had engaged in improper financial management, including an undocumented loan scheme. A new Operating Agreement was executed in November of 2020 without Karten’s involvement. Witham passed away in December of 2020.
The Plaintiff, Karten, filed an Amended Verified Complaint against Proclamation Ales and Ms. Witham, the Executrix of the Estate of David Witham following a business dispute between Karten and Mr. Witham during their joint management of Proclamation Ales for breach of fiduciary duty, breach of contract, affirmative injunctive relief, declaratory relief, specific performance, breach of membership interest agreement, and breach of operating agreement. The claim against the Estate was for breach of the membership interest agreement and breach of the operating agreement.
The court held that the 2016 Membership Interest Agreement remained valid and binding on the parties because no written modification was signed by all parties as required. Additionally, the court held that the 2020 Operating Agreement was valid and enforceable because it was properly ratified by majority vote after Mr. Witham granted power of attorney. However, the court also decided that Witham breached his fiduciary duty to Mr. Karten by terminating him without legitimate business purpose, and Karten breached his fiduciary duty to Proclamation Ales through improper financial management and comingling of funds which put Proclamation Ales at risk. Furthermore, the court found that Karten committed an event of dissociation in June of 2017 by failing to perform his managerial duties in good faith. Therefore, the court determined that Karten’s membership interest was converted to non-member economic units as of January 2020 and that Proclamation must redeem Karten’s non-member economic units and Witham’s 68.5% membership interest. The court scheduled a further hearing to determine the valuation of membership interests for redemption.
State of R.I. v. AECOM Tech. Servs.[116](Breach of contract, breach of fiduciary duty). The State of Rhode Island brought claims against AECOM Technical Services, Inc. and other defendants related to the emergency closure of the Washington Bridge on December 11, 2023. The State alleged breach of contract, negligence, breach of fiduciary duty, and sought indemnity and declaratory relief. The closure was necessitated by structural failures, including tie-down rod failures and widespread deterioration of the post-tensioning system, which rendered the bridge irreparable and required its demolition and replacement.
Regarding the breach of contract claims, the State alleged that AECOM and other defendants failed to adequately perform inspections and design services under various contracts, including a 2014 contract with AECOM. The Court found that the State sufficiently alleged that AECOM’s inadequate performance may have contributed to the bridge’s deterioration and emergency closure. At the motion to dismiss stage, the Court determined that the State’s claims were plausible, even though the State did not identify a specific contractual provision breached by AECOM. The allegations provided sufficient notice of the breach of contract claims to survive dismissal.
On the breach of fiduciary duty claim, the State argued that AECOM assumed fiduciary duties by holding itself out as a trusted expert in engineering and by the State’s reliance on AECOM’s expertise. The Court found that the State sufficiently alleged a relationship of trust and confidence, which could conceivably create a fiduciary duty. This claim also survived the motion to dismiss.
The State’s indemnity claim, however, was deemed not ripe for judicial review. The indemnity provision in question applied only to third-party claims, and the State failed to allege any actual or imminent third-party liability. The Court noted that under Rhode Island law, an indemnity claim does not arise until the indemnitee’s liability is fixed by judgment or settlement, which had not occurred in this case.
Ponte v. Independence Bank[117](Liability/damages limitation clause). Plaintiffs GBC and Ponte entered agreements with Independence Bank (IB) to act as loan originators for IB’s SBA Loan Program from 2015-2019. IB allegedly concealed from plaintiffs that it was being cited by regulators for noncompliance with SBA and FDIC regulations. Plaintiffs alleged IB and individual defendants made misrepresentations about the program’s compliance status. Plaintiffs learned in 2022 that they were targets of an FDIC investigation related to the SBA Loan Program.
The court held that the liability/damages limitation clause in the contract between the parties could be unenforceable due to public policy concerns, given the allegations of fraud and concealment. The individual defendants RAC, RSC, and Marshall may be personally liable for actions beyond the scope of their employment, but Faris, Bain, and Andrew were dismissed from personal liability claims. The claims for breach of contract, fraud, misrepresentation, and civil conspiracy were sufficiently pled to survive the motion to dismiss. However, the claims for tortious interference with contract, tortious interference with prospective business advantage, negligence, and RICO violations were dismissed for failure to state a claim.
The court granted in part and denied in part the defendants’ motions to dismiss. Counts I, II, III, and VI survive. Counts IV, V, VII, and VIII were dismissed. The individual defendants Bain, Faris, and Andrew were dismissed from personal liability claims.
§ 3.14. Texas Business Court
Applying the Business Court’s Amount in Controversy Jurisdictional Requirement.
In the first Business Court opinion of 2025, C Ten 31 v. Tarbox,[118] (C Ten) rendered January 3, 2025, Judge Andrews of the Third Division clarified a number of important issues of first impression relative to how parties are to establish, or successfully contest, the court’s jurisdiction at the commencement of a case based upon satisfaction of the requisite “amount in controversy” and related procedural matters.[119] Key holdings include:
The Business Court statute’s references to the “amount in controversy” in Texas Gov’t Code Section 25A.004 are requirements for the court’s jurisdiction to the same extent as are the statute’s descriptions of specific causes of action.[120]
The amount in controversy requirement applies at the level of the “action” being litigated, including all “claims” that are before the court, not as a per-claim minimum.
The removal provisions of the Business Court’s authorizing statute, Texas Gov’t Code Secs. 25A.004(f),(g) and .006, anticipate that removal of an action from a district court to the Business Court will remove the entire action to the Business Court, including individual claims included in the action over which the Business Court does not have subject matter jurisdiction.[121] Those claims will at some future point early in the case have to be dismissed by the Business Court, severed into a separate case remanded or transferred to a district court, or made subject to the Business Court’s jurisdiction as supplemental claims by agreement of the parties and the Business Court judge. Until that resolution occurs the Business Court has authority to take over management of the entire lawsuit, including hearing procedural matters scheduled by the district court where the case originated.[122]
The Business Court’s jurisdiction in injunctive and other equitable actions, set forth in Texas Gov’t Code Sec. 25A.004(e)[123], which does not itself reference any amount in controversy, by relying upon references to Texas Gov’t Code Sec. 25A.004(b) and (d), incorporates their amount in controversy jurisdictional requirements, and, in the case of Texas Gov’t Code Sec. 25A.004(c), incorporates its exemption of publicly traded companies from the amount in controversy requirement of Texas Gov’t Code Sec. 25A.004(b).
The court relies upon a considerable body of Texas court decisions addressing the application of statutory amount in controversy requirements to confirm, in the case of the injunctive and equitable actions described above, that the applicable amount in controversy requirement is met by the value of the rights being litigated.[124] This same principle is applied to the construction of the defendant’s assertions in the notice of removal, which is treated as part and parcel with the parties’ pleadings in petitions and answers. The court further held that the removing defendant had no obligation to file jurisdictional evidence with the notice of removal and could rely upon subsequent filings and evidence presented at a hearing before the court if the notice of removal is contested.[125]
A party contesting the Business Court’s jurisdiction (in this case the plaintiff in a district court case removed to the Business Court by the defendant, who pled in the notice of removal that the amount in controversy exceeded the Business Court’s amount in controversy requirement, without specifying an amount) bears the initial burden of showing that the amount pled by the removing defendant (or implied by the general assertion of adequacy in the defendant’s notice of removal) is fraudulent or that a different amount less than the jurisdictionally required amount (here $5 million) can be readily established. If the plaintiff provides such evidence, the burden shifts to the removing defendant to raise a fact issue (i.e., providing more than a scintilla of evidence) regarding the amount in controversy, relying on the same framework that governs pleas to the jurisdiction in Texas courts.
The opinion relies upon the Texas policy of construing pleadings liberally in favor of jurisdiction, and contrasts the approach to this issue by federal courts. The opinion notes that the Texas Supreme Court has consistently declined to require a party to marshal its evidence or prove its claims in order to survive early jurisdictional challenges of this nature. In contrast, federal courts require parties facing a jurisdictional challenge at the outset of a case to meet the same evidentiary burden they would have to satisfy at trial—proof by a preponderance of evidence of the amount in controversy. This distinction reflects that moving a case between the Business Court and a Texas district court is in effect an administrative determination of where a case would most efficiently be heard within a single court system, compared to the complete loss of authority that will occur if a federal court loses its diversity jurisdiction.
The C Ten decision was cited and relied upon by a number of other Business Court judges during the course of 2025.[126] Under Texas law, the decisions of a Business Court judge, like the decisions of other Texas trial court judges, do not create any precedent binding upon that or any other judge in any other proceeding. The Business Court judges are known to confer regularly regarding legal and procedural questions they are addressing and have to date taken consistent positions on issues before their courts.[127] This reflects the Texas Legislature’s intent that the court develop a consistent and predictable body of procedural and substantive jurisprudence to support the efficient execution of business and resolution of business disputes across the state.
Determining the “Consideration” and “Amount in Controversy” Applicable to Business Court Jurisdiction in Litigation Arising Out of a Qualified Transaction.
In Atlas IDF, LP v. Nexpoint Real Estate Partners LLC,[128] Judge Whitehill of the First Division addressed a number of fine points of law necessary to the interpretation of the Business Court’s jurisdiction to hear a dispute arising out of a series of issuances, purchases and sales of due-on-demand promissory notes asserted by the plaintiff, and denied by a defendant seeking to defeat Business Court jurisdiction, to constitute a “qualified transaction”[129] subject to the Business Court’s jurisdiction provided by Sec. 25A.004(d), Texas Gov’t Code: “The business court has civil jurisdiction concurrent with district courts in the following actions in which the amount in controversy exceeds $5 million, excluding interest, statutory damages, exemplary damages, penalties, attorney’s fees, and court costs (emphasis added): (1) an action arising out of a qualified transaction; . . . .” The court’s holdings include:
Based on the language of the “qualified transaction” definition, whether the qualified transaction definition is satisfied is to be determined based on the value of the consideration exchanged, or contemplated by the parties’ agreement to be exchanged, as of the time when the transaction occurred.
The “amount in controversy,” on the other hand, is to be determined based on the facts existing when the suit is filed, and includes both direct claims and counterclaims.
The opinion acknowledges that the principal amount of the demand notes as of the dates of the applicable transactions was below the statutory amount in controversy requirement, and the expected amount of future accrued interest at the time of issuance of the notes was unknown and unknowable. However, the plaintiff had pled that the value it was suing for was in excess of the Business Court’s minimum jurisdictional amount. The court’s analysis of the pleadings supported that the amount in controversy might exceed the applicable statutory minimum. Based on the above, the court accepted that (i) the parties could have reasonably placed a value on the notes in excess of their face amount at the time of the transaction sufficient to satisfy the definitional requirement for a “qualified transaction” and (ii) the amount being sued for by the plaintiff could reasonably be expected to exceed the applicable amount in controversy requirement.
The defendant having provided no contrary evidence to support a lower consideration value for the promissory notes, the plaintiff’s allegations were accepted as adequate to support the existence of a “qualified transaction.”
The defendant asserted that Sec. 25A.004(d)’s exclusion of “interest” in the list of claims that are not to be considered in establishing the amount in controversy—“excluding interest, statutory damages, exemplary damages, penalties, attorney’s fees, and court costs . . . .” (emphasis added) did not mean that the plaintiff could not include a negotiated amount of contractually accrued interest on the promissory notes being sued upon. Judge Whitehill interpreted the reference to interest to mean, like the other items in the list, non-negotiable statutory amounts that might be collectable as a matter of law.
The 30-Day Period to Remove an Action to Business Court Does Not Commence Until Claims are Filed Against the Removing Party.
In SafeLease Insurance Services LLC, v. Storeable, Inc.[130] Judge Andrews of the Third Business Court Division confirmed that the 30-day period allowed for removal of an action to the Business Court by Texas Gov’t Code Sec. 25A.006(f)(1)[131] does not begin running until the action has been filed, rejecting the defendant’s assertion that the 30-day deadline begins running when a party has knowledge of facts that support claims that fall within the Business Court’s jurisdiction. The opinion notes conundrums that would result from the defendant’s position, such as the possibility that a defendant with knowledge that removal jurisdiction existed would be blocked from removing the case if the plaintiff delayed filing the case by more than 30 days. The case also points up an interesting feature of the Texas statute, which allows a plaintiff that has elected to file suit in a Texas district court to later remove the case to the Business Court.
The issues raised by SafeLease were sufficiently concerning to the 2025 Texas Legislature that it amended Sec. 25A.006(f)(1)[132] to definitively resolve the issue (amendments italicized):
(f) If all parties to the action have not agreed to remove the action, the notice of removal must be filed: (1) not later than the 30th day after the later of:
(A) the date the party requesting removal of the action was served with process in accordance with rules adopted by the supreme court; or
(B) the date the party requesting removal of the action discovered, or reasonably should have discovered, facts establishing the business court’s jurisdiction over the action; . . . .
First Completed Business Court Trials—Filing to Judgment in Eight Months.
The Business Court’s judges generally seek to obtain the parties’ commitment to a trial date within 18 months of the commencement of a proceeding, a time period not reached by any Business Court cases during 2025 given its September 1, 2024, starting date, after which only newly filed cases would be accepted by the court. That being said, two cases were moved along with unusual dispatch by the parties and the judges, allowing bench trials and judgments on the merits during 2025: Primexx Energy Opportunity Fund II, LP, v. Primexx Energy Corporation (Primexx) in the First Division[133] and Marathon Oil Co. v. Mercuria EnergyAmerica, LLC (Marathon) in the Eleventh Division.[134] In each case the judge made use of Texas Rule of Civil Procedure 166(g) in connection with the development of the case’s Scheduling Order to identify issues of law that would be briefed by the parties and argued to the court early in the case to accelerate and increase the efficiency of the proceeding:
In an appropriate action, to assist in the disposition of the case without undue expense or burden to the parties, the court may in its discretion direct the attorneys for the parties and the parties or their duly authorized agents to appear before it for a conference to consider: . . . (g) The identification of legal matters to be ruled on or decided by the court; . . . .[135]
While Rule 166 is reported to be seldom used in this way in Texas trial courts, it shows good promise of becoming a regularly used tool by the Business Court that can support early resolution of cases through settlement or adjudication and reduction of costs by avoiding discovery and trial preparation in areas no longer relevant to the proceeding.
The opinions in these cases provide instructive reading for business lawyers negotiating and drafting Texas law agreements as well as for trial lawyers litigating those agreements. They amply demonstrate the benefits of having complex business disputes decided by specialized judges who support their decisions with written opinions. The cases also demonstrate the willingness of the Business Court’s judges to take innovative approaches that improve the efficiency of the trial process.
Primexx.[136] The plaintiffs in Primexx were two limited partners suing a private equity limited partnership’s controlling and managing partners over their exercise of a drag-along sale right on terms the limited partners believed had violated duties owed to them under the Texas Business Organizations Code (TBOC), Texas common law and the partnership agreement, producing a grossly inadequate sale price. The agreement at issue included terms limiting specified partner duties to the maximum extent permitted by the TBOC, and giving the defendant controlling and managing partners significant latitude to act based upon their sole interests, specifically when exercising their drag-along sale rights in circumstances where, as in this case, the sale occurred more than two years after the partnership’s formation.[137]
This case followed an interesting path to the Business Court. Following two earlier false starts, successively in Texas and federal courts, the third predecessor lawsuit to this proceeding had again been filed in Texas state court on July 31, 2023. On September 1, 2024, the case was pending in the 298th Judicial District Court in Dallas County. The enthusiasm of the parties over the Business Court’s opening on September 1, 2024, led them to remove the action to the Business Court’s First Division, by agreement of the parties, on September 27, 2024. After being made aware that the Business Court could not accept removals of pending cases that had commenced prior to September 1, 2024, the 2023 state district court case was nonsuited. Following that, again by agreement of the parties, the action was refiled as a new proceeding in the Business Court’s First Division on October 25, 2024, where it proceeded to final judgement on June 16, 2025.
Judge Whitehill’s three opinions on the merits address in detail the nature and scope of partners’ statutory and common law duties and their obligations to perform them in good faith and in the best interest of the partnership. The opinions highlight the extent to which freedom of contract principles (described as a “sacred right”) are embedded in Texas law, particularly in the case of agreements made by sophisticated parties represented by counsel.[138] The opinions review in detail each action of the defendants that plaintiffs assert to constitute “bad faith,” finding none that clearly fit into the factual situations supporting the mainstream of Texas partnership breach of duty cases.
These principles are then analyzed in the specific context of the exercise of detailed, heavily negotiated contractual drag-along rights to force the sale of the partners’ investments at a time and upon terms of the defendants’ choosing. The opinion observes that such agreements are well understood by sophisticated business parties to entail the risk of being exercised in the context of material conflicts of interest among the parties to the partnership agreement. The court notes the absence of any prior Texas judicial decisions applying the law of partners’ duties to the specific context of an exercise of drag-along sale rights.
Ultimately, Judge Whitehill saw the plaintiffs’ arguments as an attempt to make use of general, conclusory assertions of “bad faith” based on a bad business result to rewrite the relevant language of the partnership agreement, with which the defendants were found to have fully complied, in ways that the plaintiffs could have, and should have, negotiated for when the agreement was drafted. In the context of experienced parties with expert counsel negotiating this type of complex agreement, when Texas principles of freedom of contract as applied to sophisticated parties are also considered, Judge Whitehill found there was no basis in Texas law or the evidence produced that would support the court doing anything other than enforcing the agreement as written, denying the plaintiffs’ claimed right to recover damages.
Marathon. This case arose from a declaration of force majeure by Marathon as it became unable to perform under an agreement to sell and deliver natural gas to Mercuria during “Winter Storm Uri” in February 2021. That event’s widespread freezing temperatures caused a severe power crisis in Texas as demand for electric power and natural gas peaked just as the freezing weather caused the widespread failure of natural gas infrastructure across the state. Businesses and millions of residents lost electricity, natural gas and water. More than 240 deaths were reported. The weather conditions resulted in widespread disruptions in the performance of contracts to deliver natural gas and electricity, and wide swings in the market prices for those resources, resulting in billions of dollars in losses and hundreds of lawsuits.
Marathon filed this action seeking declaratory relief under Texas Civil Practice and Remedies Code Sec. 37.001 on March 4, 2025, after Mercuria invoiced Marathon for more than $17 million dollars in asserted “cover damages” incurred as a result of Marathon’s failure to deliver to Mercuria agreed quantities of natural gas under the parties’ agreement after Marathon declared a force majeure event during Winter Storm Uri under the terms of the parties’ agreement.
The parties had entered their contract through a semi-automated system established by the natural gas industry to support ease of contracting by industry parties. The system relies upon a Base Contract for Sale and Purchase of Natural Gas, underlying principles of Texas contract law, particularly the Texas Business and Commerce Code, and incorporates related terms and methods for modifying the agreement to fit a specific transaction. The parties had communicated electronically and by telephone as the agreement was negotiated, exchanging confirmations as one of the final steps in the process. In hindsight, Mercuria asserted that the confirmations had conflicting terms and that its confirmation terms should prevail over Marathon’s, materially changing Marathon’s obligations.
Judge Andrews’ first opinion[139] goes painstakingly through the technicalities of the contracting process and the parties’ communications to determine whether or not they had reached a common agreement with a single set of material, binding terms, such as whether Marathon’s duty to exercise reasonable efforts to perform the contract extended to obtaining alternative gas supplies after a force majeure event. Her opinion ultimately concludes that the agreement terms, including the two competing confirmations, when appropriately interpreted, did not conflict and were part of a single complete agreement that excused Marathon from any obligation to purchase gas at the best (exorbitant during the emergency) price available.
Her second opinion[140] parses the agreement of the parties and Texas law of force majeure in detail on the way to concluding that Marathon was not obligated to acquire replacement gas, or compensate Mercuria for doing so, as a required “reasonable effort” to alleviate the adverse effect of the force majeure declaration on Mercuria, providing Marathon a partial summary judgment on that issue. The third opinion[141] declines to take a firm position on the parties’ various damage theories due to inadequacy of legal argument and evidentiary support, other than to conclude that one theory advanced by Marathon was not available in the circumstances of the case.
The case proceeded to a bench trial on November 3, 2025, after which Judge Andrews rendered judgment for Marathon on its requested declaratory judgement that it owed nothing to Mercuria, and for Mercuria on Marathon’s claim for attorney’s fees.
§ 3.15. West Virginia Business Court Division
American Bituminous Power Partners, L.P. v. Employers’ Innovative Network, LLC et al.[142](Order granting dismissal for lack of personal jurisdiction). Originally filed in 2020, this matter concerned an allegedly wrongfully retained sum of more than $970,000 in payroll overpayments made under a services agreement between the parties. The plaintiff asserted claims for breach of contract, conversion, unjust enrichment, breach of fiduciary duty, breach of good faith and fair dealing, and civil conspiracy, and sought full repayment, contractual interest, punitive damages, attorneys’ fees, and other appropriate relief against the defendant and its two holding companies. On December 8, 2021, the defendant moved to dismiss the holding companies for lack of personal jurisdiction. In response, the plaintiff requested leave to conduct jurisdictional discovery to establish the holding companies’ minimum contacts, tortious conduct, and alter ego relationships.
The Business Court Division granted the defendants’ motion to dismiss on September 22, 2025, concluding that mere status as a holding company does not establish personal jurisdiction under the West Virginia long‑arm statute. In reaching its decision, the Court closely examined the relationships among the entities and found that, beyond bare ownership, neither holding company was a party to the underlying contract nor conducted business in West Virginia in a manner supporting the plaintiff’s claims. Additionally, four years of discovery failed to reveal any additional jurisdictional ties. Thus, the Court dismissed the holding companies from the action.
Alltranstek, LLC and Rescar Companies v. Axiall Corp.[143] (Order denying motion to dismiss or stay complaint for declaratory judgment). This matter concerns a dispute over the interpretation of a settlement agreement that the defendant now seeks to use to recover certain litigation-related fees. The underlying facts involve an industrial incident that led to multiple lawsuits, and, ultimately, a global settlement between the parties.
On April 21, 2025, the defendant filed a combined motion asking the Business Court Division to either dismiss the plaintiffs’ declaratory judgment action or stay it in favor of ongoing proceedings in Pennsylvania. In support, the defendant argued that the Pennsylvania court was the appropriate forum, that the West Virginia court lacked a justiciable controversy, and that the request for declaratory relief was premature. The Business Court Division rejected each of those arguments. It held that the declaratory judgment complaint was sufficiently pled under West Virginia law; that a real, present controversy existed because the defendant expressly stated its intent to pursue attorneys’ fees despite the settlement; and that West Virginia courts have clear jurisdiction to interpret and enforce the settlement agreement, which did not exist when the Pennsylvania judgment was entered. The Court further found that the Pennsylvania remand is narrowly limited to identifying what portion of fees relate to third‑party defense—not to interpreting a later contract—and therefore does not preclude or supersede West Virginia’s authority. Finally, the Court concluded that issuing a declaration would meaningfully resolve the parties’ dispute and thus denied the motion to dismiss or stay in its entirety.
§ 3.16. Wyoming Chancery Court
Keystone Capital Partners, LLC v. Life Clips, Inc.[144](Receivership).This case summarizes Wyoming’s statutory grounds for appointing custodians or receivers for Wyoming corporations. Wyoming’s statute permits appointment of a receiver or custodian when the board is deadlocked or engaged in fraud. Wyo. Stat. § 17-16-748(a). Elaborating on the concept of corporate deadlock, the court explained that “corporate abandonment is not corporate deadlock.” Deadlock requires actual dissension, not mere inaction.
A separate Wyoming statute authorizes appointment of a receiver when a corporation has been dissolved, is insolvent, is in immediate danger of insolvency, has forfeited its corporate rights, or in any circumstance where courts of equity have appointed receivers. Wyo. Stat. § 1-33-101(a)(vii) and (viii). The chancery court added some color to each of these grounds.
Beginning with dissolution and corporate forfeiture, the court noted these grounds include administrative dissolution by the Wyoming Secretary of State for failure to deliver annual reports or pay annual license taxes.
Turning to insolvency, the court observed the term’s different meaning depending on context and the different tests for insolvency, noting the Wyoming Supreme Court had not offered recent guidance. The chancery court suggested that a Wyoming court would likely find insolvency when a corporation either has assets insufficient to cover liabilities without a reasonable prospect of successful continuation or is unable to meet maturing obligations as they fall due in the ordinary course of business. When evaluating insolvency, stock price is a data point, but only for stocks traded on open, efficient markets. As to imminent danger of insolvency, drawing on Wyoming caselaw, the court explained that the following can suggest imminent insolvency: risk of asset value depreciation, corporate abandonment, and lack of operational funds.
The court also discussed the catchall provision permitting receivership where equity courts have traditionally exercised that power, noting courts of equity appointed receivers in circumstances such as gross mismanagement, abandonment of corporate responsibilities, or a solvent corporation’s cessation of operations without any likelihood of resuming operations successfully. Whatever the grounds, the court reiterated that receivers must be appointed only when necessary and only to perform acts essential to accomplishing the receivership’s purpose.
Applying these principles, the court granted a request by a Delaware company and shareholder of the Wyoming corporation to appoint its CIO as custodian or receiver. The court grounded its decision to appoint a receiver for reinstatement purposes on the corporation’s administrative dissolution and further relied on the equitable catchall provision, citing the gross mismanagement and dereliction of duty by the corporation’s directors. Notably, the court declined to rest its decision on abandonment, reiterating that while the directors had abandoned the corporation, abandonment does not constitute deadlock. The court likewise declined to ground the appointment in insolvency because the record did not provide a clear picture of the corporation’s financial condition or the value of its assets.
Chagnon v. Nelson[145](Improper use of AI).Responding sua sponte to a motion to dismiss filed by pro se defendant Nelson, this order discerned a high likelihood of unchecked use of generative artificial intelligence and ordered Ms. Nelson to show cause why the case should not be dismissed. The motion raised hallucinated precedent of the Wyoming Chancery Court and, at 31 pages single spaced, presented no governing authority to support its numerous legal rules. While noting that the chancery court embraces new technology, the order highlighted that improper use of AI is sanctionable because it requires almost no effort of the drafter while tasking the court and opposing counsel with the arduous task of determining what points, if any, are valid under Wyoming law. Defendant Nelson did not file in response to the order, and the case was accordingly dismissed. See Chagnon v. Nelson, 2025, WYCH 9 (Wy. Ch. Ct. July 11, 2025).
For a more detailed discussion on what may be defined as a business court, see generally A.B.A. Bus. Law Section, The Business Courts Bench Book: Procedures and Best Practices in Business and Commercial Cases (Vanessa R. Tiradentes, et al., eds., 2019) [hereinafter Business Courts Bench Book]; Mitchell L. Bach & Lee Applebaum, A History of the Creation and Jurisdiction of Business Courts in the Last Decade, 60 Bus. Law. 147 (2004) [hereinafter Business Courts History]. ↑
For an overview of business courts in the United States, see, e.g., Business Courts Bench Book, supra note 1, Business Courts History, supra note 1, Lee Applebaum & Mitchell L. Bach, Business Courts in the United States: 20 Years of Innovation, in The Improvement of the Administration of Justice (Peter M. Koelling ed., 8th ed. 2016); Joseph R. Slights, III & Elizabeth A. Powers, Delaware Courts Continue to Excel in Business Litigation with the Success of the Complex Commercial Litigation Division of the Superior Court, 70 Bus. Law. 1039 (Fall 2015); John Coyle, Business Courts and Inter-State Competition, 53 Wm. & Mary L. Rev. 1915 (2012); The Honorable Ben F. Tennille, Lee Applebaum, & Anne Tucker Nees, Getting to Yes in Specialized Courts: The Unique Role of ADR in Business Court Cases, 11 Pepp. Disp. Resol. L. J. 35 (2010); Ann Tucker Nees, Making a Case for Business Courts: A Survey of and Proposed Framework to Evaluate Business Courts, 24 Ga. St. U. L. Rev. 477 (2007); Tim Dibble & Geoff Gallas, Best Practices in U.S. Business Courts, 19 Court Manager, no. 2, 2004, at 25. Further, the Business Courts chapter of this publication has provided details on developments in business courts every year since 2004. Finally, the Business Courts Blog went online in 2019, and serves as a library for past, present and future business court developments, www.businesscourtsblog.com (last visited May 27, 2026). ↑
Business Courts Bench Book, supra note 1, at xx. ↑
Business Courts History, supra note 1, at 207, 211. ↑
Gerard V. Mantese, of Mantese Honigman, PC, the co-chair of the Business Law Section’s LLCs and Partnerships Committee and current chair of the In-House Counsel Committee, organized, moderated, and presented at the program. A summary of that program is included in Toering, Mantese, and Klida, Touring the Business Courts: Succession Planning and Shareholder Litigation Program; Recent Developments Nationally and in Delaware and New York, 45 Mich. Bus. L. J. 12 (Summer 2025), https://higherlogicdownload.s3.amazonaws.com/MICHBAR/ebd9d274-5344-4c99-8e26-d13f998c7236/UploadedImages/pdfs/journal/Summer25.pdf#page=14. ↑
The Michigan Judicial Institute is responsible for training business court judges. Mich. Comp. L. § 600.8043. The MJI typically conducts two training sessions each year specifically for the business court judges. Business court judges typically attend other MJI events over the course of a year, some of which may be relevant to business disputes. Many Michigan business court judges also attend events sponsored by the American College of Business Court Judges. ↑
One of the authors of article, Douglas L. Toering, is responsible for the business courts blog. This was previously handled by Philadelphia attorney Lee Applebaum. ↑
H.B. 19, 88th Leg., Reg. Sess. (Tex. 2023) (https://www.legis.state.tx.us/tlodocs/88R/billtext/html/HB00019F.HTM) codified as Tex. Gov’t Code Ann. § 25A.001, et seq. The Business Court’s website can be found at https://www.txcourts.gov/businesscourt, which includes links to relevant statutes, all published opinions of the court, biographical details of the judges, applicable rules of procedure and administration, and the court’s first annual report (https://www.txcourts.gov/media/1461667/bcot-ar-fy-25.pdf). Full Business Court case records are available at https://research.txcourts.gov. It should be noted that most of the reported opinions of the Business Court do not include the terms of the court’s final judgment deciding the case, making it advisable to review both the opinion and the final judgment to obtain a complete statement of the result. The Business Court’s judges serve two year terms ending August 31 of even numbered years and are subject to reappointment by the Governor. A map of the Business Court’s divisions can be found at https://www.txcourts.gov/media/1461706/operational-map-divisions-as2-of-dec2025.png. ↑
S.B. 1045, 88th Leg., R.S. (Tex. 2023), codified in Tex. Gov’t Code Chapter 22, primarily Subsecs. 22.201(p), 22.2151, 22.216(n-1), (n-2) and 22.220(d) (https://statutes.capitol.texas.gov/Docs/GV/pdf/GV.22.pdf). The largest part of the 15th COA docket consists of cases where the State of Texas is a party or state constitutional issues are raised. ↑
Texas Gov’t Code Sec. 25A.007(a): “Notwithstanding any other law, and except in instances when the supreme court has concurrent or exclusive jurisdiction, the Fifteenth Court of Appeals has exclusive jurisdiction over an appeal from an order or judgment of the business court or an original proceeding related to an action or order of the business court.” The Fifteenth Court of Appeals also has exclusive jurisdiction over a list of cases in which the State of Texas is a party or the interests of the state are implicated, as set forth in Texas Gov’t Code Sec. 22.220. ↑
Filings during the first four months of 2026 continued the gradual upward trend: January—28; February—23; March—30; April—39. 2026 has brought to the court an initial steady flow of bench and jury trials in cases filed in 2024 and 2025, generating a broadening base of experience and generally favorable reviews from the litigants. ↑
Sec. 1.056. REFERENCES IN CODE TO CERTAIN DISTRICT COURTS INCLUDES BUSINESS COURTS. Notwithstanding any other law, a reference or grant of jurisdiction in this code, including a grant of exclusive jurisdiction, to a district court constitutes a reference or grant of concurrent jurisdiction to a business court established under Chapter 25A, Government Code, if the business court has authority and jurisdiction under Chapter 25A, Government Code, to adjudicate the action or claim. This section does not expand the authority of the business court under Chapter 25A, Government Code.
This amendment was made to address the TBOC’s inclusion of dozens of references to Texas district courts having authority to hear and decide specific matters, in some cases describing the authority of the district court as “exclusive.” ↑
An example would be the Business Court’s Local Rule 2: “A party is deemed to agree to this Court’s supplemental jurisdiction of any claim, including a counterclaim, cross-claim, or third-party claim, unless that party moves to sever or otherwise objects within 30 days after the later of (1) the moving party’s appearance in this Court; or (2) the filing of the first pleading or removal notice containing fair notice of the claim.” ↑
As of the time this article was written the Texas Supreme Court had not published proposed rules in response to the two referenced rule-writing assignments made by the Texas Legislature in HB 40 (2025). ↑
Jordan v. Crudgington, 231 S.W.2d 641 (Tex. 1950). ↑
“District Court jurisdiction consists of exclusive, appellate, and original jurisdiction of all actions, proceedings, and remedies, except in cases where exclusive, appellate, or original jurisdiction may be conferred by this Constitution or other law on some other court, tribunal, or administrative body.” (emphasis added) ↑
Phillips, T., & Hilderbrand, M., Is the Texas Business Court Constitutional?, Tex. Lawyer (Oct 21, 2024). No articles in Texas legal publications or continuing education courses asserting the Business Court’s unconstitutionality have been noted by the author since the Business Court began receiving cases on September 1, 2024. ↑
No. 25-BC11B-059 (Tex. Bus. Ct., filed Sept. 18, 2025), removed from 215th District Court, Harris County, Texas (No. 2025-24769, filed Aug. 2, 2025). ↑
No. 25-BC11B-099 (Tex. Bus. Ct., filed Dec. 22, 2025), removed from 11th District Court, Harris County, Texas (No. 2025-89925, filed Nov. 26, 2025). ↑
How this issue has been addressed for the Texas Business Court is significant given the Court’s somewhat unique structure among the nation’s business courts as having been created as an entirely new type of statutory court, uniquely staffed with judges appointed by the governor, rather than resulting from administrative and procedural rule changes made applicable to existing trial courts and their judges as has occurred more frequently in other states. ↑
Note that House Bill 40 enacted by the Texas Legislature in 2025, in Section 45, reduced the required amount in controversy for actions arising out of qualified transactions and certain other commercial, financial and business disputes as set forth in Sec. 25A.004(d) from $10 million to $5 million, effective September 1, 2025, with the change to be applicable to actions commenced on or following September 1, 2024. ↑
2025 Tex. Bus. 1, ¶ 31. The Business Court when a case is removed from a district court, and before any motion to remand is decided, assumes administrative responsibility for continuing to move the case along through scheduled procedural hearings, and enforcing procedural deadlines. ↑
See Bus. Ct. Local Rule 8 (a) and (c) [https://www.txcourts.gov/businesscourt/practice-before-the-court/]: “(a) Removal does not alter any deadline imposed by the TRCP. Deadlines under an existing scheduling order remain in place until a new scheduling order is entered by the Business Court. All court settings are vitiated upon removal; however, the removing party must apprise the Business Court of any existing court settings in the removal notice filed under TRCP 355. . . . (c) To be considered in the Business Court, any motions pending at the time of removal must be re-filed in the Business Court and set for hearing or submission according to these rules.” ↑
Text of 25A.004(e) “The business court has civil jurisdiction concurrent with district courts in an action seeking injunctive relief or a declaratory judgment under Chapter 37, Civil Practice and Remedies Code, involving a dispute based on a claim within the court’s jurisdiction under Subsection (b), (c), or (d). ↑
“The Texas Supreme Court has stated that, when an action is brought to protect a right or privilege, ‘[t]he subjective value of a privilege, if asserted in good faith, establishes jurisdiction if that value meets the requisite amount in controversy.’ Independent of their other allegations, Defendants have pleaded that the value of the rights at issue exceeds $5 million.” Citing Tune v. Tex. Dep’t of Public Safety, 23 S.W.3d 358, 362 (Tex. 2000). ↑
Citing the U.S. Supreme Court’s decision in Dart Cherokee Basin Operating Co., LLC v. Owens, 574 U.S. 81 (2014), by analogy in the absence of applicable Texas precedent. ↑
ET Gathering & Processing LLC v. Tellurian Productions LLC, 2025 Tex. Bus. 11 (11th Div.) [defendant did not produce evidence that plaintiff’s assertion of amount in controversy jurisdictional requirements being met amounted to a sham]; Atlas IDF v. NexPoint Real Estate Partners, 2025 Tex. Bus. 16 (1st Div.); Slant Operating, LLC, v. Octane Energy Operating, LLC, 2025 Tex. Bus. 22 (8t h Div.) [plaintiff pled sufficient jurisdictional allegations, which the defendant failed to successfully refute]; Black Mountain SWD v. NGL Water Solutions Permian, 2025 Tex. Bus. 24 (8th Div.) [remand granted because uncontroverted evidence established that unpaid royalties sued for would not exceed the jurisdictional minimum]; Kassam v. Dosani, 2025 Tex. Bus. 25 (11th Div.) (mem. op.); M&M Livestock v. Robinson, 2025 Tex. Bus. 29 (8th Div.) (mem. op.); Chaudhry v. Stillwater Capital Investments, 2025 Tex. Bus. 31 (1st Div.). ↑
Business Court judges have also adopted a small number of individual rules of practice applicable to cases filed in their courts, which can be found at: https://www.txcourts.gov/businesscourt/divisions. ↑
Sec. 25A.001(14), Texas Gov’t Code: “’Qualified transaction’ means a transaction, or series of related transactions other than a transaction involving a loan or an advance of money or credit by a bank, credit union, or savings and loan institution, under which a party: (A) pays or receives, or is obligated to pay or is entitled to receive, consideration with an aggregate value of at least $5* million (emphasis added); or (B) lends, advances, borrows, receives, is obligated to lend or advance, or is entitled to borrow or receive money or credit with an aggregate value of at least $5* million.” *House Bill 40 enacted by the 89th Texas Legislature to be effective September 1, 2025, amended Sec. 25A, Texas Gov’t Code, to reduce these amounts from $10 million to $5 million. ↑
Texas Gov’t. Code Sec. 25.006(f) [as in effect at time opinion issued on Feb. 10, 2025] “. . . If all parties to the action have not agreed to remove the action, the notice of removal must be filed: (1) not later than the 30th day after the later of the date the party requesting removal of the action discovered, or reasonably should have discovered, facts establishing the business court’s jurisdiction over the action; . . . .” ↑
Section 47, House Bill 40, 2025 Texas Legislature. ↑
Judge Whitehill produced a total of five opinions in the course of resolving this dispute. Two opinions dealt with the court’s jurisdiction over some out-of-state individual defendants considered in special appearances: 2025 Tex. Bus. 5 (1st Div.; Feb. 10, 2025) and 2025 Tex. Bus. 26 (1st Div.; Jul. 16, 2025). 2025 Tex. Bus. 9 (1st Div.; Mar. 10, 2025) is the primary 79-page opinion explaining Judge Whitehill’s decision on the merits, which granted summary judgment to the defendants based on an extensive, detailed parsing of Texas partnership and contract law and the lengthy, complex agreement of the parties. 2025 Tex. Bus. 13 (1st Div.; Apr. 15, 2025) is a rare instance of a Texas trial court considering further rebuttal arguments from plaintiffs on the issues adjudicated in favor of the defendants by the court’s earlier judgment (all of which further arguments the court rejected) in order to clarify the record. Lastly, in 2025 Tex. Bus. 21 (1st Div: May 22, 2025) Judge Whitehill addressed a narrow set of issues, dismissing with prejudice the plaintiff’s causes of action against specific individual defendants in response to a request for clarification supported by all parties. On June 3, 2025, the parties completed a Rule 11 Agreement providing for dismissal without prejudice of the remaining claims not addressed in the opinions issued at that date against all but the primary defendants, allowing the causes of actions and claims dismissed by Judge Whitehill to proceed to an appealable judgment. Summary judgement was granted in favor of the remaining defendants, with two minor exceptions, with plaintiffs taking nothing by a Final Judgment dated June 16, 2025 (1st Div.). That Final Judgment is currently before the Fifteenth Court of Appeals. ↑
Judge Andrews (of the Third Division, sitting by assignment in the 11th Division) produced three opinions in the course of resolving this declaratory judgment action in favor of Marathon. The first opinion, 2025 Tex. Bus. 36 (11th Div.; Sep.18, 2025), addressed issues of contract interpretation raised in a Joint Advisory on Early Legal Issues included in the case’s Scheduling Order that sought early decisions by the judge to support efficiency or resolution of the action. The second opinion, 2025 Tex. Bus. 39 (11th Div.; Oct. 14, 2025), addressed further issues of contract interpretation and supported the court’s grant of partial summary judgment to Marathon. The third opinion, 2025 Tex. Bus. 40 (11th Div.; Oct. 28, 2025), evaluated the parties’ competing theories of damages, resulting in a “no decision” on Mercuria’s proposed actual and spot-price data due to a lack of sufficient arguments and evidence and a determination that Marathon’s proposed cost-based measure of actual damages was not the correct legal standard. Neither of the parties appealed Judge Andrews’ decisions. ↑
The speed with which these cases were decided likely had some non-replicable tailwind supplied by their arrival in the Business Court’s early months of docket building, the relatively narrow legal and factual focus of each case and avoidance of what would have been difficult determinations of damages. The cases do demonstrate the efficiency that can result from the Business Court’s early resolution of legal questions that then avoid unnecessary ongoing expenditures of the parties’ time and money. ↑
Artificial intelligence features are rapidly being embedded into the enterprise software that organizations rely on daily. From customer relationship management platforms and document management systems to human resources tools and financial reporting software, technology vendors are racing to integrate AI capabilities into their existing products, particularly software-as-a-service (“SaaS”) offerings. For clients, this trend presents a mix of opportunity and risk.
When your vendor announces that it is adding AI features to a product you already license under an existing contract, the legal and practical implications can be significant. Legacy agreements were not drafted with AI in mind, and the terms governing data use, intellectual property, termination, and liability may be wholly inadequate once AI enters the picture.
This article provides a practical framework for evaluating and responding to vendor-initiated AI changes, including the risks created by legacy contract gaps and critical considerations when reviewing vendor-proposed AI addenda. A follow-up article will discuss the key features that should be included when a client decides to develop its own AI addendum for use in negotiations and contracts.
I. AI Features Are Coming—Whether You Asked for Them or Not
Most major SaaS providers have introduced, or are actively rolling out, AI-powered features within their existing product suites. These range from AI-assisted search and summarization tools to automated drafting, predictive analytics, and large language model (“LLM”) integrations. These features are often activated by default—without explicit customer consent and sometimes without any advance notification. Unfortunately, this so-called “stealth AI” can create significant contract challenges. Under traditional SaaS contracts, your organization provides data, the vendor hosts and processes it, and defined terms control what happens to that data during and after the relationship. AI challenges and changes many of these assumptions.
Legacy Contracts Were Not Drafted for AI
When your vendor adds an AI feature into an agreement that was never designed for it, several critical contract gaps may emerge:
Outdated definitions. It’s highly unlikely that the standard definition of “Customer Data” in your existing SaaS agreement captures prompts, outputs, embeddings, or other AI-specific data categories. If your “Customer Data” definition is narrowly defined, the protections you negotiated—including deletion obligations, export rights, and confidentiality protections—may not reach the data that AI features generate or consume.
Inadequate deletion obligations. Any termination obligation to delete “Customer Data” at the end of the contract is quite limited if the definition does not capture prompts, outputs, embeddings, or trained model weights. Your vendor may be contractually compliant in deleting your CRM records while retaining the AI-derived insights and analytics learned from your data indefinitely.
Broken data flow assumptions. The original SaaS contract may assume a relatively straightforward data flow between your organization and the vendor’s infrastructure, with a few subprocessors thrown in (once you review the data processing agreement). However, AI features may introduce new data complexities. For example, your data may be sent to third-party LLM providers, used to train vendor or third-party models, or otherwise processed in jurisdictions not contemplated by the original agreement. The details may (or may not) be in the fine print.
Default activation without consent. Perhaps the most concerning gap is that many AI features are activated by default without express notice from your vendor. Your organization may already be feeding sensitive data into an AI tool without anyone having reviewed or approved the terms under which that data will be processed.
Insufficient legacy termination clauses. Traditional termination provisions address subjects such as material breach and bankruptcy/insolvency, but they do not contemplate AI-specific termination trigger events such as model deprecation/degradation, foundation model substitution, changes in the vendor’s acceptable use policy that restrict use cases, or regulatory prohibitions. These are new categories of risk that require new exit rights.
Why This Matters Now
The window for negotiating favorable AI terms is often narrow. Once AI features are live and customer data is being processed through them, your leverage diminishes significantly. Vendors have little incentive to renegotiate terms after the fact, and the practical difficulty of unwinding AI data processing creates a form of lock-in that is fundamentally different from traditional SaaS lock-in.
Clients should treat any vendor communication about new AI features—whether a product announcement, a contract amendment, or a click-through addendum—as a trigger to review their existing agreement and take any necessary action to remedy any concerns.
II. Reviewing a Vendor-Proposed AI Addendum
When a vendor proposes an AI addendum to an existing agreement, it is essential to approach the document with the same level of diligence, rigor, and scrutiny that you would apply to a new contract. Typically, vendor-drafted AI addenda are designed to expand the vendor’s rights and limit its liabilities, often in ways that directly contradict the protections you painstakingly negotiated in the underlying agreement.
The Click-Through Trap
Many vendors present AI addenda to clients through click-through mechanisms, such as hyperlinked documents within the existing platform, pop-up acceptance screens, or standalone nonnegotiable terms posted on a vendor website. These are likely not benign administrative updates that should be blindly accepted. They are often substantive contract amendments that can fundamentally alter the rights and obligations under your existing agreement. Key risks of click-through AI addenda include the following:
Contradicting negotiated terms. The AI addendum may contain broad license grants, liability disclaimers, or indemnification carve-outs that directly override the extensively negotiated representations, warranties, limitation of liability, data protection, and restriction provisions that you carefully negotiated in the master agreement.
Embedded and hyperlinked terms. Vendors frequently embed additional terms through hyperlinks within the addendum itself, creating multiple layers of contractual obligations that you may miss during a casual review.
As a best practice, you should ask to see the vendor’s standard AI addendum at the procurement stage or renewal phase before any AI features are activated. Instruct your organization’s users not to click through or accept any vendor-presented AI terms without legal review.
Data Use, Data Privacy, and Data Security
Data provisions are typically where vendor-drafted AI addenda are most vendor-focused. Areas of concern may include the following:
Broad training rights. Vendors often seek the right to use customer data (including prompts, outputs, and usage patterns), to train, fine-tune, or “improve” their AI models. This may be framed as improving “the Services,” but it effectively grants the vendor a perpetual right to benefit commercially from your data, including potentially sensitive or proprietary data, without economic benefit to you.
De-identification as a workaround. Vendors frequently propose de-identification or aggregation as a compromise, permitting them to retain and use data in de-identified form. However, AI systems can re-identify individuals from patterns across datasets, making de-identification far less protective than it appears. Contracts should reference an industry standard for de-identification, such as NIST SP 800-188, and include an affirmative covenant by the vendor not to re-identify your data or your users.
Gaps between contract and practice. Actual vendor data usage may differ materially from what the contract says, or the contract may be silent on key data practices. It is critical to understand how the vendor (and its affiliates, subcontractors, and subprocessors) actually uses your data (including personal information or the information of your customers), and where it is stored and processed, particularly if you are in a highly regulated industry.
Liability and Indemnification for AI-Generated Outputs
AI-generated outputs additionally introduce new categories of risk. Vendor-drafted addenda typically seek to limit the vendor’s exposure in several ways:
Disclaiming accuracy. Almost all standard AI agreements state that outputs are made available on an “as-is,” “as-available” basis, and vendors commonly disclaim any representation or warranty regarding the accuracy, completeness, or reliability of AI-generated outputs. This leaves the customer to bear the risk if an AI output is incorrect, misleading, harmful, or biased or violates applicable laws.
Excluding outputs from indemnification. The vendor’s standard intellectual property indemnity often does not extend to AI-generated outputs (and the same is true of other indemnities). If an output infringes a third party’s intellectual property rights, you may have no contractual recourse against the vendor.
Disclaiming uniqueness. Vendors routinely disclaim any guarantee that AI outputs will be unique, meaning multiple customers may receive identical or substantially similar outputs. While this reflects a genuine technical limitation, it also underscores the need for robust IP protections.
Intellectual Property Ownership
IP ownership in the AI context is more complex than traditional software licensing because there are distinct categories of intellectual property at stake, each often addressed in different sections of the vendor’s contract. These include the following:
Inputs and prompt libraries. While the vendor may acknowledge that you technically own your inputs, prompts, configurations, and fine-tuning data, the fine print may reveal that such terms are then reincluded in definitions like “Service Data” or “Usage Data” and licensed back to the vendor perpetually and irrevocably. This means the vendor retains a right to use your proprietary prompts and configurations even after termination of the contract with no compensation to you.
Outputs. The statement “you own your outputs” is often not entirely accurate. In practice, ownership is frequently conditioned on ongoing compliance with the vendor’s acceptable use policy, and outputs are generally excluded from the vendor’s standard IP indemnity. What you receive may be a conditional assignment rather than true, unfettered and unconditional ownership, so confirm the contract language carefully.
Feedback and ratings. Customer feedback and ratings, which may be provided via thumbs up/down ratings, corrections, and evaluation results, are typically defined outside of the standard “Customer Data” definition and may be licensed to the vendor under a separate perpetual, irrevocable license that survives termination. As this data sits outside your negotiated data protections, none of the negotiated contractual safeguards will apply.
Opt-Out Rights and Transparency
Opt-out rights. Clients should also ask whether the proposed AI features are optional or required to use the updated vendor product. Unfortunately, even where a vendor offers the ability to turn off an AI feature, toggling off the user interface may not actually stop the vendor from using your data for training or model improvement purposes. Clients should confirm whether toggling off the feature actually stops all data processing associated with it. Similarly, you should ask whether toggling off the AI feature preserves your right to delete what has already been ingested.
Transparency and model substitution. Vendors may swap, replace, or materially reconfigure their underlying foundation models without providing notice to customers. A model swap can materially change the data practices, accuracy, and performance characteristics of the vendor product. Clients should require advance written notice of any vendor model changes and should understand whether a model swap changes any data-use, training, or processing commitments of the vendor.
Compliance with Applicable Law
The regulatory landscape for AI is evolving rapidly. Vendor-drafted addenda may not adequately address (i) compliance with current and emerging AI-specific regulations in applicable jurisdictions; (ii) regulatory actions or adjudicated IP findings that could impair the client’s permitted use of the product; or (iii) the allocation of regulatory risk between vendor and customer, particularly where the vendor’s AI features create compliance headaches for the customer (e.g., bias, discrimination, or failure to meet transparency requirements). Additionally, the vendor-drafted AI addenda may not contain sufficient obligations on the part of the vendor to stay abreast of key regulatory developments during the contract period.
III. Creating a Client-Side AI Addendum
Rather than accepting vendor-drafted AI terms, it is far better for clients to proactively develop their own standard-form AI addendum for use in negotiations. A well-crafted client-side addendum establishes the client’s baseline expectations and provides a structured framework for evaluating the vendor’s AI capabilities and practices. Stay tuned for Part Two of this article for a more detailed discussion about suggested AI addendum best practices and next steps.
Bankruptcy law has a timing problem. A company may still be paying its debts, no petition may have been filed, and no court may be involved. Yet a lender’s credit model may already have detected deterioration in that company’s risk profile. A supplier may be reassessing payment terms. An insurer may be repricing exposure, while a major customer may be quietly considering whether the company remains a reliable counterparty. None of these decisions requires a bankruptcy filing or any formal legal recognition of distress.
The gap matters because prediction can change the condition it predicts. A lender that reduces exposure affects liquidity. A supplier that shortens payment terms does the same. A customer that begins shifting orders elsewhere changes expected revenue. Each actor may simply be managing its own risk. But a company that eventually reaches Chapter 11 may arrive there with its commercial position already altered by decisions made well before bankruptcy law entered the picture.
In earlier work, I used the term Algorithmic Shadow Insolvency to describe the predictive gap in which financial distress begins shaping restructuring decisions before those decisions become legally visible.[1] This article looks at that gap from a practitioner’s perspective: What changes when commercially important actors can see, price, and act upon financial deterioration before a bankruptcy case begins? The concept does not suggest that an algorithm can declare a company insolvent, nor does it propose another legal test for insolvency.
From Prediction to Commercial Consequence
Credit models have long influenced lending decisions. What is changing is not simply their sophistication. Risk can increasingly be reassessed through model-based processes and translated into commercial decisions before the events that traditionally make distress unmistakable. That question is becoming more immediate as model-based risk assessment moves deeper into ordinary financial decision-making. U.S. banking regulators’ revised 2026 model risk guidance reflects how embedded quantitative models have become in significant banking activities.[2] Bankruptcy-prediction research likewise shows that machine-learning methods can improve predictive performance over traditional approaches.[3]
For restructuring lawyers, however, prediction accuracy is only half the question. The harder problem begins when prediction changes behavior. A lender may reduce exposure without terminating a facility. A supplier may shorten terms without ending the relationship. An insurer may reprice risk. A customer may diversify its supply chain before canceling a contract. Each decision may be rational in isolation. Taken together, they can progressively reduce the company’s room to maneuver.
This is where Algorithmic Shadow Insolvency differs from the familiar idea of an early warning system. Early warning generally asks whether distress can be identified soon enough for the company, its advisers, its creditors, or public authorities to respond. Predictive systems operating throughout a company’s commercial network create a different possibility.[4] The company may not control those systems, know which signals they are detecting, or even realize that counterparties have begun to react. The warning may no longer be delivered to the company in distress. It may be delivered to everyone around it.
That distinction matters in Chapter 11. Filing activates legal mechanisms that can protect the debtor and support continued operations, including the automatic stay, debtor-in-possession authority, and access to postpetition financing subject to statutory requirements.[5] But formal protection does not recreate every commercial condition that existed before filing. If credit has tightened, suppliers have reduced exposure, customers have begun diversifying, or strategic capital has become hesitant, the legal process inherits those changes. The filing date remains legally decisive. Commercially, it may no longer be the beginning of the story.
Protecting the Restructuring Window
The practical response is not necessarily to file earlier. That would confuse predictive information with the decision to invoke a formal bankruptcy process and, in many cases, miss the problem entirely. The more immediate question is whether the company is losing viable restructuring options while management and counsel are still measuring distress principally through liquidity, covenant compliance, debt maturities, defaults, and other familiar indicators.
A different approach begins with the reactions surrounding the company. Shorter payment terms, reduced credit availability, additional collateral demands, insurance repricing, customer diversification, or hesitation by strategic investors may each be ordinary commercial events. They should not automatically be treated as evidence of impending bankruptcy. But when several appear together around a financially pressured company, treating each as an unrelated inconvenience may obscure something more important: The company’s risk is being reassessed outside the company itself.
A restructuring lawyer does not need access to a lender’s proprietary model or a supplier’s risk system to recognize that shift. The algorithm may be invisible; its commercial footprint is not. Counsel can observe changes in counterparty behavior and ask whether they form a broader pattern. The relevant inquiry is whether those changes are beginning to affect liquidity, operating continuity, or the range of restructuring choices still available.
That distinction matters because restructuring options do not disappear at once. They narrow. A financing source becomes more expensive. A critical supplier becomes less patient. A customer becomes less willing to depend on the company. Strategic capital becomes harder to secure. None of these developments necessarily requires Chapter 11. But each can make a restructuring that later becomes necessary more difficult to execute.
The appropriate response is therefore preparation rather than panic. Counsel and management can identify the relationships most capable of affecting continuity, determine whether adverse changes are isolated or cumulative, preserve liquidity, engage critical counterparties while confidence can still be stabilized, test alternative financing, and prepare restructuring options before those options become materially narrower.
The objective is not to file earlier. It is to recognize earlier when the ability to restructure is beginning to erode.
In practical terms, that means three things: detect the reaction, map the pattern, and preserve optionality. This does not turn every adverse commercial signal into a restructuring event, and it does not require lawyers to become data scientists. It asks restructuring counsel to do something much more familiar: understand the company as a business operating within a network of relationships and recognize when those relationships begin changing faster than the traditional indicators of distress.
The Question for Chapter 11
Chapter 11 will continue to have a legally identifiable beginning. Algorithmic Shadow Insolvency concerns the period before it—that is, the weeks or months during which commercially consequential responses may accumulate without a filing, judicial supervision, or a formal restructuring process. That period matters precisely because meaningful choices may still exist within it.
The point is not to give predictive models legal authority, nor to treat every algorithmic warning as evidence of insolvency. The more immediate implication is for restructuring practice. If the commercial environment surrounding a company can recognize changing risk earlier, counsel may need to ask not only whether a filing or other restructuring step is approaching but also whether important counterparties have already begun behaving as though the company’s risk has changed.
That suggests a different form of early intervention. It does not begin with a petition. It begins with preserving the conditions under which a restructuring can still work. By the time distress is obvious enough to force the filing question, some of those choices may already be gone.
Off. of the Comptroller of the Currency, Bd. of Governors of the Fed. Rsrv. Sys. & Fed. Deposit Ins. Corp., OCC Bulletin 2026-13: Model Risk Management: Revised Guidance (Apr. 17, 2026). ↑
Tokenization—the representation of assets as digital tokens on a decentralized ledger or blockchain—has attracted significant attention among market participants, particularly in the financial sector. Analysts predict that tokenized assets, driven in part by the prospect of greater efficiency and accessibility in the financial system, could be valued between $10 trillion and $16 trillion by 2030.[1] Attorneys advising clients in this dynamic area of the law need to stay informed about the complex issues and changes in this space.
This piece examines a confluence of key regulatory, market, legal, and legislative issues driving tokenization adoption in financial markets through the lens of the prevailing competition between incumbents and new entrants, as stakeholders balance the technology’s value proposition against its idiosyncratic risks. It provides a snapshot and a useful framework for analyzing the rapidly evolving developments in digital assets as regulators and policymakers attempt to calibrate the optimal purview of regulation when it is at odds with technological development, in a manner that maintains market integrity, fosters competition, and supports a bedrock principle of our capitalist system in which market forces dictate winners and losers.
Essentially, tokenization is a new technology applied to financial products and services. As with the dematerialization of paper stock certificates to uncertificated form, the introduction of electronic exchanges, and other innovations, the use of blockchain and tokenization as a new medium for transferring value introduces distinct risks and opportunities juxtaposed to its traditional counterpart of book-entry or centralized ledgers.
Core value propositions of tokenization include:[2]
programmability—the ability to embed code-based instructions that automatically execute when predetermined triggering conditions are met;
fractionization—dividing assets into smaller, tradable units;
atomicity—the execution of multiple inseparable transactions, such that either all occur or none occur; and
composability—the ability to combine and reuse programmed instructions in new ways to develop different products and services.
While tokenization aims to provide a more direct, trustless, and dynamic way to transfer value, blockchain technology is in discord with various established regulatory frameworks and legal constructs. Specifically, the current financial, legal, and regulatory system relies on conventional custody of assets and a network of intermediaries to facilitate transactions and to assign legal responsibility and accountability, practices that are often incongruous with blockchain-based systems.
Differentiating Factors Between Tokenization and Blockchain-Based Systems and Conventional Book-Entry Systems
Pinpointing the key differences between tokenization and blockchain-based systems, and conventional book-entry systems, helps advance the conversation. Specifically, on a blockchain, ownership and asset transfers are not recorded and validated centrally on a master ledger but rather on every computer node running the software, collectively, in accordance with the agreed-upon protocol. As such, the authority of the determinative entity (the blockchain or code) that establishes ownership is decentralized. This creates idiosyncratic risks—notably, the relative immutability of transactions, which makes fraud and errors difficult to reverse.[3] Additionally, blockchain infrastructure poses various custody risks, including the risk that the loss or theft of the private key associated with an asset can result in irreversible loss.[4] Furthermore, blockchain’s decentralized features create challenges in ascribing legal responsibility and accountability to intermediaries and market participants.
Intrinsically, the core value proposition of tokenization—to increase the dynamism and velocity of asset transfers and reduce opacity in financial markets—rests on the diffusion of authority within the network and the ubiquity of the ledger among participants. These same forces also create potential friction points in the financial system and discord with traditional legal and regulatory frameworks. Policymakers are balancing the need to provide a conducive pathway for new technology to compete (including adjusting regulatory approaches when technology renders certain constructs obsolete) against other mandates and priorities.
Primary Ways to Structure a Token
Principally, there are three ways to structure a token: as a token issued by the issuer or its representative of the underlying asset in the form of a digital twin token (“DTT”) or a digital-native token (“DNT”) or through various models of a third-party token (“TPT”). In a DTT model, an issuer issues a token that serves as a digital representation of an asset on a blockchain that exists or was issued off-chain, and the master record of ownership of the asset is maintained in traditional book-entry form. In a DNT model, a token represents an asset issued on-chain, and a decentralized ledger or blockchain serves as the master record of ownership. A TPT, by contrast, does not derive from the issuer of the underlying asset or its affiliate. This narrow framework is not meant to be exhaustive; rather, it highlights key issues in tokenization.
SEC’s Directives on Tokenization
Primarily, there are two main potential development models for tokenization: one in which the technology eliminates the need for certain intermediaries (clearinghouses, exchanges, brokers, dealers, etc.) and upends bedrock principles such as custody; and another in which market intermediaries incorporate the technology into their products and services.
Proponents of blockchain technology argue that today’s market infrastructure is the legacy of decades of layering intermediaries and regulations atop one another in pursuit of policy goals before better technology existed.[5] This raises an important point for analysis: in the absence of legislation, what posture should regulators adopt when confronted with new technology that challenges the merits of the current regulatory infrastructure and creates market competition?
The U.S. Securities and Exchange Commission (“SEC”) Statement on Tokenized Securities issued on January 28, 2026 (“Statement”),[6] along with other enactments, provides important clarity and highlights the varied regulatory approaches to balancing technological developments with regulatory objectives and priorities. Key points of the Statement include the following:
The only difference between a security issued by an issuer (or its agent) as a DNT and a security issued in traditional form is that instead of maintaining the master security-holder file through conventional book-entry, the issuer (or its agents) maintains it on one or more decentralized ledgers or blockchains.
The format in which a security is issued (e.g., paper stock certificate, digital token) or the method by which holders are recorded (e.g., book-entry, decentralized ledger) does not affect the application of federal securities laws. Stated differently, regardless of form or recordkeeping method, if securities laws are implicated, market participants must comply with federal securities laws.
An issuer (or its agent) recordkeeping system can include a combination of decentralized ledger technology and a conventional book-entry database.
An issuer may issue its securities in various classes and formats, enabling security holders to hold them in different forms, including a combination of traditional and tokenized formats.
The Statement applies substance-over-form principles. If a tokenized security is substantially similar in character to a security issued in traditional format and holders of the tokenized security enjoy substantially similar rights and privileges, the tokenized security may be considered of the same class as the security issued in traditional format.
Third parties unaffiliated with an issuer of a security could tokenize the unaffiliated issuer’s security.
A TPT may or may not represent an ownership interest in or a contractual obligation of the issuer of the underlying security and, as such, may or may not confer upon the holder of the TPT any rights as a holder of the underlying security.
The structures of TPTs may vary and include custodial tokenized securities, in which an unaffiliated third party issues a token representing the underlying security held in custody, and the TPT evidences the holder’s ownership interest in the underlying security.
A TPT may be structured to provide synthetic exposure to an underlying asset, such as a tokenized securities–based swap, but must comply with applicable securities laws.
The Statement adopts a merit- and technology-neutral tone, stating that the format in which a security is issued, or whether holders are recorded on a centralized or decentralized ledger, does not affect the application of federal securities law. It emphasizes that “regardless of its format, the Securities Act requires that every offer and sale of a security must be registered with the Commission unless an exemption from registration is available.”[7] The Statement deftly opens the door for issuers to tokenize their securities, aiming to establish fair competition between centralized and decentralized ledgers and to reduce regulatory arbitrage opportunities by applying a substance-over-form approach to federal securities law, thereby fostering an environment where market forces can determine outcomes.
The Statement is silent on the interplay between market intermediaries and tokenization and blockchain technology. Theoretically, the Statement provides an avenue for an issuer to issue its securities through a direct listing as a DNT, such that transferring the DNT results in a title transfer recorded on the selected blockchain. In this admittedly oversimplified hypothetical, market intermediaries are removed from the market infrastructure as much as possible, establishing a close nexus between the buyer and the seller of the securities involved in the transaction.
Applying the substance-over-form principle from the Statement, presumably, in the hypothetical presented above, an issuer would need an “exchange”[8] as defined by the Securities Exchange Act to provide a marketplace that brings together purchasers and sellers of its securities. The posture of the Statement suggests that, regardless of form, a function that performs commonly known tasks of a stock exchange will be treated as such under the securities laws.
To the point, on July 22, 2026, SEC Commissioner Hester M. Peirce issued a statement, stating in part that “[m]oving activities that fall within the scope of the federal securities laws onchain, as a general matter, does not take those activities outside the scope of the laws the Commission administers.”[9] Although Peirce’s statement is not formal SEC guidance, it offers valuable insight into how the flexible-by-design federal securities laws and regulatory principles are being applied to new technological innovations such as blockchain-based vaults. Through her statement, Peirce encourages market participants whose activities fall within the securities laws to work with the SEC “to find a compliant path forward,”[10] which could lead to a series of no-action letters for various vault use cases.
The substance-over-form approach is evolving in interesting ways in the context of blockchain technology. Conventionally, the concept is used to determine whether a set of facts and circumstances warrants applying a regulatory regime. Subtly, blockchain technology is creating a scenario in which technological advancements might achieve the substance of a regulatory objective, rendering certain regulatory forms or constructs superfluous.
Illustratively, thought leaders in the space proffer that the SEC’s custody rule, operationalized through the qualified-custodian requirement, should be viewed functionally as a mechanism to advance a set of regulatory objectives—specifically, to protect client assets against misappropriation, commingling, insolvency exposure, fabricated reporting, and unchecked adviser control. As such, the rule should not favor a particular form or construct.[11] Stated differently, regardless of form, if a structure satisfies a rule’s regulatory objectives, it should be afforded the same regulatory imprimatur as its counterparts.
Entrepreneurs are developing on-chain vault applications to fulfill the core function of the custody rule promulgated under Section 206(4) of the Investment Advisers Act for tokenized securities. The SEC’s posture toward blockchain-based applications that satisfy the investor protection and prudential objectives of qualified custodians will significantly shape the competitive landscape. If the SEC extends the substance-over-form principle to assess whether a product or service meets statutory objectives and mandates regardless of form, competition between blockchain-based vault systems and traditional custodians for market share is likely to intensify. Recently, through a series of statements, no-action relief, rule proposals, and functional equivalents of a regulatory sandbox, the SEC has shown a propensity to provide pathways for decentralized systems to bring products and services to market within the current regulatory framework.
On March 18, 2026, the SEC approved the Nasdaq Stock Market LLC proposed rule change to enable the trading of securities on the exchange in tokenized form.[12] Similarly, on January 19, 2026, the New York Stock Exchange, Inc., announced that it is developing a platform for trading and on-chain settlement of tokenized securities, for which it will seek regulatory approvals. The platform will enable 24/7 operations, instant settlements, and stablecoin-based funding.[13]
Additionally, on December 17, 2025, the SEC’s Division of Trading and Markets staff issued a statement providing its views on the application of paragraph (b)(1) of Rule 15c3-3 under the Exchange Act regarding broker-dealers’ responsibilities when they are in custody of “crypto asset securities” for customers.[14] As with exchanges, if a market participant in a blockchain ecosystem meets the statutory definition of a broker-dealer, it will be subject to the securities laws; however, recent SEC directives provide an avenue for broker-dealers to engage with the technology. To the extent that tokenization and blockchain technology eliminate the need for broker-dealers, market forces will presumably phase them out.
Market Adoption
As tokenization gains momentum, market participants are working to leverage its potential benefits while managing its risks. On December 11, 2025, in a no-action letter, the SEC granted the request of the Depository Trust Company (“DTC”) to confirm that the Division of Trading and Markets staff would not recommend enforcement action for violations of applicable securities laws if its parent company, the Depository Trust and Clearing Corporation (“DTCC”), launched its pilot program for securities tokenization.[15] DTCC provides custody, clearing, and settlement services to the financial industry. In 2020, DTCC processed $2.3 quadrillion in securities; and as of 2025, DTC custodies over $100 trillion in securities.[16]
Broadly, the no-action letter provides a three-year regulatory sandbox for DTCC to launch its Pilot Tokenization Service Program. Strategically, it gives DTCC an advantage as the first major mover in the space. The program allows participants to elect to convert their securities entitlements in the Russell 1000 index and other qualified securities into a DTT[17] on preapproved blockchains and using preapproved wallets. Any transfer of a DTT would be tracked and made visible to DTC through its LedgerScan software.
The program establishes two layers for recording transactions. The primary layer functions as the definitive record of ownership and will be maintained in book-entry form. The program does not alter the ultimate custodian of record for the “subject securities” or the legal framework governing their ownership, and DTC will continue to serve as the “securities intermediary” for the subject securities in accordance with Article 8 of the Uniform Commercial Code (“UCC”). The second layer enables participants to conduct peer-to-peer transactions on preapproved blockchains without DTC executing these transactions, with all transactions eventually reconciled on the primary layer. The program enables participants to leverage the benefits of blockchain and tokenization technology without forgoing the value of a central securities depository (“CSD”) to help mitigate risks associated with the technology.
The no-action letter highlights the development models for tokenization and the interaction between decentralized ledgers and market intermediaries, such as CSDs and clearing agencies. Similarly, on August 12, 2026, the SEC staff granted no-action relief to Franklin Templeton–affiliated funds, permitting the custody of tokenized shares of certain money market funds without complying with certain provisions of Rule 17f-2, promulgated under Section 17(f) of the Investment Company Act. Importantly, the administrative controls allow transfer agents “to correct errors or unauthorized transactions, freeze or mitigate wallet records if necessary, and maintain or restore the official record of share ownership in the Integrated System.”[18] This marks another step in the SEC’s growing treatment of blockchain technology as a recordkeeping mechanism, functionally equivalent to traditional book-entry.
During these early stages of tokenization development, market participants are leveraging tokenization’s benefits while maintaining the advantages of traditional market structures to minimize risk. As blockchain technology evolves to reduce its idiosyncratic risks, as long as the regulatory framework stays flexible, market forces will help dictate the role of intermediaries in market infrastructure.
Commercial Law Implications
The law’s significance for intermediaries in the custody of tokenized assets extends beyond the securities law regulatory framework and has significant commercial law implications. CSDs dominate the custodial services market by volume and are subject to numerous laws and regulations.[19] CSDs are typically designated as “financial market utilities” and are part of a broader network of subsidiaries of “custodial banks” regulated by the Office of the Comptroller of the Currency. If a CSD provides clearing services, it also falls under Section 17A of the Exchange Act. Additionally, as securities intermediaries that custody securities, CSDs are governed by Article 8 of the UCC for commercial law purposes, which provides a comprehensive set of investor protection rules. Part 5 of Article 8 was codified in 1994 to accommodate market trends toward indirect holding of securities.[20]
Tokenization and blockchain technology will have to contend with certain foundational aspects of commercial law principles that were designed with traditional book-entry as the primary means of recording and transferring value. Stated succinctly, fundamental principles of commercial law are based on established concepts of custody, intermediaries, and recordkeeping that do not easily align with blockchain infrastructure. As blockchain technology becomes more widely adopted, how these challenges are addressed will affect tokenization’s penetration rate in financial markets.
Notably, the UCC 2022 Amendments, highlighted by Article 12, modernize the UCC to “accommodate emerging technologies, such as artificial intelligence, distributed ledger technology, and virtual currency.”[21] The revised UCC introduces a new class of electronic property, controllable electronic records, which presumably covers a broad range of digital assets. In essence, the amendments aim to provide pathways for emerging technologies, including blockchain-based custody systems, to use the UCC infrastructure—a critical pillar of commercial transactions. To date, thirty-two jurisdictions have adopted these amendments.[22] The manner in which Article 12 is implemented will be instrumental in the proliferation of tokenization.
Legislative Activities
Recent legislative activity underscores the importance of the evolving securities law regulatory regime for the development of blockchain technology and digital assets. Broadly, policymakers employ four approaches to address new technologies that enter the market and conflict with the existing regulatory or legal framework: prohibition, regulation by enforcement, ex ante nonbinding guidance and regulatory rulemaking, and legislative enactment. These approaches reflect risk tolerance, governing philosophies, and the potential impact of the new technology. Each approach has its advantages and disadvantages, ranging from facilitating innovation and minimizing uncertainty to mitigating market and prudential risks.[23]
On July 17, 2025, the House of Representatives passed the Digital Asset Market Clarity Act (“CLARITY Act”); and on July 22, 2026, Senate Republicans released their latest version of the bill. On September 15, the bill failed a procedural Senate vote to advance, significantly reducing the likelihood of comprehensive federal market-structure legislation for digital assets in the near future—and further prompting regulators to fill the gap.[24] In the absence of comprehensive legislation, the SEC is expected to continue applying the securities laws in a post-Chevron era, in which regulators can no longer rely on judicial deference to an agency’s statutory interpretation[25] to regulate blockchain technology and tokenization through interpretive releases and rulemaking.
On March 17, 2026, the SEC issued an interpretive release clarifying how federal securities law applies to certain crypto assets and transactions involving them (“2026 Interpretive Release”).[26] Among other things, the 2026 Interpretive Release provides a taxonomy that defines five categories for crypto assets: digital commodities, digital collectibles, digital tools, stablecoins, and digital securities. Except for digital or tokenized securities, the enumerated types of crypto assets are not viewed as securities in and of themselves, but they can be offered and sold as part of an investment contract, thereby making them securities under the Howey test.[27] Additionally, the 2026 Interpretive Release provides guidance on when crypto assets are no longer considered investment contracts and on the types of representations or promises that create reliance under the Howey test.
Additionally, on August 18, 2026, the SEC released its proposed rules, “Regulation Crypto Assets,” “to create a tailored offering regime for certain investment contracts involving crypto assets.”[28] Subsequently, on September 1, 2026, the SEC released its proposed modernized rules for registered transfer agents.[29] The proposed rules revisit the current regulatory framework “to reflect transfer agents’ current processes and operations, including the use of electronic communications and blockchain technology in connection with securities offerings and the transfer of shares.”[30]
Most recently, on October 1, 2026, the SEC proposed new rules and amendments for the custody of crypto assets under the Investment Advisers Act of 1940 and the Investment Company Act of 1940.[31] Among other things, the new rules provide a tailored framework and a pathway for advisers and regulated funds to self-custody crypto assets and to maintain client or regulated fund crypto assets with a state trust company. Conceptually, the proposed rules and amendments aim to modernize custody rules and adopt a substance-over-form approach to the custody rules’ objectives of protecting client assets from loss, theft, misuse, and misappropriation. In a recent statement, Chairman Paul S. Atkins emphasized that only Congress can ensure that regulations in this space establish a durable framework for blockchain technology and decentralized ledgers.[32] This underscores that interpretive releases convey the SEC’s current views and that regulatory rules are subject to change, whereas legislative actions are more enduring.
Conclusion
As tokenization gains traction, attorneys must have a keen understanding of the intersectionality of key regulatory, market, legal, and legislative issues that influence the technology’s adoption in the financial markets. They should also be familiar with the core features tokenization offers, the problems it aims to solve, its evolving technology stack, and the unique regulatory and legal challenges it faces relative to conventional systems so that they can provide value-added counsel in this rapidly evolving area of the law.
For example, the evolving legal and regulatory landscape and its impact on the programmability and composability features of tokenization, as market participants attempt to leverage developments in artificial intelligence, smart contracts, and decentralized autonomous organizations toward the technology’s use cases, will help drive tokenization’s proliferation rate. Attorneys with a thorough understanding of these issues will play an important role in helping clients navigate any discord between the current market infrastructure and the tokenization of financial assets. A holistic view and an understanding of the interplay of these issues will be an invaluable asset in helping clients meet their short- and long-term objectives.
Press Release, Div. of Corp. Fin., Div. of Inv. Mgmt. & Div. of Trading & Mkts., U.S. Sec. & Exch. Comm’n, Statement on Tokenized Securities (Jan. 28, 2026). ↑
A wrongful death lawsuit, Raine v. OpenAI, has put a once-obscure governance document at the center of artificial intelligence litigation strategy. System cards, the structured disclosures AI developers publish to describe how their systems perform, are now being used by both plaintiffs and defendants to establish what a company knew, when it knew it, and whether its safeguards were adequate. For lawyers advising companies that build or deploy AI tools, understanding how these documents create legal exposure is key in a thoughtful risk mitigation strategy.
The risks are similar, but not exactly the same, across AI developers, companies that build tools on AI platforms, and companies that use AI tools. Take this for an example: The system card for OpenAI’s GPT-5.5 model, released in April 2026, reports lower scores than the immediately preceding model for not producing disallowed outputs when the input includes an image across all four categories evaluated—hate, extremism, self-harm, and erotic harms—though OpenAI describes the differences as minor and not statistically significant. It could mean, however, that GPT-5.5 was worse at identifying content in those categories. If a deployer of AI that developed a companion app used this new ChatGPT model, there might be a valid argument that the deployer should have known the selected model was not appropriate for this use case because of the information in the system card.
System cards function primarily as evidence rather than as an independent cause of action. They can nonetheless give rise to liability where the disclosure itself is false or misleading because AI capability representations are subject to Section 5 of the Federal Trade Commission Act and, in California, to civil penalties under the Transparency in Frontier Artificial Intelligence Act enacted in 2025.
Why Companies That Integrate AI into Their Products Should Care About System Cards
System cards are published by AI providers and describe how a deployed AI system performs in real-world conditions, including intended use cases, known limitations, testing methodology, and risk mitigation measures. The term is sometimes contrasted with model cards, which address underlying models rather than deployed systems, but developers use the labels inconsistently, and a single document often blends both. Counsel should read the methodology closely rather than assume a card describes production behavior, since results are frequently generated offline and may capture only the model’s own conduct without accounting for other layers of the safety stack.
Companies that integrate third-party AI systems into their products may also face claims that they should have known about risks disclosed in a provider’s card. If those materials identify known limitations, foreseeable misuse, or safety concerns, a downstream company may be expected to account for those risks in its own product design, user disclosures, contractual controls, and usage restrictions.
System Cards in Litigation: Raine v. OpenAI
Raine v. OpenAI, No. CGC-25-628528 (Cal. Super. filed Aug. 26, 2025) arose from the suicide of a sixteen-year-old who had used ChatGPT extensively in the months before his death. His parents allege that OpenAI’s system was defective, that the risks were foreseeable, and that the company failed to implement safety measures to reduce the foreseeable harms. A subsequent amended complaint added the allegation that OpenAI deliberately removed a “suicide guardrail” from its platform, framing the claim not just as a failure to warn, but as a conscious choice to deprioritize safety. As of this writing, the case remains in pretrial proceedings.
Plaintiffs rely on OpenAI’s own system documentation to argue the company had actual knowledge of the risk. OpenAI relies on the same materials to show it conducted structured testing and implemented safeguards. Both sides treat system cards as probative of the company’s knowledge, the foreseeability of harms, and the adequacy of the company’s response. However, the question is not whether adequate disclosures were made, but whether the disclosures aligned with what the system actually did.
The FTC, SEC, and California Now Treat AI Disclosures as Enforceable Representations
The FTC has made clear, through staff guidance and enforcement, that AI capability claims are subject to the same deception standards as any other product representation.
The Securities and Exchange Commission has taken the same posture for public companies. Its Division of Examinations, in priorities released in November 2025, said it will assess whether registered companies’ AI-related disclosures, supervisory frameworks, and controls align with actual practices. Those priorities reach investment advisers, broker-dealers, and investment companies, among others, rather than issuers generally. For issuers, the analogous exposure runs through the federal securities antifraud provisions, principally Section 17(a) of the Securities Act of 1933 (15 U.S.C. § 77q(a)) and Section 10(b) of the Securities Exchange Act of 1934 (15 U.S.C. § 78j(b)) and Rule 10b-5 (17 C.F.R. § 240.10b-5), where “AI washing” has already drawn enforcement attention.
California codified the same principle with penalties. The Transparency in Frontier Artificial Intelligence Act, effective January 1, 2026, requires frontier AI developers to publish safety frameworks, disclose catastrophic risk assessments, and report critical safety incidents within fifteen days to state regulators. Civil penalties of up to $1 million per violation, enforced by the California attorney general, attach to enumerated violations.
Practical Risks for Companies
As system cards are used in litigation and enforcement, the risks they create and the actions required to manage those risks are closely related.
System card statements can function as admissions: Descriptions of known limitations or failure modes are often drafted to demonstrate responsible governance, but in litigation, those same statements become evidence that the company had actual knowledge of a specific risk before harm occurred. Every disclosure of a weakness should be accompanied by internal documentation showing how that weakness was evaluated and what was done about it.
A documented risk with no documented response is a failure-to-warn claim waiting to be filed: If a system card identifies a limitation but the company does not translate that acknowledgment into user-facing warnings, usage restrictions, or design changes, plaintiffs will argue the company knew of the hazard and chose not to address it. The Raine amended complaint makes exactly this argument regarding the removed guardrail. A documented risk with no documented response is a failure-to-warn claim waiting to be filed.
Outdated documentation creates independent exposure: AI systems change faster than the documents that describe them. A system card that no longer reflects current system behavior, particularly one that omits the removal of a previously disclosed safety feature, suggests the company stopped paying attention to its own disclosures. Companies should treat system card updates as a compliance obligation.
Inconsistency between internal testing and external statements is discoverable: System cards will be reviewed alongside internal evaluations, safety logs, and communications. Where public summaries diverge from what engineers and safety teams actually found, that gap will be central to both litigation and regulatory inquiry. Internal records should be able to support every material statement in any external disclosure.
Final Takeaways
System cards are no longer just technical transparency documents; they are becoming evidence of what companies knew about AI risks and how they responded. Companies that develop or deploy AI tools should treat these disclosures as legal and compliance documents, ensuring that public statements align with internal testing, actual system behavior, and documented mitigation steps. The greatest exposure may arise not from identifying risks, but from failing to act on them, update disclosures, or explain why a particular safeguard was sufficient. As litigation and regulatory scrutiny increase, system cards should be reviewed with the same care as other material representations about product safety, performance, and risk.
Haynes Boone, LLP 2801 N. Harwood St., Suite 2300 Dallas, TX 7520 214.651.5329 [email protected]
§ 1. Introduction
The term “business divorce” includes disputes that cause business partners/investors to end their partnership, situations that require owners to separate, or circumstances where a business partner/investor wishes to change the composition of management. This chapter provides summaries of developments related to such business divorce matters that arose from October 1, 2024, to September 30, 2025, from fourteen states.
Contributors to this chapter used their best judgment in selecting business divorce cases to summarize. We then organized the summaries, first, by subject matter, then by jurisdiction. This chapter, however, is not meant to be comprehensive.
The reader should be mindful of how any case in this chapter is cited. Some jurisdictions prohibit courts and parties from citing or relying on opinions not certified for publication. To the extent unpublished cases are summarized, the reader should always consult local rules and authority to ensure the unpublished cases can serve as relevant and permissible precedent. The reader should also be mindful that this chapter provides a “snapshot” of developments within a single year. Any development in a particular year covered by this chapter may be altered by legislation or cases in subsequent years.
We hope this chapter assists the reader in understanding recent developments in business divorces.
§ 2. Access to Books and Records
§ 2.1. Arizona
Svec v. Davis, et al., 2025 WL 2062694 (D. Ariz. July 23, 2025). This case underscored a common problem in business divorce cases that occurs when the parties form a business venture without adequate professional documentation. Here, the parties met at a pinball show and discussed forming a partnership to design, source and sell pinball products under Davis’s existing brand and company, XPin and 21 Electronics, LLC, respectively. Svec and Davis signed a “notice to serve as a letter of intent” (“LOI”) stating that for $30,000 Svec would acquire a 50% ownership interest in 21 Electronics but also contemplated the preparation of additional partnership agreements. Svec paid Davis $30,000 and the parties operated a business together for two years, but then the relationship deteriorated. The distributions to Svec decreased despite an increase in profits and, despite repeated requests, Svec was denied access to the bank accounts. Svec sued Davis under a variety of legal theories largely predicated upon Svec becoming a 50% owner of 21 Electronics via the $30,000 payment. In this context, the Court decided Svec’s motion for summary judgment on two of his causes of action: (1) the issue of his ownership of 21 Electronics under a breach of contract theory; and (2) his claim for accounting.
The primary evidence consisted of the LOI as well as a series of emails leading up to its execution. The LOI provided that it would serve as a “letter of intent” concerning the sale of “50% Member ownership of 21 Electronics” including all “inventory, assets, fixtures, intellectual property and equipment currently owned by Brett Davis, valued at $60,000, for the development of XPin-related products, for the sum total amount of $30,000” and specified that at the conclusion of the sale transaction each party would be a 50% “Member/Owner” of 21 Electronics. The LOI concluded by saying “[t]hese changes will be effective as of the date of the financial transaction on August 13, 2020 following which additional partnership agreements will be constructed and put into place.” The LOI did not say it was nonbinding or unenforceable absent the execution of subsequent documentation. Svec argued that his payment of $30,000 pursuant to the LOI was sufficient to convey to him a 50% ownership interest in 21 Electronics and that, at least for a time, Davis referred to him as a “50% partner” and granted Svec access to certain information for purposes of monitoring and assisting with product distribution and marketing. Davis argued that the LOI contemplated additional partnership agreements which were never created and that articles were never filed with the State of Arizona formalizing the partnership.
Applying Arizona’s contract interpretation standards to the dispute the Court attempted to determine the intent of the parties by looking first to the plain meaning of the words in the contract. Of importance was the principle of Arizona law that “the mere fact that an agreement contemplates the execution of another, related agreement in the future does not render the initial agreement unenforceable.” (citing T.D. Dennis Builder, Inc. v. Goff, 418 P.2d 367, 370 (Ariz. 1966)). Secondarily, the parol evidence rule in Arizona does not require contractual ambiguity but, rather, permits the Court to consider the proffered evidence and if the contract language is reasonably susceptible to an interpretation asserted by its proponent, the parol evidence may aid in determining the intent of the parties. Based on the foregoing, the Court granted summary judgment in favor of Svec on his breach of contract claim and held that both the plain language of the LOI and the ancillary email correspondence all supported the conclusion that Svec became a 50% owner of 21 Electronics at the time he conveyed the $30,000 payment.
As to the claim for an accounting, Svec argued that even if the LOI had been insufficient to convey a 50% ownership interest to him that he and Davis had formed a partnership under Arizona law sufficient to entitle him to an accounting. The Court held that pursuant to A.R.S. § 29-1012(A) “the association of two or more persons to carry on as co-owners a business for profit forms a partnership, whether or not the parties intend to form a partnership.” As a result, both A.R.S. §§ 29-1035(B) and 29-1033(B) allowed a partner to maintain an action against the partnership or another partner, including for “access to [the partnership’s] books and records.” The Court held that the fact that Svec and Davis conducted business together for over two years and shared in the profits was sufficient to create a partnership and, as a result, Svec was granted summary judgment on his claim for access to books and records to perform a full accounting for 21 Electronics.
§ 2.2. California
Perry v. Stuart, 111 Cal. App. 5th 472, 333 Cal. Rptr. 3d 472 (2025). Member brought action against LLC and its manager seeking writ of mandate to compel production and inspection of LLC’s financial records and member information. The Superior Court, Santa Clara County, granted members’ petition in part, ordering disclosure of some corporate records but requiring redaction of member names and addresses from a member list after finding that list was a trade secret. An appeal and a cross-appeal followed.
The scope of the redactions was one of the issues challenged on appeal. LLC asserted that the trial court’s redaction order was too narrow. It argued that the member names and contact information are trade secrets, whether they appear in a member list or elsewhere; thus, such information should be redacted in all the records ordered produced. Member challenged the trial court’s redaction instruction as contravening both § 17704.10, subd. (h) (stating “Any waiver of the rights provided in this section shall be unenforceable”) and their right under the terms of the operating agreement to access “all” records.
A trade secret is information, including a formula, pattern, compilation, program, device, method, technique, or process that: (1) derives independent economic value, actual or potential, from not being generally known to the public or to other persons who can obtain economic value from its disclosure or use; and (2) is the subject of efforts that are reasonable under the circumstances to maintain its secrecy. The record supported the trial court’s finding that the LLC’s member list was a trade secret, and the operating agreement did not contradict or prevent this finding. The appellate court then decided, as a matter of statutory interpretation, that the protection of the member list as a trade secret under Cal. Civil Code, § 3426.1 takes precedence over a member’s right to obtain a copy of the member list under § 17704.10, subd. (a) and 17701.13, subd. (d)(1). The trial court did not err in declining to order LLC to provide an unredacted member list under § 17704.10.
But as to the trial court’s decision to decline ordering the redaction of individual member names and addresses from other documents, there was no error. Though the member list was properly redacted as a trade secret, there was no evidence or legal authority in support of LLC’s argument that the court should also require the redaction of individual member names, addresses, and other identifying information from all other records the court ordered disclosed. By issuing its judgment without the requested additional limitations on disclosure, the trial court impliedly determined that LLC had not met its burden of proof with respect to its argument that the court should expand its redaction order. The record did not support overturning this determination on appeal.
LLC failed to identify evidence indicating that the member list is duplicated in any of the other records the court ordered LLC to disclose. LLC had not presented any cogent argument that the names and addresses appearing in documents other than the member list are not publicly known, derive independent economic value from not being generally known to the public, and are the subject of efforts that are reasonable under the circumstances to maintain their secrecy. As such, there was no error in declining to require the redaction of member names and addresses for all records ordered produced.
§ 2.3. Delaware
Cornett v. Collectable Sports Assets, LLC, 2025 WL 1531160 (Del. Ch. May 29, 2025). The Delaware Court of Chancery held that plaintiff Justin Cornett (“Cornett”), a member of Collectable Sports Assets, LLC, (the “LLC”) is entitled to inspect most of the books and records he requested from the LLC, subject to a reasonable confidentiality agreement. Cornett sought inspection to evaluate his investment and investigate possible mismanagement after the LLC underwent significant ownership and operational changes, including missed SEC filings, halted trading, and asset relocations.
While the LLC acknowledged his valuation purpose, it resisted the investigation and argued voluntary production sufficed. The Court found that the operating agreement’s inspection rights generally mirrored those in the Delaware LLC Act, except for limiting access to series-specific information only to series in which the member invests. And although the operating agreement afforded the managing member discretion over the reasonableness of a demand, that power did not override the Court’s authority to adjudicate inspection rights. The Court concluded that Cornett had a credible basis to suspect wrongdoing and granted broad inspection rights, including access to business status, financial condition, membership lists, and formal materials about key decisions, but denied his request for a narrative explanation of a former officer’s termination. The LLC’s attempt to limit Cornett’s communication with other members was rejected, as long as confidential information was not disclosed. Cornett was awarded costs, but both sides bore their own attorneys’ fees. The parties were ordered to meet and confer on logistics and confidentiality for production, with unresolved disputes to be submitted to the Court.
Garner v. Authenticity.AI Investors, LLC, 334 A.3d 1108 (Del. Ch. 2025). The Delaware Court of Chancery held that Authenticity.AI Investors, LLC (the “LLC”)—an entity formed solely to aggregate investments for purchasing stock in Authenticity.AI Corporation (the “Company”)—must produce a limited subset of books and records to plaintiff Michael B. Garner (“Garner”). The Court also rejected the bulk of Garner’s extensive demands for inspection.
In this case, Garner was one of approximately ten investors in the LLC, which acted as a “feeder entity” whose only asset is stock in the Company. Garner sought thirty categories of corporate records under the auspices of valuation and to investigate mismanagement. The Court found his investigation purpose mostly unsupported except for one issue: a discrepancy in the number of Series A Preferred Stock shares held by the LLC.
Accordingly, the Court ordered the LLC to produce (1) documents regarding the financial performance and accounting of the LLC and the Company, including quarterly and annual reports and QuickBooks records, to the extent they exist and were not previously produced; and (2) documents reflecting grants of the LLC’s equity or options to board members, officers, executives, advisors, or other individuals in the relevant period.
Chuang Wei Pan LLC v. Hiwin Holding LLC, 2025 WL 2490263 (Del. Ch. Aug. 29, 2025). The Delaware Court of Chancery held that plaintiffs Chuang Wei Pan LLC (the “LLC”) and Yaning Li (“Li”) lack standing to inspect the books and records of Hiwin Holding LLC (the “Company”) under Section 18-305, because they voluntarily withdrew from the Company and were no longer members, who are entitled to inspection rights.
The Company is a Delaware LLC formed by the LLC and WXG Funding, Inc. to invest in real estate. Based on alleged rights in the operating agreement, the plaintiffs sought inspection to investigate suspected misconduct within the Company. The Court found that the plaintiffs, beginning in August 2024, engaged in a series of actions that constituted a voluntary withdrawal by the LLC. The operating agreement defined voluntary withdrawal as requiring only an attempted dissociation, followed by appraisal and return of capital contributions. The evidence showed Li, managing member of the LLC, initiated withdrawal discussions, negotiated terms for the return of capital, and referenced withdrawal in both written and in-person communications. While Li continued to use board titles and attempted to call meetings after these communications, the Court determined these acts did not override the prior, clear withdrawal.
Accordingly, the plaintiffs lacked standing to pursue books and records inspection. But the Court found that the plaintiffs could pursue information necessary to value their capital contribution for liquidation purposes under the operating agreement.
Centerview Partners Holdings LP v. Handler, 2025 WL 1720039 (Del. Ch. June 20, 2025). The Delaware Court of Chancery dismissed all counterclaims brought by David Handler (“Handler”) against Centerview Partners Holdings LP and related entities and individuals (“Topco,” and with its subsidiaries, “Centerview”) because collateral estoppel barred Handler from relitigating issues already decided in a prior books and records proceeding.
Centerview sued Handler, a former employee, over post-employment non-compete and non-solicitation provisions. Handler counterclaimed for breach of fiduciary duty, constructive fraud, breach of contract, breach of the implied covenant of good faith and fair dealing, and unjust enrichment—all premised on the theory that Centerview unlawfully stripped him of certain contractual and common law rights that he was entitled to as a partner of Topco. Indeed, the relevant partnership agreement provided for certain payouts to departing partners, if they complied with restrictive covenants. But a prior books and records trial concluded that Handler was never made a partner, no partnership agreement was finalized with him, and his compensation after 2012 was a matter of annual negotiation and Founders’ discretion—not governed by partnership or fixed terms. As a result, the Court held that Handler’s counterclaims claims were precluded by the earlier factual finding that Handler was never a partner and never believed himself to be a partner of Topco.
Handler also challenged the scope and enforceability of the restrictive covenants that Centerview sought to enforce, arguing they were unreasonable, overbroad, and unlawful. The Court of Chancery disagreed, finding that Handler was a sophisticated party who had negotiated the agreement and benefitted from the employment. Thus, the restrictions were lawful and enforceable.
Gentile v. GPB Capital Holdings, LLC, 2024 WL 4941050 (Del. Ch. Nov. 27, 2024). The Delaware Court of Chancery ordered the indemnification of fees and expenses incurred in connection with a books and records action filed by a majority member of an LLC for purposes of obtaining books and records necessary to prepare and file tax returns on behalf of the LLC. The underlying books and records action had been successful, though the majority member never reviewed the produced documents nor prepared the tax returns. Nonetheless, the Court found that, under the LLC’s indemnification clause, which required indemnification for “any loss, damage or claim incurred” by a member “by reason of any act or omission performed or omitted by” such member “in good faith on behalf of the Company.” The Court held that, given that the books and records action had the proper purpose of preparing the company’s tax returns, the expenses incurred were properly indemnifiable under the company’s operating agreement.
§ 2.4 Texas
Collins v. Hetzler, No. 02-24-00078-CV, 2025 WL 937486 (Tex. App.—Fort Worth Mar. 27, 2025, no pet.). The court established that, beyond the duty to allow inspection of books and records for a proper purpose upon request, there is no statutory fiduciary duty for a director to send regular, formal reports to shareholders. Tex. Bus. Orgs. Code Ann. §§ 3.151–.153, 21.218.
The case arose from an appeal of a jury’s take-nothing decision in a derivative suit brought by Collins, a minority shareholder, for alleged breaches of corporate duty surrounding the corporate founder’s divorce. The court ultimately affirmed the jury’s verdict based on a finding of sufficient evidence. Collins was a former employee of the company he still maintained shares of. After his departure from the company, he requested financial information about the company six times from Hetzler, the founder, president, majority shareholder, and chairman of the company. Hetzler did not share any formal financial reports. Collins later also requested access to the company’s QuickBooks application, which Hetzler denied. Collins responded demanding profit and loss statements, income statements, cash flow statements, balance sheets, and tax filings for the previous five years. Hetzler ultimately agreed without requiring Collins to sign a nondisclosure agreement. Since its inception, the company had an informal approach to shareholder relations. Hetzler did not send regular financial statements or other communications to the shareholders. Hetzler did not distribute a formal financial overview to any shareholder for the first 25 years of operations until the company’s first shareholder meeting. However, Hetzler informally responded to requests for information, and shareholders other than Collins stated that they felt that they had sufficient access to information.
After learning the details of how the company functioned, Collins filed suit against Hetzler, the company, a subsidiary company, and a separate company that was providing consulting services. Collins specifically alleged that Hetzler had breached his fiduciary duties to the company. The court affirmed the jury’s finding that Hetzler did not fail to comply with his fiduciary duties. Specifically, as to Collin’s access to the company’s books and records, the court found that Hetzler declined Collins’s request to access the company’s financial software directly and offered general financial information instead. Four years later, when Collins responded to that email, requested specific financial information, and stated a purpose for the request, information was provided shortly thereafter at the first shareholder’s meeting. Further, multiple shareholders testified that financial reports and books and records were available upon request and that they had access to all the information they felt they needed.
Douglas Scott Sec., Inc. v. Wilkie, No. 05-23-00833-CV, 2025 WL 1270096 (Tex. App.—Dallas May 1, 2025, no pet.). The court of appeals affirmed the trial court’s straight-forward application of Tex. Bus. Orgs. Code § 152.002(b)(1), which states that a “partnership agreement or the partners may not: unreasonably restrict a partner’s or former partner’s right of access to books and records under Section 152.212.”
Wilkie, a partner in various partnerships, requested the names and contact information of his current partners from Hill Country Exploration Inc., the partnerships’ managing general partner, and from Douglas Scott Securities, Inc., which Wilkie described as a “placement agent” that facilitates investment in the energy industry. The two companies denied his request, so Wilkie filed suit seeking a judgment requiring defendants to allow him access to review, examine, and copy all books and records of the partnerships in which he was currently invested, including the names and addresses of partners in those partnerships. The trial court granted Wilkie’s motion for summary judgment.
On appeal, the Appellants/Defendants argued that (1) the motion did not address the unreasonableness standard of section 152.002(b)(1) or (2); (2) the motion did not provide evidence that the restrictions on providing partner information were unreasonable; and (3) the partnership agreement contained a provision that barred providing the requested information. The court found that (1) the motion did address the unreasonableness standard; (2) the motion contained affidavits evidencing denial of his requests that supported his motion; and (3) the aforementioned provision only restricted the transferability of partnership units and did not address accessibility of records, and, as a result, was not applicable. The court of appeals affirmed.
§ 3. Business Judgment Rule
§ 3.1. California
Tuli v. Specialty Surgical Cntr. of Thousand Oaks, LLC, 105 Cal. App. 5th 997, 326 Cal. Rptr. 3d 357 (2024). Randhir Tuli is not a medical doctor, but he was a founding member of a surgery business. Founder contributed to the enterprise, then lapsed into inactivity. He did nothing productive but took millions from LLC profits. The surgeon members sought to buy him out, but founder refused to surrender his interests. Then founder set a letter to a wide swath of recipients, including potential investors that speciously suggested the specter of criminal liability for all involved in the LLC. The LLC members warned founder they would eject him without compensation, as was their right under the operating agreement, unless he cured the situation within 30 days.
The operating agreement had a “terminating event” provision that was designed to ensure “bad actors” within the company did not damage it. A “terminating event” would occur if a member disrupts the affairs of the LLC or has acted adversely to the best interests of the LLC, as determined in the reasonable discretion of the LLC’s “Governing Board” and fails to cure such conduct within thirty (30) days after receiving written notice of a terminating event from the governing board. The consequence of an uncured terminating event was the loss of the offending member’s interests in the LLC for $0.
Here, founder took no action to cure his terminating event. The other members acquired founder’s membership interest for nothing. Founder launched a decade-long litigation campaign against his former business colleagues that resulted in a bench trial rejecting founder’s claims.
The business judgment rule was a significant issue on appeal. This rule is a presumption that the member of an LLC makes business decisions on an informed basis, in good faith, and in the honest belief that the action taken was in the best interests of the company. Courts defer to board judgments that can be attributed to any rational business purpose. The trial court ruled the business judgment rule insulated LLC and its decisionmakers from founder’s claim they breached their fiduciary duty to him. The court found LLC established this affirmative defense by proving its business purpose was rational. The evidence supported LLC’s rational fear that founder’s letter would scare off potential investors, that it was rational to notify founder his letter was a terminating event, and that it was rational to oust him when he refused to cure within 30 days. Founder contended the business judgment rule does not apply for three reasons: conflict of interest, bad faith, and improper investigation.
Founder’s logic is that each person on the governing board had an ownership interest in the LLC, and each would gain a personal advantage by voting founder out and redeeming founder’s interest for $0, because such action proportionally increased each remaining member’s ownership interests. The conflict-of-interest exception to the business judgment rule arises when the interests of the individual decisionmakers diverge from the interest of the enterprise. But the uncontested evidence was that LLC’s decisionmakers worked in the best interest of the company, so the conflict-of-interest exception did not apply.
Officers and directors are required to act in good faith to receive the protection of the business judgment rule. Founder argued that defendants exhibited animosity towards founder. They had been upset with founder for a long time, were frustrated that founder was earning high profits without bringing in business or providing services and had repeatedly and unsuccessfully tried to buy his units. But it is not bad faith to offer to buy out an unproductive member. Founder even admitted there was nothing wrong with offering to buy his shares. Nor is it bad faith to be frustrated with a member for earning profits while doing nothing.
Finally, the record showed that the LLC had adequately investigated the allegations in founder’s letter and there was no evidence provided that further investigation would have changed the results. Application of the business judgment rule was not barred due to any improper investigation. The trial court properly applied the business judgment rule and found defendants acted properly in LLC’s interests when it expelled founder pursuant to the terminating events provisions of its operating agreement.
§ 3.2. Michigan
Sparling v. Rumple, No. 369228, 2025 WL 2015946 (Mich. Ct. App. July 17, 2025). Port Builders, Inc., a family-owned corporation formed to own and manage commercial real estate, had been embroiled for years in internal disputes among the Sparling sibling shareholders over control and the disposition of its real estate assets. As part of a 2017 settlement placed on the record, Port Builders’ board was required either to complete a sale of the properties by a fixed deadline or, failing that, to install a third-party management company. After an initial sale to one buyer fell through, the trial court authorized the board to continue pursuing a sale to another third-party purchaser, Steven Ureel. The board entered into a purchase agreement representing that Port Builders held clear title and had obtained all necessary approvals. However, the transaction ultimately failed when the title company refused to issue a commitment due to ongoing litigation and lack of unanimous shareholder consent. As a result, the corporation paid damages to the prospective buyer. Plaintiffs then sued the defendant directors individually to recover those amounts, alleging breach of fiduciary duty under Mich. Comp. Laws § 450.1541a. They claimed the directors made misrepresentations in the purchase agreement concerning title, authority, and consents, which resulted in the corporation’s liability to pay the prospective buyer damages. The trial court granted summary disposition in favor of the directors, finding they had acted in good faith, with due care, and in the corporation’s best interests and their decisions were protected by the business judgment rule.
The Michigan Court of Appeals affirmed, holding that there was no genuine issue of material fact. The directors had reasonably relied on court orders, advice of counsel, and prior sale efforts when entering into the agreement with Ureel. Although the sale ultimately failed and the trial court’s sale order was later reversed on appeal, the appellate court emphasized that directors are not liable for reasonable decisions made in good faith under existing judicial authority. It stressed that the directors’ conduct must be evaluated based on the information available at the time, not in hindsight. The record demonstrated that the board entered into the purchase agreement only after years of court involvement, multiple court orders authorizing continued sale efforts, and consultation with counsel regarding how to proceed after the initial sale failed. These circumstances supported application of the business judgment rule and negated any inference of reckless or dishonest conduct.
The Michigan Court of Appeals also rejected plaintiffs’ argument that the directors’ representations regarding title, authority, and consents created a triable issue of breach of fiduciary duty. The evidence supported the conclusion that the directors reasonably believed they had authority to proceed with the sale based on the court orders and the corporation’s sale history. The failure to obtain title insurance or unanimous shareholder consent reflected legal uncertainty rather than bad faith or intentional misrepresentation. The appellate court further observed that plaintiffs presented no evidence showing that the directors ignored contrary legal advice, concealed material facts, or acted for personal gain. In the absence of such evidence, the directors’ reliance on court orders, counsel’s advice, and prior sale efforts shielded them from liability.
§ 3.3. Texas
Martin v. Hutchison, No. 06-24-00018-CV, 2025 WL 876812 (Tex. App.—Texarkana Mar. 21, 2025, pet. denied). The court of appeals affirmed the trial court’s denial of a motion to disregard the verdict after reviewing a director’s fiduciary duties under the business judgment rule. The business judgment rule is a presumption that, in making a business decision, the directors of a corporation acted on an informed basis, in good faith, and in the honest belief that the action taken was in the best interests of the company and its shareholders. Moody v. Nat’l W. Life Ins. Co., 634 S.W.3d 256, 274 (Tex. App.—Houston [1st Dist.] 2021, no pet.).
Plaintiffs, minority shareholders in Network Operator Services, Inc. (NOS), alleged that Defendants, corporate directors, violated their fiduciary duty to the corporation when they transferred corporate assets—ownership interest in a second corporation—to themselves, without approval from or notice to the corporation. The jury found that Defendants did not violate their fiduciary duty in this regard, and the trial court denied Plaintiffs’ motion to disregard the jury verdict. The court of appeals affirmed the denial based on a finding that the evidence was sufficient to support the jury’s verdict.
On appeal, Plaintiffs/Appellants specifically argued that there was no valid agreement that justified Defendants/Appellees transfer of a corporate asset to themselves. Defendants/Appellees contended that the majority directors of NOS agreed in 1998 to equalize ownership in future-formed companies amongst themselves and that this transfer was in line with that agreement. Each of the Defendants/Appellees testified that the principal shareholders in NOS orally agreed to equalize interests in new companies formed after NOS, and without the agreement to equalize, they would have gone on without including the initial investors, to the detriment of NOS. As a result, the court of appeals concluded that a reasonable jury could have determined that Defendants/Appellees did not breach their fiduciary duties to the corporation.
§ 4. Dissolution/Disassociation/Explusion
§ 4.1. Arizona
Furst v. Mayne, et al., 2025 WL 314371 (Ariz. Ct. App. Jan. 28, 2025) (unpublished). Mayne appealed the trial court’s judgment in favor of Frost on claims involving partnership dissolution, accounting and enforcement of negotiable instruments. The Court of Appeals affirmed the trial court’s judgment. The parties formed Investor Clout as a partnership to invest in commercial real estate mortgages through Mortgages Ltd. The partnership agreement specified that “cash flow from the partnership shall be distributed to the partners in proportion to their respective contributions” and profits and losses shall be allocated accordingly. Mortgages Ltd collapsed and a bankruptcy agent oversaw subsequent bankruptcy distributions. Investor Clout received distributions totaling approximately $1.5 million of its original $1.8 million investment. The parties disagreed, however, about how Investor Clout should receive and distribute the proceeds and, as a result, could not send joint instructions to the bankruptcy agent regarding the distributions. Furst filed the action alleging claims for declaratory and equitable relief, dissolution of Investor Clout and breach of fiduciary duty as against Mayne. After a four-day bench trial the trial court granted judicial dissolution and a winding up of Investor Clout because the action itself demonstrated that it was not reasonably practicable to carry on the partnership and Mayne’s conduct had frustrated its purpose. The trial court also held that the distributions must be divided based on ownership interest in Investor Clout. Mayne appealed and the Arizona Court of Appeals affirmed.
In doing so, the Court of Appeals held that “A partnership may be dissolved through judicial dissolution if ‘[t]he economic purpose of the partnership is frustrated,’ A.R.S. § 29-1071(5)(a), or ‘[i]t is not otherwise reasonably practicable to carry on the partnership business,’ A.R.S. § 29-1071(5)(c). . . . During the winding up of a partnership, ‘the assets of the partnership . . . shall be applied to discharge its obligations to creditors . . . Any surplus shall be applied to pay in cash the net amount distributable to partners in accordance with their right to distributions.’ A.R.S. § 29-1077(A).” Further, when granting a dissolution, the superior court may “make such orders as it deems advisable to effectuate the speedy winding up of the partnership affairs” (citing Wood v. Holiday Mobile Home Resorts, Inc., 128 Ariz. 274, 284 (App. 1980)). The Court rejected Mayne’s argument that her consent was required for a judicial resolution. The Court held that judicial dissolution without a partner’s consent is permissible and affirmed the trial court (citing Imperial Litho/Graphics v. M.J. Enters., 152 Ariz. 68, 76 (App. 1986) (finding partner “was entitled to seek judicial dissolution of the partnership for cause,” despite the partnership agreement only contemplating “voluntary dissolution upon agreement of all partners.”)).
§ 4.2. Colorado
Hogue v. Hogue, 565 P.3d 1123, 2025 COA 5 (2025). Plaintiff general partner in a family limited liability limited partnership that owned ranch property brought action seeking judicial dissolution of the partnership and a winding up of its assets. Following a bench trial, the court entered orders dissolving and liquidating the assets of the partnership. Defendant partner appealed.
Defendant partners argued that the trial court should have considered partitioning the ranch property instead of liquidating the assets. But everyone agreed that this was not a partition action. The partners had no property interests in the ranch property itself because it belonged entirely to the partnership. The partners only had interests in the partnership. As a result, none of the partners could have requested a partition of the property under C.R.S. § 38-28-101 because none of them was a “person having an interest in” the property at issue.
C.R.S. § 7-62-802 of the Colorado Uniform Limited Partnership Act of 1981 (“ULPA”) provides that the district court, “[o]n application by or for a partner, . . . may decree dissolution of a limited partnership whenever it is not reasonably practicable to carry on the business in conformity with the partnership agreement.” If the district court finds that dissolution is appropriate, it may wind up the limited partnership’s affairs upon application of any partner.
The ULPA does not define “reasonably practicable.” As such, the appellate court adopted principles and precedent applied to LLC dissolutions, including the factors detailed in Gagne v. Gagne, 2014 COA 127 (“Gagne I”) to determine whether it was reasonably practicable to carry on the partnership in this case. The factors include, but are not limited to:
(1) whether the management of the entity is unable or unwilling reasonably to permit or promote the purposes for which the company was formed; (2) whether a member or manager has engaged in misconduct; (3) whether the members have clearly reached an inability to work with one another to pursue the company’s goals; (4) whether there is deadlock between the members; (5) whether the operating agreement provides a means of navigating around any such deadlock; (6) whether, due to the company’s financial position, there is still a business to operate; and (7) whether continuing the company is financially feasible.
The trial court was deemed to have properly applied the Gagne I factors in support of its decision to dissolve the partnership and order the liquidation of its assets.
§ 4.3. Delaware
In re Coral Gables Luxury Holdings, 2025 WL 1356027 (Del. Ch. May 9, 2025). In In re Coral Gables Luxury Holdings, the Delaware Chancery Court granted summary judgment appointing a liquidating trustee for Coral Gables Luxury Holdings, LLC and resolving a deadlock between its two 50/50 members: Shoma Coral Gables LLC (“Shoma”) and Gables Investment Holdings (“GIH”).
In this case, the company’s only asset, a Florida property, was sold under court order and sale proceeds were held in escrow pending resolution of ongoing litigation between Shoma and GIH. The sale triggered the dissolution of the Company under the LLC Agreement, which required the appointment of a trustee to wind up affairs. GIH refused to cooperate in the process, prompting Shoma to file suit in Delaware seeking the appointment of a trustee and attorneys’ fees. GIH responded that Shoma’s claim (1) was barred by laches due to delay; (2) that appointing a trustee was futile because distributions needed mutual consent or a final court order; and (3) that Delaware proceedings should be stayed pending the related Florida litigation.
The Court rejected all defenses, noting that (1) GIH’s own actions perpetuated delay and could not be used to avoid judicial intervention; (2) the need for a liquidating trustee was based on the LLC Agreement and Section 18-803 of the Delaware LLC Act, not the Escrow Agreement; and (3) the Florida litigation did not eliminate the necessity for a trustee. Judicial intervention was warranted under Delaware law due to the members’ unresolvable deadlock. The Court ordered the appointment of a liquidating trustee to oversee the wind-up process and dismissed GIH’s other objections, emphasizing that the LLC Agreement’s dissolution provisions governed and that ongoing litigation elsewhere did not negate the need for proper dissolution procedures in Delaware.
PXP Producing Co. LLC v. MitEnergy Upstream LLC, 342 A.3d 402 (Del. Ch. 2025). The Delaware Court of Chancery denied PXP Producing Company LLC’s (“PXP”) request to appoint a receiver for the cancelled entity MitEnergy Upstream LLC (the “Company”), finding that PXP failed to show good cause or provide enough specific facts to justify such an appointment.
In this case, PXP sought indemnification for oil well decommissioning costs, arguing that the Company improperly failed to reserve funds for known obligations before cancellation in 2019, as required by Delaware law. PXP also requested a receiver to investigate undistributed assets and pursue veil-piercing claims. MEPUS Holdings LLC (“MEPUS”), an entity connected to former members, moved to dismiss the petition for a receiver, claiming the suit was untimely. The Court rejected the argument, stating only the canceled company or its legal successors could assert it. But the Court ultimately denied PXP’s petition for a receiver because its allegations were speculative and unsupported by concrete facts, especially regarding possible leftover assets or improper structure. Late arguments about cash on hand at cancellation were disregarded. The Court concluded that PXP failed to establish a sufficient factual basis for appointing a receiver.
PJT Holdings, LLC v. Costanzo, 339 A.3d 1231 (Del. Ch. 2025). The Delaware Court of Chancery upheld the expulsion of investor PJT Holdings, LLC (“PJT”), controlled by Peter Trematerra (“Trematerra”), from PBM Group Holdings, LLC (the “Company”), after finding that PJT’s principal willfully breached the LLC Agreement by refusing to fund the company and unilaterally terminating a key lease—actions that justified removal under the operating agreement’s expulsion provision. This decision affirmed the authority of the “sweat-equity” Founders (Daniel Costanzo, Benjamin Costanzo, and Brian Fitzpatrick), who contributed operational expertise and intellectual property to the member-managed Delaware LLC, to enforce governance protections designed to safeguard the business against a disruptive member.
The LLC Agreement provided (1) a 50% interest to Trematerra (through PJT); (2) certain deadlock-breaking rights; and (3) that a member could be removed for willful breach, gross negligence, fraud, or materially wrongful conduct by a unanimous vote of the other members. After a series of disputes—including Trematerra’s repeated refusals to make required capital contributions unless the Founders agreed to restructure the business in his favor and his unilateral cancellation of a key restaurant lease—the Founders invoked the expulsion provision and removed Trematerra from the Company.
Trematerra sued to invalidate his expulsion and claimed breach of the LLC Agreement. The Founders counterclaimed, arguing they had multiple valid grounds for expulsion under the Agreement. The Court found that the Founders proved at trial that Trematerra had willfully breached the LLC Agreement by repudiating his obligation to fund the Company and by unilaterally terminating the lease, both of which justified expulsion. As a result, the Founders were entitled to indemnification from Trematerra for their litigation expenses as provided by the LLC Agreement.
Holzbaur v. Trolley Square Hospitality, LLC, 343 A.3d 603 (Del. Ch. 2025). The Delaware Court of Chancery ruled in favor of the defendants, finding that the plaintiff was validly removed as a noncash contributing member of Trolley Square Hospitality, LLC and is owed no further distributions, clarifying the power of the manager to remove “sweat equity” members under the LLC agreement.
This dispute arose after the plaintiff, recruited as general manager and granted a 14% membership interest described as “sweat equity,” was removed by the managing member following his resignation. The LLC agreement distinguished between cash contributing members—who could not be removed by the manager and retained ongoing rights—and noncash contributing members, who could be removed and would lose their distributions. The plaintiff claimed he was a cash contributing member, citing conflicting provisions and an exhibit that appeared to list a cash contribution.
Finding the agreement ambiguous, the Court examined extrinsic evidence, including pre-formation negotiations and the parties’ conduct, to determine the parties’ intent. The evidence showed only certain members made actual cash contributions—not including the plaintiff, whose interest was based solely on his labor and management efforts. The LLC agreement’s reference to a symbolic cash amount did not reflect a real contribution. The Court declined to apply contra proferentem because the agreement resulted from mutual negotiation, not one-sided drafting.
Based on these findings, the Court held that the plaintiff was a noncash contributing member, making his removal and cessation of distributions proper under the agreement. Judgment was entered for the defendants, with costs shifted in accordance with Court of Chancery Rule 54(d).
Lundgren v. Brola, 2025 WL 2325499 (Del. Ch. Aug. 13, 2025). The Delaware Court of Chancery held that judicial dissolution under 8 Del. C. § 273 was unavailable because Plaintiff Christopher Lundgren (“Lundgren”) failed to prove that Credit Glory Inc. (the “Company”) was a joint venture between himself and Alex Brola (“Brola”) Brola—clarifying that Section 273 applies only when two equal shareholders are true co-venturers in a jointly controlled enterprise.
Credit Glory Inc. was founded in 2016 Brola and others, with Lundgren joining later as a marketing employee and receiving equity as compensation. Following another founder’s departure, Lundgren’s equity stake was increased to match Brola’s, and Lundgren took on expanded duties, the title of Chief Marketing Officer, and a board seat. In 2022, Brola terminated Lundgren for alleged misconduct, and Lundgren petitioned for dissolution and a receiver, arguing that he and Brola were deadlocked co-owners in a joint venture.
At trial, Lundgren argued that he and Brola were equal shareholders in a joint venture and deadlocked on the future of the corporation. Brola countered that Lundgren was never intended to be a co-venturer or partner, and that Lundgren’s equity grant was simply compensation for his role as an employee. In evaluating the parties’ arguments, the Court focused on Section 273’s statutory requirements, including that judicial dissolution is available only where a corporation has two 50% stockholders “engaged in the prosecution of a joint venture” and unable to agree on discontinuing the venture or disposing of its assets. Vice Chancellor Will noted that joint ventures require a voluntary agreement to pursue a common purpose with joint control, proprietary interest, and a duty to share profits and losses. The Court, however, found no evidence of a voluntary agreement between Lundgren and Brola to jointly pursue a business with shared control, risks, and profits. Instead, Lundgren’s equity was granted as employee compensation, not as a sign of partnership or co-venturer status. Equal ownership resulted from happenstance, not a joint venture arrangement, and Lundgren was never allowed an equal voice in major decisions.
Without proof of a joint venture relationship, the Court concluded that statutory dissolution was unavailable and entered judgment for Brola, leaving the company intact.
§ 4.4. Florida
Chimouni on behalf of E.E.R. Holdings, LLC v. Victory Avenir, LLC, 410 So.3d 593 (Fla. Dist. Ct. App. 2025). The Florida Fourth District Court of Appeal affirmed a final judgment dissolving E.E.R. Holdings, LLC, (“E.E.R.”) a real estate investment company jointly owned by Dan Chimouni (“Dan”) and Elodie Chimouni (“Elodie”). The parties’ dispute arose from a breakdown in the business relationship between Dan and Elodie, who formed E.E.R. to acquire and manage twenty rental properties. During their falling out, Dan withdrew all funds from E.E.R.’s account and cut off Elodie’s access, and Elodie responded by transferring twelve of E.E.R.’s properties to an entity she alone controlled. Dan, acting on behalf of E.E.R., sued Elodie and her company for breach of fiduciary duty and judicial dissolution of E.E.R.
At trial, a central issue was the admission of E.E.R.’s 2017–2020 tax returns, which contained information about the company’s ownership structure, capital accounts, and financial history—evidence critical for determining how to divide E.E.R’s assets. Dan objected, arguing that the returns were inadmissible hearsay and did not qualify as business records under Florida law (section 90.803(6)) because the necessary foundation for business records had not been laid. The appellate court agreed that the tax returns were not “records of a regularly conducted business activity” within the meaning of the statute, so the business records exception did not apply.
The Court of Appeal, however, found a valid alternative basis for admitting the tax returns: as party admissions under section 90.803(18). The Court reasoned that Dan—acting as E.E.R.’s tax representative—had reviewed and authorized the filing, thereby adopting their contents. Applying the “tipsy coachman doctrine,” the Court explained it could affirm a trial court’s decision if there was any valid legal basis in the record, even if the trial court relied on the wrong reason.
The appellate court concluded that the trial judge properly admitted the tax returns as party admissions and that the evidence supported dissolution and an equal division of E.E.R.’s assets.
§ 4.5. Pennsylvania
Hayes v. Goring, 2025 WL 2953794 (Pa. Super. Ct.). In Hayes v. Goring, the Pennsylvania Superior Court considered whether Hayes, the husband in a domestic divorce proceeding, had disassociated from a limited liability company owned with his ex-wife Goring. The Court noted there are a myriad of ways that a member can become disassociated from an LLC under the Uniform Limited Liability Company Act (“ULLCA”) as adopted in Pennsylvania. See 15 Pa.C.S.A. § 8861 of the ULLCA. Importantly, “[a] person is dissociated as a member when . . . [t]he [LLC] knows or has notice of the person’s express will to withdraw as a member, except that, if the person specified a withdrawal date later than the date the company knew or had notice, on that later date.” Id. at §8861(1). The Court further noted that “[a] person has the power to dissociate as a member [of an LLC] at any time, rightfully or wrongfully, by withdrawing as a member by express will under [sub]section 8861(1)[.]” Id. at § 8862(a) (emphasis added). The Court concluded that the “quality and quantum of evidence necessary to prove a member’s ‘express will’ to dissociate from a Pennsylvania LLC” was an issue of first impression in Pennsylvania. Ultimately, the Court found that the trial court did not abuse its discretion in finding no “magic words” were required to disassociate and that Hayes had expressed a desire to disassociate in various text messages with his ex-wife containing statements that he didn’t want anything, that she did not owe him anything, and that he would not accept anything. Based on the timing of the messages, the Court found that Hayes was due to share in member profits only through early 2017.
§ 5. Jurisdiction, Venue, and Standing
§ 5.1. California
Bigfoot Ventures Ltd. v. Knighton, 132 F.4th 1138 (9th Cir. 2025). Shareholder, Bigfoot Ventures Ltd. (“Bigfoot”), brought a derivative action on behalf of the corporation, NextEngine, Inc. (“NextEngine”), alleging breach of fiduciary duty, abuse of control, corporate waste, and unjust enrichment against: NextEngine’s CEO, founder and largest shareholder—Mark Knighton; his related entity, ShapeTools, LLC (“ShapeTools”); and NextEngine itself. The trial court granted defendants’ motion to dismiss for lack of subject matter jurisdiction based on Bigfoot’s inability to fairly or adequately represent the interest of NextEngine’s shareholders, which is required by Federal Rule of Civil Procedure 23.1 (“FRCP 23.1”). Shareholder appealed.
Since 2008, Bigfoot initiated and pursued a campaign of multiple cases against NextEngine. As such, Defendants argued that Bigfoot cannot fairly or adequately represent the interests of NextEngine’s shareholders. Several shareholders submitted declarations that objected to Bigfoot’s derivative action. These shareholders did not believe that Bigfoot could competently and fairly represent their interests as NextEngine shareholders because of Bigfoot’s litigation campaign against NextEngine. These shareholders asserted that Bigfoot’s misconduct damages their property rights. Using the multi-factor test in Larson v. Dumke, 900 F.2d 1363 (9th Cir. 1990), the trial court agreed and dismissed the derivative action.
Under Larson, an adequate FRCP 23.1 representative must have the capacity to vigorously and conscientiously prosecute a derivative suit and be free from economic interests that are antagonistic to the interests of the class. Larson set out eight factors to consider when determining adequacy of representation in shareholder derivative actions: (1) indications that the plaintiff is not the true party in interest; (2) the plaintiff’s unfamiliarity with the litigation and unwillingness to learn about the suit; (3) the degree of control exercised by the attorneys over the litigation; (4) the degree of support received by the plaintiff from other shareholders; (5) the lack of any personal commitment to the action on the part of the representative plaintiff; (6) the remedy sought by plaintiff in the derivative action; (7) the relative magnitude of plaintiff’s personal interests as compared to his interest in the derivative action itself; and (8) plaintiff’s vindictiveness toward the defendants. These factors are intertwined or interrelated, and it is frequently a combination of factors which leads a court to conclude that the plaintiff does not fulfill the requirements of FRCP 23.1. A court need not assess each one of the Larson factors when determining plaintiff adequacy. The Larson factor test is not exhaustive. Courts can consider whatever other factors help them to assess whether a plaintiff does not fairly and adequately represent the interests of shareholders or members who are similarly situated in enforcing the right of the corporation or association.
The Ninth Circuit ruled that the district court did not err in considering the ongoing litigation between Bigfoot and NextEngine as disqualifying outside entanglements. Such entanglements may make it likely that the interests of the other stockholders will be disregarded in the management of the suit. Bigfoot or its affiliates have been in multiple litigated disputes against NextEngine since 2008 concerning its investments in NextEngine. Because of its consistently contentious nature, Bigfoot and its affiliates’ lawsuits against NextEngine were properly deemed significant outside entanglements, making it probable that the interests of NextEngine’s stockholders will be disregarded in the management of the derivative action. The court noted that the derivative action appears to be leverage in Bigfoot’s other lawsuits against NextEngine, which weighs heavily against plaintiff’s adequacy to advance the corporation’s interests on behalf of shareholders in a derivative action. After also considering the declarations of other shareholders, the 9th Circuit held that this derivative action cannot be maintained because Bigfoot does not fairly and adequately represent the interests of NextEngine’s shareholders.
Bigfoot might have been the true party in interest but as a separate entity and not as a NextEngine shareholder. The lengthy history of litigation further supported the district court’s finding that Bigfoot was vindictive toward NextEngine and Knighton, which also weighs against finding that a plaintiff could adequately represent the interests of corporate shareholders in a derivative action. The plaintiff lacked standing. Dismissal was affirmed.
EpicentRxrix, Inc. v. Superior Court of San Diego County, 18 Cal. 5th 58, 334 Cal. Rptr. 3d 702 (2025). In this matter, a corporation, its controlling stockholder, and various associated individuals were sued by the corporation’s minority stockholder for breach of contract, fraudulent concealment, and other claims. Defendants moved to dismiss the lawsuit on the ground of forum non conveniens, relying on the corporation’s certificate of incorporation and bylaws, which contain mandatory forum selection clauses requiring most stockholder lawsuits against the corporation and related individuals to be brought in the Delaware Court of Chancery. The trial court denied defendants’ motion, and the Court of Appeal denied a petition for writ of mandate challenging the trial court’s order. Both courts held that the forum selection clauses were unenforceable. The lower courts reasoned that, if plaintiff’s claims were litigated in California, plaintiff would have a right to a jury trial, but the Delaware Court of Chancery does not recognize a similar right. In their view, because the forum selection clauses would effectively deprive plaintiff of its right to a jury trial, like a pre-dispute jury trial waiver, enforcement of the clauses would be contrary to California public policy. The California Supreme Court disagreed.
Although California has a strong public policy, based on the California Constitution, in favor of the right to trial by jury, this strong public policy protects the jury trial right in California courts, not elsewhere. California does not have a strong public policy against forum selection clauses or agreements to litigate in a jurisdiction that does not recognize the same civil jury trial right. When litigation proceeds in another forum, the jury trial right the parties enjoy in California courts does not travel with them. Instead, matters of procedure are governed by the law of the forum, including the right to trial by jury. The law of the forum determines whether an issue of fact shall be tried by the court or by a jury. The California Constitution and related statutory provisions do not reflect any public policy regarding the right to a civil jury trial in other forums. Consequently, a forum selection clause is not unenforceable simply because it requires the parties to litigate in a jurisdiction that does not afford civil litigants the same right to trial by jury as litigants in California courts enjoy.
Because the Court of Appeal found the lack of a right to a jury trial in the Delaware Court of Chancery dispositive, it did not consider plaintiff’s other arguments against enforcement of the forum selection clause, such as the manner of its adoption as part of the corporation’s certificate of incorporation and bylaws. The court therefore reversed the judgment of the Court of Appeal and remanded for further proceedings in that court.
§ 5.2. Delaware
Blue Pointer Gesture, LLC, 2112 Group LLC, and Rush Equipment II, LLC, v. Schrade, 2025 WL 3232620 (Del. Ch. Nov. 19, 2025). The Delaware Court of Chancery stayed a contract dispute between plaintiffs Blue Pointer Gesture, LLC (the “LLC”), 2112 Group LLC (“2112 Group”), Rush Equipment II, LLC (“Rush Equipment”), and defendant Samuel Schrade (“Schrade”), pending the outcome of a parallel, earlier-filed lawsuit in Texas. The plaintiffs brought this Delaware action to remove Samuel Schrade as a member of 2112 Group LLC for alleged breaches of the 2112 Group’s operating agreement. Plaintiffs also sought specific performance, compelling Schrade to transfer certain assets pursuant to a related Asset Purchase Agreement.
LLC owns 60% of 2112 Group, which wholly owns Rush Equipment. Schrade is a minority member of 2112 Group and contributed business equipment to the company as his capital investment. All parties are bound by an operating agreement (“Operating Agreement”), and Schrade and the plaintiffs are also parties to a related asset purchase agreement (“APA”) for the transfer of business assets.
Schrade moved to dismiss or stay the Delaware case, arguing that the forum selection clause in the Operating Agreement allowed litigation in Texas, and the Texas action involved the same parties and issues. Plaintiffs countered that Delaware had a unique interest in resolving governance disputes involving Delaware LLCs.
The Court found that the Operating Agreement’s forum selection clause was only partially exclusive, permitting suit in either Delaware or Texas. Applying the “first-filed” rule, the Court determined that the Texas action—filed months before the Delaware case—raised substantially the same claims and parties, and that the Texas court could grant complete relief, including issues of member removal. To avoid duplicative litigation and the risk of inconsistent rulings, the Delaware action was stayed. The Court instructed the parties to provide regular updates on the status of the Texas proceedings and allowed the Delaware case to resume only if the Texas court declines to address a member’s removal from the Delaware LLC.
§ 5.3. Minnesota
Warren v. ACOVA, Inc., 21 N.W.3d 218 (Minn. Ct. App. 2025), review granted (July 15, 2025). In this case, a beneficiary of several family trusts filed a lawsuit against her family members and the closely held family business asserting claims of unfairly prejudicial conduct and breach of fiduciary duty. The district court partially dismissed these claims on the grounds they were derivative following a special litigation committee investigation, and it found for plaintiff on her claims of unfairly prejudicial conduct on the basis of the defendants’ voluntary redemption of shareholders other than plaintiff. All parties appealed the decision.
On appeal, the court addressed whether a beneficiary of trusts owning shares of a closely held business satisfied the statutory standing requirements under Minn. Stat. § 302A.751 to assert a shareholder oppression claim since the beneficial owner is not the “shareholder” The statute requires that a “shareholder” bring the statutory oppression action, but the plaintiff in this case brought the action only in her capacity as a beneficial owner. “Shareholder” is defined by the statute as “a person registered on the books or records of a corporation or its transfer agent or registrar as owner of the whole or fractional shares of the corporation.” The parties to the suit disagreed over whether the definition of shareholder includes a beneficial owner. The court held that it does not, thus bringing suit as a beneficial owner is insufficient to establish shareholder standing. This legal issue is being reviewed by the Minnesota Supreme Court.
§ 5.4. Missouri
Delphi Mgmt. Solutions, Inc. v. Bearden, 717 S.W.3d 315 (Mo. Ct. App. May 27, 2025). Delphi, a minority owner and manager of several Missouri-licensed marijuana dispensaries, filed suit against Heya Retail, the majority owner, asserting claims including breach of operating and management agreements, fiduciary duty, and quantum meruit. While the lawsuit was pending, Delphi entered into an agreement granting AJO MO, LLC and Hi-Rise, LLC an option to purchase 95% of its interests in the dispensaries. Although these entities were later named third-party defendants in an interpleader action, they were not parties to the core claims between Delphi and Heya. Delphi and Heya ultimately settled their dispute and submitted a consent judgment to the trial court. AJO and Hi-Rise opposed the judgment and moved to intervene, claiming the settlement affected their rights under the option agreement. The trial court denied the motion to intervene and entered the consent judgment.
On appeal, the Missouri Court of Appeals dismissed the challenge to the consent judgment, holding that the option holders, AJO and Hi-Rise, lacked standing to appeal and were not “aggrieved” parties because the judgment only resolved issues between Delphi and Heya and did not involve or affect the option agreement, which had not been exercised. The Court of Appeals emphasized that under Missouri law, an unexercised option does not create a legally enforceable interest. Because AJO and Hi-Rise were not parties to the operative agreements or claims resolved in the judgment, they lacked standing to appeal. It also affirmed the trial court’s denial of the motion to intervene, noting that even if the court had jurisdiction, AJO and Hi-Rise failed to preserve a record for review. They did not provide affidavits or verified pleadings, nor did they ensure a transcript of the hearing was prepared. The Court of Appeals found the record insufficient to evaluate their claims and therefore upheld the trial court’s ruling.
§ 5.5. Pennsylvania
Linde v. Linde Enterprises, Inc., 339 A.3d 379 (Pa. Super. Ct. 2025). This case is the third lawsuit between two brothers Scott and Eric Linde over a construction company started by their father, Linde Enterprises, Inc. (“LEI”) and is ultimately a cautionary tale about using an inexperienced lawyer for a complex dispute between business owners. In 1999, Eric Linde sued Scott and a sister, derivatively on behalf of LEI, for starting their own company and funneling assets of LEI to their company. That case was settled in 2014 whereby Eric was to be bought out of LEI for $2,000,000, stock in another entity and land. For reasons that are not clear in the opinion, the settlement devolved into another dispute. In 2016, Eric commenced a lawsuit against Scott for breach of contract and specific performance. Judgment was entered in favor of Eric and affirmed on appeal. In 2019, Scott sued Eric in this action for unjust enrichment, breach of fiduciary duty, fraud, and conversion, alleging that Eric devalued LEI and misappropriated assets during his tenure as President of LEI. Scott repeatedly alleged that Eric breached the agreement but neglected to include a breach of contract claim. At trial, Eric moved for nonsuit, asserting that Scott was not a proper plaintiff but, rather, that Scott’s claims were derivative in nature, belonging to LEI. Scott countered by requesting leave to amend the Amended Complaint to add LEI as a plaintiff. Ultimately, the Court denied the amendment and entered judgment for Eric. Scott appealed. This Court affirmed holding (i) that Scott’s claims were derivative in nature because they alleged harm to LEI, not direct harm to Scott, (ii) adding a derivative claim would “go[] beyond simply editing the caption” and require adding LEI as a party and reopening the evidence, which would cause unfair prejudice to Eric, and (iii) the prejudice from the timing (post-trial) and potential statute of limitations issues justified denial of the requested Amendment. (Notably, the Court did not discuss the lack of a derivative demand. This would have been a separate basis to deny the amendment because Pennsylvania does not recognize the futility doctrine.
§ 5.6. Texas
Kassam v. Dosani, No. 24-BC11A-0021, 2025 WL 1826637 (Tex. Bus. Ct. June 30, 2025). The court established that the party challenging the court’s jurisdiction based on an insufficient amount-in-controversy bears the burden of presenting evidence that the plaintiff’s pleadings do not control the amount-in-controversy inquiry because the pleadings are fraudulent or because an amount outside the jurisdictional threshold is readily established. When reviewing the plaintiff’s allegations in the petition, the court construes them liberally in favor of jurisdiction and looks to the plaintiff’s intent.
Here, Plaintiffs alleged that Defendants usurped operational control of and mismanaged the nominal defendants by, among other acts: (1) unilaterally naming themselves to executive positions; (2) forbidding access to books and records; (3) loaning and transferring large sums of money without documentation; and (4) removing valuable inventory without explanation and possibly shifting it to other entities controlled by Defendants. Plaintiffs asserted that the amount in controversy exceeded $5 million and sought not only to recover damages but also to protect the value of the rights of control of the nominal defendants, implicating the entire values of the nominal defendants. Construing the allegations liberally in favor of jurisdiction and looking to the Plaintiffs’ intent led the court to conclude that the allegations were sufficient to invoke the court’s jurisdiction.
In re Hesseltine, No. 13-25-00256-CV, 2025 WL 1819777 (Tex. App.—Corpus Christi–Edinburg July 1, 2025, no pet.). This case concerns a dispute over venue. Relators filed a petition for the judicial dissolution of Texas Throne, a limited liability company. Relators asserted that they formed the company with the Reins, but the parties’ relationship deteriorated. The Reins filed suit against relators and former employees of Texas Throne alleging various improprieties and violations of a company agreement. Relators thus requested the trial court to compel the unwinding of Texas Throne.
Relators filed an original petition in San Patricio County. The real parties filed an answer and did not specifically deny relators’ venue allegations. The relators then filed a first amended petition and asserted that, based on Texas Business Organizations Code § 11.314, mandatory venue for the suit was in San Patricio County because Texas Throne’s principal offices were located there. Ultimately, the real parties filed a motion to transfer venue from San Patricio County to Nueces County because, contrary to the relators’ assertions, Texas Throne’s principal offices were in Nueces County, not San Patricio County, and the events material to the dispute occurred in Nueces County. Without holding a hearing on the real parties’ motion to transfer venue, the trial court granted the motion and transferred the case to Nueces County. The relators then filed a petition for writ of mandamus at the court of appeals.
Relators argued that (1) the real parties waived their venue challenge because they did not file their motion to transfer venue prior to or concurrently with their first appearance in the case; and (2) the trial court abused its discretion by transferring venue without holding a hearing on the motion to transfer. The court determined that the real parties did waive their venue challenge by filing their motion to transfer on April 5, 2025, over two months after they filed their answer to the lawsuit on January 31, 2025. The court further determined that the trial court did abuse its discretion by granting the motion to transfer without notice and a hearing, and that mandamus relief is the proper remedy for this deviation from required procedure. See Henderson v. O’Neill, 797 S.W.2d 905, 905 (Tex. 1990) (orig. proceeding) (per curiam).
§ 6. Claims and Issues in Business Divorce Cases
§ 6.1. Accounting
§ 6.1.1. Michigan
Pasionek v. Pasionek, 772 F. Supp. 3d 813 (E.D. Mich. 2024). Two brothers, James and Robert, formed a partnership in 1986 to purchase and hold hunting property. Decades later, after their relationship deteriorated and one brother allegedly attempted to sell the property without the other’s consent, the parties became embroiled in litigation involving claims for breach of fiduciary duty and counterclaims for failure to make required partnership contributions. Because neither party had maintained the capital accounts or partnership accounting required by their agreement, and the partnership was no longer viable, the district court appointed an independent CPA to reconstruct the partnership’s finances. The expert was tasked with determining each partner’s relative capital contributions, including whether certain expenditures qualified as capital contributions or were instead personal expenses. The expert concluded that James had contributed $80,788 (65.3%) and Robert $42,945 (34.7%) to the partnership. Robert subsequently moved for reconsideration.
Applying the Eastern District of Michigan’s reconsideration standard, the district court determined that Robert failed to identify a material error of fact or law warranting relief. The district court found that extrinsic evidence demonstrated the parties intended the legal work performed by Robert, a lawyer, to fall within his partnership obligations and not as separately compensable services. Any remaining ambiguity was construed against Robert as the drafter of the agreement. It also rejected Robert’s objections to the treatment of legal fees, finding that the agreement barred compensation for required services unless both partners provided written consent. The district court further upheld the expert’s classification of a movable log cabin placed on the property as a personal expense rather than a capital contribution. The cabin was not affixed to the land, had been installed without James’ consent, and remained under Robert’s personal control.
Additionally, the district court rejected Robert’s claim that the expert improperly credited James for maintenance costs, clarifying that its prior order had excluded vague or unsubstantiated maintenance billings but permitted credit for documented materials actually used for property repairs. With reconsideration denied, the expert’s accounting remained in effect, resulting in a substantially larger capital account for James than Robert. The district court then ordered the parties to proceed with winding up the partnership, including an auction sale of the partnership property, with bidding credits tied to each partner’s respective capital account.
§ 6.2. Anti-SLAPP Statute
§ 6.2.1. California
Meads v. Driggers, 114 Cal. App. 5th 28, 337 Cal. Rptr. 3d 7 (2025). The issue in this appeal is whether a cross-complaint was properly dismissed pursuant to California Code of Civil Procedure § 425.16, known as the anti-SLAPP statute. “SLAPP” stands for strategic litigation against public participation, and a SLAPP suit is one that contains claims arising from the defending party’s exercise of the constitutional right to free speech or to petition the government for the redress of grievances. A SLAPP suit is subject to dismissal unless the claiming party can demonstrate there is probability it will prevail on the challenged claims.
Steven Mead and Penny Lipking-Meads (collectively, the “Meadses”) and Driggers were members of Afterburner, LLC (the “LLC”). The Meadses initiated an action against Driggers and the LLC that included a request for dissolution. Driggers and the LLC (collectively, “Driggers”) filed a cross-complaint against the Meadses for breach of contract and breach of fiduciary duty based on a provision in the operating agreement that waived a member’s right to seek judicial dissolution. The operating agreement noted that the members agreed not to take any other voluntary action that would cause the LLC to dissolve, notwithstanding any provision of the Beverly-Killea Limited Liability Company Act (the “Beverly-Killea Act”) to the contrary. Driggers claimed the Meadses breached both the operating agreement and their fiduciary duties by filing a lawsuit seeking to dissolve the LLC in violation of their agreement.
The Meadses filed a motion to strike the cross-complaint pursuant to the anti-SLAPP statute, arguing it arose out of their right to petition the government for redress of grievances. The trial court found that the cross-complaint arose out of the Meadses filing their complaint, which is an act petitioning the government and Driggers failed to prove that they have probability of prevailing on the cross-complaint. The cross-complaint was stricken. Driggers appealed.
The filing of a complaint is a protected activity under the anti-SLAPP statute—the right to petition. The Meadses engaged in protected activity when they filed their complaint against Driggers. The question then became whether the cross-complaint arose from that protected activity. The Meadses were sued precisely because of they sought judicial dissolution. But for the Meadses’ claim for judicial dissolution, there would be no basis for the cross-complaint. The cross-complaint therefore arose from the Meadses’ protected activity. As such, Code Civ. Proc., § 425.16, subd. (b)(1), shifts the burden to Driggers to show there is a probability he will prevail on his claims.
Based on the Beverly-Killea Act, an operating agreement may not vary or waive a member’s right to seek judicial dissolution. A contract that is contrary to an expressed provision of law is void and unenforceable. Since operating agreement’s waiver provision eliminates the power of a court to decree dissolution in the circumstances specified within the Beverly-Killea Act, the waiver provision is contrary to an express provision of law and is void and unenforceable. As such, Driggers could not establish a probability of prevailing on the cross-complaint. The order striking the cross-complaint was affirmed.
§ 6.3. Breach of Contract
§ 6.3.1. Delaware
AG Mobile Holdings, L.P. v. H.I.G. Mobile, L.P., 2025 WL 501088 (Del. Ch. Feb 13, 2025). The Delaware Court of Chancery granted in part and denied in part the defendants’ motion to dismiss in a dispute arising from the management of Mobileum, Inc. (“Mobileum”). Plaintiff AG Mobile Holdings, L.P. (the “L.P.”), an affiliate of Audax Management Company, LLC (“Audax”), and defendant H.I.G. Mobile, L.P. (“H.I.G.”) jointly owned Mobileum through Matrix Topco, L.P. (the “Partnership”), governed by a partnership agreement. Defendant Matrix Topco GP, LLC (“Matrix”) serves as the Partnership’s general partner, while H.I.G. Technology Partners, LLC (“HIG LLC”) is a special limited partner. The Partnership is controlled by a Board, on include both Audax and H.I.G. representatives.
The Partnership’s Board created a Special Committee consisting only of H.I.G.-appointed directors to investigate alleged accounting irregularities at Mobileum. The Special Committee’s findings led H.I.G. to file a fraud suit against Audax in another court, which caused the L.P. to bring this suit. The L.P. alleged breaches of the Partnership Agreement and other claims, arguing that its designated manager (from Audax) was improperly excluded from the Special Committee and that material information was improperly withheld.
The Court held that the Partnership Agreement clearly required that the L.P. (as Audax’s subsidiary) have a manager on every Board committee, including the Special Committee. Therefore, the L.P. breach of contract allegations were sufficient to state a claim against the individual directors who served on the Board and Special Committee. The Court, however, dismissed all claims against the entity defendants—including H.I.G., the Partnership, H.I.G. LLC., and Matrix—because the Partnership Agreement limited their liability and delegated management authority solely to the Board.
Tatum v. Fairstead Affordable LLC, 2025 WL 3011957 (Del. Ch. Oct. 27, 2025). The Delaware Court of Chancery largely ruled in favor of John Tatum (“Tatum”) and JCT Capital LLC (“JCT”) in a business dispute with the principals and entities behind Fairstead’s affordable housing fund: Fairstead Capital Management LLC (“Fairstead”). Tatum was both a member (partner) in Fairstead Affordable LLC—holding a 5.25% equity stake through JCT—and an employee, who built and led Fairstead’s lucrative tax credit business. Tatum claimed he was wrongly stripped of his equity and denied fair compensation after resigning. Fairstead’s leadership accused him of breaching his duties and misusing confidential information.
The court found that Tatum had not breached his contractual or fiduciary duties by preparing to leave and considering a new venture because he continued to work diligently for Fairstead up to his resignation and did not misuse confidential information. The court further held that Fairstead breached its agreements by (1) failing to follow the promised process for valuing and purchasing Tatum’s equity; (2) taking his equity after he rejected a lowball offer; and (3) making his exit unnecessarily difficult. Tatum received a damages award reflecting the value of his equity interests, his promised share in a prior portfolio, and compensation for interests he transferred on promises never fulfilled.
On Fairstead’s counterclaims, the court ruled that Tatum did breach his contract by downloading and retaining company documents, but found no evidence of harm or improper use, awarding Fairstead only the cost of investigating that issue. All other claims brought by Fairstead—such as breach of fiduciary duty, aiding and abetting, and tortious interference—were rejected.
Schulz Group GmbH v. Jamestown Premier Property Fund, L.P., 2025 WL 1695819 (Del. Ch. June 17, 2025). The Delaware Court of Chancery dismissed, with prejudice, a lawsuit filed by Schulz Group GmbH (“Schulz”), a German family office investor, against Jamestown Premier Property Fund, L.P. (the “Fund”) and its general partner, Jamestown Premier GP, L.P (the “General Partner”). Schulz invested $10 million in a Delaware real estate investment fund, acquiring partnership units under a subscription and partnership agreement. When the General Partner made a capital call during adverse market conditions, Schulz’s units lost value. Schulz sued, claiming the General Partner breached contractual and fiduciary duties by making the capital call at a time unfavorable to Schulz, and by failing to act in Schulz’s best interests.
The Court dismissed all claims, holding that the partnership agreement granted the General Partner broad discretion to manage the fund and make capital calls in the best interests of the fund and all limited partners collectively, not any individual investor. Moreover, Delaware law does not require a general partner to prioritize one limited partner’s interests over those of the partnership. Furthermore, the claim for unjust enrichment was foreclosed by the existence of valid contracts governing the parties’ relationship.
§ 6.3.2. Illinois
Learco Hosp., LLC v. Comacchio, 2025 IL App (1st) 250258-U. Learco Hospitality, LLC (Learco), an Illinois LLC that operated an upscale Italian restaurant in Chicago, sued its minority member and executive chef, Federico Comacchio, asserting breach-of-contract theories and statutory claims under the Limited Liability Company Act. The circuit court dismissed Learco’s third amended complaint with prejudice under section 2-615, and the appellate court affirmed because Learco did not plead actionable contractual duties or facts supporting statutory violations.
Learco was formed in 2018 with two members: Comacchio and an Italian investor entity that controlled 85%. In 2018, the parties executed a lawyer-drafted Letter of Intent (LOI) describing Comacchio’s duties, including taking actions to open the restaurant, providing reports, hiring staff, obtaining permits, purchasing supplies, and ensuring economic results under an attached business plan, though no plan was attached. The LOI also contained a noncompetition clause that, if the restaurant did not open by June 30, 2019, extended the noncompete obligation only through December 31, 2019. Multiple operating agreements were drafted, and the operative operating agreement was signed on January 11, 2020. It defined “Letter of Intent” and incorporated the LOI into the parties’ relationship. The agreement contained an integration clause stating that the operating agreement and LOI reflected all agreements between the parties concerning the company and superseded prior agreements. In the final operating agreement, the LOI controlled in the event of any conflict. The restaurant opened on June 26, 2021. Comacchio resigned in October 2023, effective November 20, 2023.
Learco’s third amended complaint asserted four counts. Count I alleged breach of a separate oral promise made in 2017 to use “sound business practices” in managing the business. Count II alleged breach of the implied covenant of good faith and fair dealing based on Comacchio’s alleged inattention and poor performance. Count III alleged breach of an implied contract term that he would follow “sound business practices.” Count IV alleged LLC Act violations, including competing with the company, personal enrichment at Learco’s expense, and breach of a fiduciary duty of care. Learco’s pleading catalogued more than twenty performance complaints, including failure to monitor email inquiries and vendor payment requests, inconsistent reporting, failure to follow protocols, mishandling of vendor payments and accounting, inadequate scheduling and labor cost control, menu and inventory mismanagement, marketing delays, and strained vendor and PR relationships. Learco framed these as contract breaches and statutory violations.
The appellate court affirmed dismissal of Count I because any alleged 2017 oral agreement was superseded by the integrated written agreements. The integration clause broadly displaced prior agreements concerning the company, and Comacchio’s managerial obligations were tied to his executive chef role. The court rejected Learco’s argument that performance standards were outside the operating agreement’s scope, emphasizing that the operating agreement incorporated the LOI, which described duties, and the parties never executed the referenced separate employment agreement. Count II failed because Illinois law treats the implied covenant of good faith and fair dealing as a construction aid for ambiguous contractual provisions or discretionary performance, not an independent source of new duties. Learco did not identify an ambiguous contract term requiring interpretation and, instead, attempted to use the covenant to impose specific performance obligations not contained in the contract. Count III failed because Learco offered no basis to imply a new contract term requiring “sound business practices” when the written agreements defined the parties’ rights and obligations. The court declined to add implied terms, noting the presumption that parties include intended duties in their contracts. Count IV failed because the operating agreement and incorporated LOI displaced the statutory noncompete duty in a clear and unambiguous way by defining the parties’ agreed noncompete period, which expired on December 31, 2019, long before the alleged competitive conduct. Learco’s remaining statutory allegations were conclusory, including the claim that Comacchio personally benefitted at Learco’s expense, and did not satisfy Illinois fact pleading. The duty-of-care claim also failed because the LLC Act limits the duty of care to refraining from gross negligence, reckless conduct, intentional misconduct, or knowing legal violations, and Learco’s allegations described, at most, poor performance rather than conduct meeting that heightened standard. The appellate court therefore affirmed the dismissal in full.
§ 6.3.3. Michigan
Kircher v. Boyne USA, Inc., __N.W.3d__, 2025 WL 938147 (Mich. Mar. 27, 2025). Plaintiff sued Boyne USA, Inc., a ski business founded by her late father, along with her brother, Stephen, the company’s majority shareholder and CEO, and others, alleging breach of a 2014 settlement agreement entered after she was terminated from the family business in 2012. Under that agreement, plaintiff released her claims in exchange for the right to redeem her shares pursuant to a formula tied to company earnings and debt. The parties later executed a second settlement agreement in 2019 to resolve a separate lawsuit. That agreement fixed redemption prices for plaintiff’s shares for the years 2015 through 2018 based on the 2014 formula but listed the redemption price for 2019 as “to be determined” because it depended on the company’s 2018 financial statements, which were not yet finalized. The parties therefore agreed that the redemption value of plaintiff’s 2019 shares would again be calculated under the same formula set forth in the 2014 agreement that incorporated the company’s earnings and debt. In 2018, the company incurred approximately $300 million in new debt to acquire resort assets, which caused the formula to yield a negative redemption price for plaintiff’s 2019 shares.
After discovering the negative redemption price, plaintiff sued, alleging that defendants breached the 2014 settlement agreement and acted in bad faith by refusing to use an alternative method to calculate the redemption price. The trial court denied defendants’ motion for summary disposition under Mich. Ct. R. 2.116(C)(8) (i.e., motion to dismiss), and the Michigan Court of Appeals affirmed. Relying on the implied covenant of good faith and fair dealing, the Court of Appeals concluded that plaintiff had stated a cognizable breach of contract claim, reasoning that the 2014 agreement’s “unless otherwise agreed by the Parties” language permitted the parties to depart from the formula and supported plaintiff’s allegation that defendants acted in bad faith by declining to do so with respect to the 2019 redemption price.
The Michigan Supreme Court reversed, in part, denied leave to appeal, in part, and remanded for further proceedings, holding that the Court of Appeals erred by concluding that plaintiff stated a valid claim for breach of contract based on defendants’ refusal to negotiate an alternative redemption formula. The Michigan Supreme Court reaffirmed that under Michigan law the implied covenant of good faith and fair dealing is not an independent cause of action and cannot override or replace express contractual terms. Rather, the covenant applies only as an interpretive aid where a contract grants one party discretion in performance. Here, the agreement did not vest discretion in either party regarding calculating the redemption price of plaintiff’s shares. Instead, the parties expressly agreed to a specific formula that unambiguously tied the redemption price, including the “TBD” redemption price of plaintiff’s 2019 shares, to the corporation’s EBIDTA and debt. As such, defendants had no contractual duty to negotiate an alternative formula, and the Court of Appeals erred by holding that defendants were contractually obligated to use a different formula under the implied covenant of good faith and fair dealing. The Court also held that the phrase “unless otherwise agreed by the Parties” imposed no discretionary duty or obligation to depart from the agreed-upon redemption formula. Instead, the language simply recognized the parties’ ability to mutually amend the contract in the future, and absent such a modification, the existing contractual terms governed.
§ 6.3.4. Missouri
Niemeier v. Williams, 707 S.W.3d 779 (Mo. Ct. App. Dec. 24, 2024). Niemeier sued Williams and Green Peak Capital Partners, LLC, claiming Williams promised him a 50% ownership stake in Green Peak in exchange for helping acquire a target company. Niemeier assisted with the acquisition, but no formal ownership documents were executed, and Williams later offered only an employment agreement. At trial, a jury found in favor of Niemeier on both his breach of contract and fraudulent misrepresentation claims, awarding him damages and, additionally, the trial court granted specific performance, ordering that Niemeier receive a 50% ownership interest in Green Peak. Defendants moved for a directed verdict and judgment notwithstanding the verdict, which the trial court denied.
On appeal, the Missouri Court of Appeals reversed the breach of contract and specific performance rulings, holding that no enforceable agreement existed due to missing material terms and ongoing negotiations. However, the court affirmed the fraud verdict, finding sufficient evidence that Williams knowingly misrepresented his intent to grant ownership and that Niemeier reasonably relied on that promise. It also vacated the contract-based damages award to avoid duplicative recovery.
Oliver & Co. v. Zamber, No. 4:24-cv-00635, 2025 WL 1580288 (E.D. Mo. June 4, 2025). Oliver and Company sued its former employee Dr. Louis Zamber for breach of contract, tortious interference, and breach of fiduciary duty, alleging that he violated restrictive covenants after leaving the company by diverting business opportunities, disclosing confidential information, and competing with its veterinary services business. After a bench trial, the trial court entered judgment in favor of Zamber on all claims, finding that Oliver and Company failed to prove enforceable restrictive covenants because the agreements were either not properly executed or lacked consideration. The court also determined that there was insufficient evidence to support claims that Zamber disclosed confidential information or wrongfully solicited clients or employees. On the fiduciary duty claim, the court found no breach because Zamber’s actions occurred after his employment ended, and any pre-departure conduct was not shown to be disloyal or harmful to the company.
The Missouri Court of Appeals affirmed. The Court of Appeals agreed that the restrictive covenants were unenforceable, as the agreements either lacked signatures, were signed only by Zamber but not the company, or were executed after the employment relationship had already begun, thus lacking independent consideration. It also agreed that Oliver and Company failed to prove the elements of tortious interference or breach of fiduciary duty, particularly because Zamber had ceased employment by the time he engaged in the allegedly wrongful conduct. The Court of Appeals emphasized that the trial court’s credibility determinations and factual findings were supported by the record and declined to disturb them.
§ 6.3.5. Texas
S. Methodist Univ. v. S. Cent. Jurisdictional Conference of the United Methodist Church, 716 S.W.3d 475 (Tex. 2025). This case arises out of a dispute between the Southern Methodist University (SMU) and the South Central Jurisdictional Conference of the United Methodist Church (the “Conference”), a nonmember of SMU. Until recently, SMU’s articles of incorporation consistently reflected that the university was “owned” and “controlled” by the Conference and that the Conference’s approval was required to amend those articles. However, in 2019, SMU’s board of directors, without the Conference’s approval, amended SMU’s articles of incorporation to delete all references to the Conference as well as provisions detailing the board’s composition and election. After SMU filed the amended articles with the Texas Secretary of State, the Conference sued. The Conference sought a declaration that the 2019 amendments were void, and they asserted claims for breach of contract and filing a materially false instrument with the secretary of state.
The court held that the Conference had the authority to sue SMU to enforce its rights under the articles and the Texas Business Organizations Code and that the Conference may pursue, at least at this stage, its breach-of-contract claim as a third-party beneficiary of SMU’s articles of incorporation. However, the court found that SMU was entitled to summary judgment on the false-filing claim.
Specific to the Conference’s breach of contract claim, the court addressed what constituted the underlying contract. SMU’s articles of incorporation are not a contract between SMU and the Conference because a nonmember, nonprofit corporation is formed to benefit the public. However, a nonprofit corporation’s articles do constitute a contract between SMU and the State of Texas. A third-party beneficiary to a contract that expressly grants contractual rights to the beneficiary has the right to sue. Here, the Conference is a third-party beneficiary to the articles of incorporation because the articles repeatedly single out the Conference and expressly articulate precise powers the Conference may wield. The court concluded that the Conference could pursue a breach-of-contract claim in its capacity as a third-party beneficiary and affirmed the court of appeals remand to the trial court for further proceedings on this claim.
§ 6.4. Breach of Fiduciary Duty
§ 6.4.1. Arizona
Barsanti v. DeLoach et al., 2025 WL 563466 (D. Ariz. February 20, 2025). Plaintiffs are three individuals (Barsanti, Lawhorn and Vargas) who formed a solar panel installation business with two individual Defendants (Butterfield and DeLoach). Lawhorn accused Defendants of fraudulently securing solar panel financing and, in response, Defendants purportedly removed Lawhorn as a member and manager. Plaintiffs sought a temporary restraining order that would, in effect, reinstate Lawhorn as a member-manager, prohibit Defendants from unilaterally making operating decisions, and require all member-managers to unanimously agree to any proposed spending.
Plaintiffs argued that Defendants had breached their fiduciary duties by withdrawing and dissociating Lawhorn without first acquiring a judicial determination of wrongdoing or providing notice. The Court held that Plaintiffs were unlikely to succeed on the merits of this aspect of their fiduciary duty claim because the Operating Agreement contemplated an involuntary withdrawal of a member without a judicial determination of wrongdoing and, also, the Operating Agreement only required a valuation and payment for the disassociated members interest if one of the other remaining members elected to purchase it. This was not contrary to the Arizona Limited Liability Company Act. The Act contemplates that disassociation terminates the right to participate as a member in the management and conduct of the business but does not necessarily terminate ownership rights—and thus payment was not required.
Plaintiffs also argued that Defendants’ hiring of relatives for unnecessary positions and spending corporate funds for personal use breached fiduciary duties to Plaintiffs. Defendants did not dispute this alleged conduct. The Court, however, found that this undisputed conduct did not create a likelihood of irreparable harm sufficient to support the requested injunction. The Court held that Plaintiffs “have provided only minimal evidence” that the company might be driven out of business by this conduct such that the economic harm they feared could be deemed irreparable and, on this basis, denied Plaintiffs’ request for an injunction.
§ 6.4.2. Delaware
Leo Investments Hong Kong Ltd., 342 A.3d 1166 (Del. Ch. 2025). Here, the Court of Chancery held that the defendants acted reasonably and did not engage in any breaches of fiduciary duty that caused harm to the plaintiff. Plaintiff Leo Investments Hong Kong Limited (“Leo Group”), a Hong Kong-based, indirect subsidiary of a Chinese public company, invested $50 million, as a limited partner in Tomales Bay Capital Anduril III, L.P. (the “Fund”), a Delaware limited partnership formed to acquire SpaceX shares. Tomales Bay Capital Anduril III GP, LLC was the Fund’s General Partner, and Iqbaljit Kahlon (“Kahlon”) was that entity’s managing member.
As part of the deal, Leo Group negotiated a side letter allowing it to publicly disclose its investment in SpaceX, which was required under Chinese regulations. After Leo Group made its required disclosure, the news attracted significant Chinese media coverage. SpaceX objected to the publicity, fearing it could jeopardize its government contracts, and told Kahlon that the Fund would not be allowed to buy SpaceX shares if Leo Group remained an investor. In response, Kahlon invoked a “Forced Withdrawal” provision in the limited partnership agreement to remove Leo Group from the Fund and return its capital contribution.
Leo Group sued the Fund, the General Partner, and Kahlon, arguing that the forced withdrawal was a breach of contract and fiduciary duty. The Court held that, under the terms of the limited partnership agreement, the General Partner had the authority to remove Leo Group when its continued participation posed a material adverse effect or significant delay to the Fund’s activities. The Court found that Kahlon acted reasonably and in the best interests of the Fund and its partners when it removed Leo Group. The Court also clarified that the General Partner and Kahlon owed fiduciary duties to the Fund and its partners as a whole—not to individual limited partners like Leo Group—when exercising the withdrawal provision.
Vice Chancellor Laster, however, did find that Kahlon breached his duty of candor by not fully disclosing to Leo Group the real reasons for its removal during their communications. Because this breach did not cause Leo Group any meaningful harm, the Court awarded only nominal damages of $1 for this claim.
§ 6.4.3. Florida
Kajaine Capital, Inc. v. Abouzeid, 396 So.3d 582 (Fla. Dist. Ct. App. 2024). The Florida Fourth District Court of Appeal held that while Diana Abouzeid (the “Widow”) was entitled to damages for breach of contract in a failed real estate joint venture, she could not recover separate damages for breach of fiduciary duty based on the same conduct—a significant clarification preventing double recovery for a single injury.
This case arose from a joint venture between the Widow and companies controlled by Anand Patel (“Patel”)—Kajaine Capital, Inc. (“Kajaine”) and Worth Avenue Capital II, LLC (“Worth Avenue”), both controlled by (collectively with Kajaine and Worth Avenue, the “Defendants”). Widow and Kajaine each owned 50% of Worth Avenue, with Kajaine as managing member. Their agreement required Worth Avenue to secure a $4.3 million mortgage, pay off existing debts, pay the Widow $300,000, invest at least $500,000 in property renovations, and split any sale profits equally.
After the property sold for less than expected and the Widow did not receive the share she anticipated, she sued Kajaine, Worth Avenue, and Patel (collectively, “Defendants”), claiming breach of contract and breach of fiduciary duty based on allegations including the failure to spend the agreed-upon $500,000 on renovations. At trial, the jury found that Patel did not breach any fiduciary duty but held Kajaine and Worth Avenue liable for both breach of contract and breach of fiduciary duty, awarding the Widow $946,258.25 for breach of contract and $50,000 for breach of fiduciary duty.
On appeal, the Court of Appeal affirmed the breach of contract judgment but reversed the $50,000 fiduciary duty award, holding that the Widow did not present evidence of separate damages for breach of fiduciary duty apart from those for breach of contract. The Court explained that a plaintiff cannot recover twice for the same injury simply because the same conduct supports two legal theories.
Shah v. Patel, 419 So.3d 646 (Fla. Dist. Ct. App. 2025). Here, the Florida Fourth District Court of Appeal held that Sanjay Patel breached his fiduciary duty to two hotel-operating LLCs—Deerfield Hotel One, LLC (“Deerfield One”) and Deerfield Hotel Two, LLC (“Deerfield Two”) (collectively the “LLCs”)—by using a forged management agreement to convert company loans into unapproved management fees, and reversed the lower court’s failure to award damages.
The LLCs were jointly owned by Hiren Shah and Piyush Shah (the “Shahs”), Dr. Umesh Patel (“Umesh”), and Sanjay Patel (“Sanjay”) to renovate, operate, and manage two hotels. The Shahs, as minority members of the LLCs, brought derivative claims against both Sanjay and Umesh alleging that each, while serving as manager, breached fiduciary duties owed to the LLCs. They accuse Sanjay of causing the LLCs to loan company funds to his wife and related entities, including Freeport Marina Hotels (over $1.1 million) (the “Freeport Loan”). And Sanjay allegedly forged Umesh’s signature on a backdated management agreement, using that contract to reclassify the previously outstanding loans as management fees owed—at a rate the Shahs never approved—thereby reducing company assets and creating unapproved liabilities. These alleged actions depleted company assets and created improper liabilities.
The trial court dismissed all claims against Umesh, finding he had no substantive involvement in business operations or the disputed transactions. As for Sanjay, although the court determined he had forged the agreement and breached his fiduciary duty, it found no competent evidence of damages, noting the Shahs were aware of the loans and believing the balances had been eliminated.
On appeal, the Fourth District Court of Appeal affirmed the dismissal of claims against Umesh but found error in the judgment for Sanjay. The Appellate Court held that Sanjay’s actions resulted in financial harm to the LLCs. The Shahs had presented credible evidence of the damages, including the outstanding balance on the Freeport loan, and the trial court failed to compare the LLCs’ financial positions before and after Sanjay’s actions. The appellate court emphasized that managers cannot use forged documents to retroactively justify personal enrichment at the expense of the company.
§ 6.4.4. Illinois
Bosco v. Bosco, 2025 IL App (1st) 231181-U, appeal denied, No. 131701, 2025 WL 2720354 (Ill. Sep. 24, 2025). This case arose from a long-running dispute between two brothers, Robert and Joseph Bosco, who each owned 50% of Lombard Auto Exchange, Inc., a closely held used-car dealership. Robert served as president, while Joseph served as vice president, secretary, and treasurer. Their relationship was contentious for years, particularly over business operations, finances, and the possibility of one brother buying out the other.
In 2014, Robert sued Joseph and Lombard Auto, asserting claims for an accounting, breach of fiduciary duty, unjust enrichment, and shareholder oppression. Joseph and Lombard Auto counterclaimed for breach of fiduciary duty, shareholder oppression, breach of contract, and unjust enrichment. After a bench trial, the circuit court found that neither side proved any of their claims by a preponderance of the evidence and entered judgment for the defendants on Robert’s claims and for Robert on the counterclaims. The appellate court affirmed the judgment in full, concluding that the trial court’s findings were not against the manifest weight of the evidence and that no legal error occurred.
The evidence showed that the brothers divided responsibilities informally. Joseph focused on retail operations, property management, and banking relationships, while Robert handled wholesale vehicle sales and certain administrative tasks. There were no written bylaws or agreements governing work hours, expense reimbursements, or repayment of shareholder loans. Both brothers routinely used corporate credit cards for personal expenses with the understanding that matters would later be reconciled, though no reconciliation ever occurred. A central dispute concerned Joseph’s 2009 purchase of a warehouse with his own funds to address Lombard Auto’s parking and storage needs. Lombard Auto used the warehouse for years without a lease, while Joseph spent more than $100,000 of corporate funds to improve it. Robert knew of and acquiesced in the arrangement for years before objecting in 2014. Other disputes involved Robert’s temporary repayment of his shareholder loan, his refusal to renew a corporate line of credit, and his use of a separate Lombard Auto bank account for wholesale transactions.
On appeal, Joseph argued that the trial court’s rejection of his claims for breach of fiduciary duty, shareholder oppression, breach of contract, and unjust enrichment or quantum meruit was against the manifest weight of the evidence. The appellate court disagreed, holding that the evidence supported the trial court’s findings that Lombard Auto was not harmed, that the brothers’ conduct was consistent with their longstanding informal practices, and that Joseph failed to prove damages or inequitable conduct. The court emphasized that poor or debatable business decisions in a closely held corporation are borne by the corporation absent fraud, illegality, or conflicts of interest.
Robert cross-appealed, arguing that the trial court improperly applied the business judgment rule because Joseph had not pleaded it and that the denial of Robert’s fiduciary-duty claim was against the manifest weight of the evidence. The appellate court rejected both arguments. It held that the business judgment rule is not an affirmative or special defense that must be pleaded, but a rebuttable presumption arising as a matter of law. It further held that the evidence supported the trial court’s conclusion that Joseph’s conduct regarding the warehouse did not constitute a breach of fiduciary duty and, at most, reflected a bad business decision from which Lombard Auto benefitted.
Davis v. Scheck, 2025 IL App (3d) 240444-U, appeal denied, No. 131806, 2025 WL 2717957 (Ill. Sep. 24, 2025). Scheck Lumber Company (SLC) is a closely held family corporation. Plaintiff Anne Davis owns 49% of the shares through a trust, while her brothers, Tim and Kevin Scheck, collectively own 51% and control corporate decisions. Davis sued her brothers, alleging they breached fiduciary duties and engaged in minority shareholder oppression by paying themselves excessive compensation, limiting dividends to pass through tax distributions, and freezing her out of any meaningful economic return on her ownership interest. The dispute followed extensive prior litigation. In a Cook County action resolved after a bench trial in 2013, the trial court rejected similar claims by Davis and her predecessor, finding that Tim and Kevin’s compensation had been approved or ratified, was not excessive, complied with corporate formalities, and did not constitute a gross abuse of power or a freeze out. After that case, Tim and Kevin continued to vote their combined majority together on compensation and other governance matters, over Davis’s objections. In 2023, Davis filed a new action in Du Page County asserting individual and derivative claims for breach of fiduciary duty and shareholder oppression under section 12.56 of the Business Corporation Act. Her theory again centered on alleged excessive compensation that supposedly deprived her of any return on her minority interest. The trial court dismissed the original complaint and an amended complaint for failure to plead sufficient facts, granting leave to replead each time. Davis then filed a second amended complaint alleging that Tim and Kevin’s compensation was excessive, unreasonable, and disconnected from SLC’s profitability, and that they acted together to freeze her out by refusing to pay dividends beyond tax distributions. The trial court dismissed the second amended complaint with prejudice under section 2-615, noting that Davis had been given multiple opportunities to plead facts and acknowledged she could allege nothing further.
On appeal, the appellate court affirmed. Applying de novo review, the court held that Illinois is a fact pleading jurisdiction and that conclusory labels such as “excessive” or “unreasonable” compensation are insufficient. To plead excessive compensation, a plaintiff must allege facts addressing recognized factors such as the officers’ services, responsibilities, time devoted, company profitability, financial condition, and comparable market compensation. Davis pleaded none of those facts and did not allege revenues, profits, retained earnings, compensation benchmarks, or dishonesty in approving compensation. As to oppression, the court held that majority shareholders exercising their voting power, without more, does not constitute a freeze out. Davis did not allege denial of director rights, lack of meetings or notice, violations of bylaws, concealment of information, or other conduct typically associated with shareholder oppression. She alleged only that her objections were outvoted. Because Davis failed to plead nonconclusory facts supporting excessive compensation, waste, or oppressive conduct, she could not state claims for breach of fiduciary duty or relief under section 12.56. Given her repeated failure to cure the defects and her concession that no additional facts could be alleged, the appellate court affirmed the dismissal with prejudice.
Sianis v. Sayeed, 2024 IL App (1st) 231312-U. Plaintiffs George Sianis and Spyridon Theodorakis were minority shareholders of Vital Home & Healthcare, Inc. (Vital), an Illinois corporation providing home healthcare services. Defendant Asif Sayeed was Vital’s president and controlling shareholder. Plaintiffs sued Sayeed alleging multiple breaches of fiduciary duty, including dilution of their ownership interests, usurpation of corporate opportunities, and self-dealing through improper loans from Vital to entities owned by Sayeed, his wife, or his relatives. After plaintiffs sold 90% of Vital to a holding company owned by Sayeed in 1997, plaintiffs retained a combined 10% interest and ceased involvement in Vital’s operations. In 2000, Sayeed became Vital’s president and exercised full control. In 2003, Sayeed claimed he made a substantial capital contribution to Vital and demanded reimbursement from plaintiffs or, alternatively, issued himself over 235,000 additional shares, which drastically diluted plaintiffs’ ownership. At trial, Sayeed admitted Vital was profitable at the time and that he did not personally make the claimed capital contribution. Plaintiffs also alleged Sayeed usurped Vital’s corporate opportunities. First, after Vital ceased Indiana operations in 2012, Sayeed personally acquired an Indiana home healthcare company, Advanced Home Health Care, Inc., without offering the opportunity to Vital, even though it operated in the same line of business and used overlapping personnel. Second, Sayeed purchased office property in Tinley Park without informing Vital, relocated Vital there, charged above-market rent without an appraisal, and shared the space with other entities he or his family owned, generating substantial personal rental income. Additionally, plaintiffs alleged Sayeed caused Vital to make undocumented, interest-free loans to his affiliated entities without board authorization. A forensic accountant testified that Vital’s records were unreliable, the loans lacked documentation, collateral, or repayment, and at least $1.2 million remained outstanding, with additional unexplained discrepancies suggesting even greater losses.
The litigation followed a complex procedural history, including voluntary dismissals, a prior appeal, and remand. After remand, plaintiffs filed a fourth amended complaint reasserting previously dismissed claims. Following a bench trial, the court entered judgment for plaintiffs on claims for dilution of shares, two counts of usurpation of corporate opportunity, and breach of fiduciary duty based on self-interested loans. The court awarded damages reflecting unpaid loans, improper profits from real estate transactions, and other losses to Vital.
On appeal, Sayeed challenged appellate jurisdiction, the refiling of claims after voluntary dismissal, dismissal of his laches defense, and the trial court’s liability findings and damages calculations. The appellate court held it lacked jurisdiction to review dismissal of laches because it was not referenced in the notice of appeal and was waived. The court further held that the one-year refiling limitation in section 13-217 of the Code of Civil Procedure did not apply because the case was continued after remand, not refiled as a new action. On the merits, the appellate court affirmed. It held that the trial court’s findings of fiduciary breach, usurpation of corporate opportunities, and improper loans were not against the manifest weight of the evidence. The court emphasized that corporate fiduciaries must tender business opportunities to the corporation, even if they believe the corporation may be unable or unwilling to pursue them, and that a fiduciary who commingle corporate and personal transactions bears the burden of disentangling them. The trial court acted within its discretion in awarding monetary damages rather than imposing a constructive trust.
§ 6.4.5. Pennsylvania
In re Swarthmore Group, Inc., 667 B.R. 258 (Bankr. E.D. Pa. 2025). In In re Swarthmore Group, Inc., the United States Bankruptcy Court for the Eastern District of Pennsylvania ruled on a motion to dismiss an adversary action brought by the Chapter 7 Trustee against five defendants including Paula Mandle, a former director of Debtor The Swarthmore Group (“TSG”), alleging breach of fiduciary duty, aiding and abetting breach of fiduciary duty, avoidance of preferential and fraudulent transfers, conversion, unjust enrichment, and civil conspiracy. The claims were primarily related to TSG’s purchase of Mandle’s shares at a purchase price allegedly inflated to more than 100 times their fair market value while TSG was insolvent. The allegations were that Mandle coordinated a buyout of her shares with an alleged FMV of $9,205 for $963,941. The buyout was structured as 48 monthly payments with interest. The Court dismissed the claim for avoidance of preferential transfers under 11 U.S.C. § 547 because the payments were outside the 90-day preference period. However, the Court denied the motion in all other respects finding that, as a Director of TSG, Ms. Mandle finding that the payment of an inflated purchase price stated a claim for violation of a Director’s fiduciary duties of care and loyalty, that the transaction suggested several of the “badges of fraud” to support a voidable transaction, and that the remaining claims were adequately pled.
§ 6.4.6. Texas
Bertucci v. Watkins, 709 S.W.3d 534 (Tex. 2025). The court clarified the fiduciary duties owed by limited partners to each other. The general rule is that general partners owe each other a formal duty of loyalty and care, but limited partners generally do not owe each other fiduciary duties. The court concluded here that a minority partner’s control over the partnership’s funds did not create a fiduciary duty to the majority partner as an individual.
This case arose out of a dispute between two business partners, Bertucci, the majority partner, and Watkins, the minority partner. Watkins managed their funds (“B-W funds”) using a bank account owned by a separate partnership, Texas Community Builders, LP (TCBLP), that Watkins and his wife created for their own separate business. Watkins claimed that Bertucci knew that Watkins was comingling B-W funds, TCBLP funds, and Watkins’s personal funds. Watkins had sole authority to expend or distribute funds from that account.
When Bertucci’s health began declining, he gave his power of attorney to manage his finances to his son, Christopher. Christopher became concerned that Watkins had not properly managed or distributed B-W funds and instead had diverted substantial funds for his own personal use. Christopher asked Watkins to provide additional records regarding the TCBLP account, but Watkins refused on the ground that it was his private account. Christopher removed Watkins from his role and proceeded to sell the partnership’s projects.
An interpleader action was brought by parties holding the sale proceedings, and $4.5 million was tendered into the court’s registry. Watkins appeared and asserted claims requesting that funds be distributed to partners. Christopher also appeared and asserted individual and derivative claims against Watkins for violations of the Texas Theft Liability Act, breach of fiduciary duties, breach of the duty to account, equitable disgorgement and forfeiture, and breach of contract.
As to the breach of fiduciary duty claim, the issue on appeal was whether Watkins owed and breached his fiduciary duty to Bertucci as an individual because Watkins assumed control over the B-W funds and functioned as a general partner. Bertucci argued that Watkins’s control over the B-W funds imposed upon Watkins a fiduciary duty to use the funds in accordance with Bertucci’s authorization and created a principal-agent relationship. The court found that Bertucci delegating control over the funds to Watkins did not create an agency or fiduciary relationship, and Watkin’s role managing the funds was only in his capacity as a limited partner.
Davis v. Crawford, 700 S.W.3d 438 (Tex. App.—Eastland 2024, no pet.). Texas courts have not imposed broad-based fiduciary duties on members of a limited liability company (LLC), but, in this case, the court established that managing members of an LLC owe a fiduciary duty to non-managing members.
In 2015, Davis, Crawford, and Carson formed a business, Precision Frac, where VanMeter and Seburg worked as employees. Two years later, Davis, VanMeter, and Hillman pursued a new venture to build multiple water stations through separate entities under WLM Energy, LLC (controlled by VanMeter), with the first project near Barstow, Texas. Hillman, acting as a landman for the project, claimed his company, Dahlia Land Services, LLC, was promised a 5% interest. Litigation ensued. Relevant here, Davis and Hillman filed a suit against Defendants/Appellees Crawford, Carson, VanMeter, and Seburg, alleging that the promised 5% interest was not honored. The trial court granted Defendants/Appellees’ summary judgment motions.
In their motion for summary judgment, Appellees asserted that there was no evidence that VanMeter or any other person owed a fiduciary duty to Hillman. As such, it was incumbent on Hillman to raise a genuine issue of material fact on the existence of a fiduciary duty. Hillman argued that he, Davis, and VanMeter made plans to be partners in a company—he and VanMeter spoke on an almost daily basis, they texted frequently, and they placed confidence in each other. Hillman also attested that in exchange for his work on the project, his company, Dahlia Land, would receive 5% of all money from the business venture. The court determined that these facts supported a finding that VanMeter, the managing member of the LLC, owed a fiduciary obligation to non-managing members, Davis and Hillman, because the relationship between a managing member of an LLC and a non-managing member is similar to that of a general partner/limited partner relationship.
The court sustained Hillman’s cause of action against VanMeter but overruled it as against Crawford, Carson, and Seburg because Hillman did not submit evidence of the fiduciary duties of these parties.
§ 6.5. Declaratory/Equitable/Statutory Relief
§ 6.5.1. California
Angel Lynn Realty, Inc. v. George, 114 Cal. App. 5th 655, 337 Cal. Rptr. 3d 185 (2025). This case addresses the interplay between collateral estoppel and California Code of Civil Procedure § 187, which authorizes a trial court to amend a judgment to add additional judgment debtors on the ground that a person or entity is the alter ego of the original judgment debtor, within the context of a failed partnership between Angel Lynn Realty, Inc. (“ALR”) and Real Estate Portfolio Management, LLC (“REPM”). ALR, who became a judgment creditor against REPM for breaches of a partnership agreement and fiduciary duty, filed a motion to add one of REPM’s member, Steve George (“George”), as an additional judgment debtor to the $1 million judgment entered against REPM. The trial court denied the motion, finding it was barred by collateral estoppel because it had already decided George was not REPM’s alter ego.
ALR filed a lawsuit against REPM and George alleging causes of action for breach of a partnership agreement and breach of fiduciary duty, among others. The complaint also alleged George was the alter ego of REPM. After a bench trial, the court found REPM breached a partnership agreement and its fiduciary duties to ALR; ALR was entitled to $1 million in damages and prejudgment interest; and that ALR had not proven that George was the alter ego of REPM.
ALR’s 187 motion to add George to the judgment was based on George’s action post-judgement. After the judgment was entered, George was accused of fraudulently draining REPM of all of its assets to prevent ALR from satisfying its judgment. The trial court denied the 187 motion based on collateral estoppel, finding it had already determined George was not REPM’s alter ego and ALR was thus precluded from relitigating that issue. The appellate court disagreed.
Though collateral estoppel prevents the re-litigation of issues that have already been decided, the estoppel effect of a judgment extends only to the facts as they existed at the time of the judgment. Some issues are not static. They are not fixed and permanent in their nature. A prior ruling is, therefore, not conclusive as to such issues at some later time. This limitation, however, does not apply simply because a party claims to have discovered new evidence that would make an original claim more persuasive. Instead, the limitation is restricted to those situations in which the rights of the parties are not static but depend upon a current assessment of all the facts considering applicable law. The appellate ruled that alter ego liability is one of those issues that is not static and can change over time.
The court reversed the trial court’s ruling and remanded the matter to the trial court with instructions to decide whether ALR had proven that new, post-judgment facts and/or changed circumstances show that George is now REPM’s alter ego.
Koenig v. Centralia Ltd. Investors, 112 Cal. App. 5th 1174, 335 Cal. Rptr. 3d 112 (2025). Among other issues, this case addresses California’s partnership buyout code, Cal. Corp. Code § 15908.2. The heirs of a limited partner brought action against other partners, the partnership, and others, asserting claims for breach of partnership agreements, breach of fiduciary duty, conversion, declaratory relief, and dissolution, and asserting derivative claims on behalf of limited partnership. The complaint requested, among other relief, the appointment of a receiver and alternatively dissolution or an order compelling the partnership to purchase the heirs’ interests under § 15908.2. The Superior Court, Los Angeles County, granted the heirs’ motion to appoint receiver and denied a limited partner’s application to commence statutory buyout proceedings. Defendants appealed.
Under § 15908.02, subd. (c), “the court, upon application of the purchasing parties, . . . shall stay the . . . dissolution proceeding and shall proceed to ascertain and fix the fair market value of the partnership interests owned by the moving parties.” The word “shall” is mandatory. Nothing in the text of § 15908.02 suggests that its use of “shall” is permissive, just like the code governing the buyout proceedings for corporations. Since all of the conditions to activate § 15908.02 were satisfied the trial court should have stayed the case and initiated buyout proceedings.
Since the heirs challenged the existence of the partnership and sought dissolution, the heirs argued that the trial court was therefore permitted to allow them to litigate their expired partnership theory instead of granting the application to commence buyout proceedings. The court noted that a trial court has no discretion to deny the buyout remedy where the statutory requirements are met. The trial court therefore should have stayed the action, commenced buyout proceedings, but properly appointed a receiver.
§ 6.5.2. Delaware
Shassian v. Riverwalk Park, LLC, 2025 WL 3039285 (Fla. Dist. Ct. App. Oct. 31, 2025). The Florida Sixth District Court of Appeal reversed a summary judgment in a dispute among investors in Riverwalk Park, LLC (“Riverwalk”), a closely held company formed to acquire real estate in Tennessee. The central issue involved a $1 million “credit” claimed by Louis P. Shassian (“Shassian”), one of the company’s original investors. After Riverwalk’s formation, Shassian recruited Wayne Steidle (“Steidle”) and Mark Lass (“Lass”) to contribute $1 million each to help close the deal. The parties disagree about what Steidle and Lass received for their investment. Steidle and Lass contend their $2 million was a loan that also gave them a 25% interest in Riverwalk, while Shassian claims they each paid $500,000 for their shares, and the additional $1 million they invested was a loan to the company. In other words, Shassian believes he is entitled to a $1 million “credit” (i.e., repayment) from Riverwalk.
Riverwalk’s internal records and promissory notes were inconsistent about who was owed what, and eventually, the members voted to revoke Shassian’s $1 million credit and reallocate it to Steidle and Lass. Shassian sued for a declaration that Riverwalk still owed him the $1 million, while Steidle and Lass argued that any claim Shassian had was waived in a prior settlement agreement.
The trial court granted summary judgment against Shassian, but the appellate court found this was error. The District Court of Appeal held that genuine issues of material fact existed as to the parties’ original agreement—specifically, whether Steidle and Lass’s $2 million was structured as equity, loan, or both—and whether Shassian had knowingly and voluntarily waived his claim to the $1 million credit. Because these fact questions were crucial to the outcome and remained genuinely disputed, summary judgment was inappropriate.
Sunder Energy, LLC v. Jackson, 332 A.3d 472 (Del. 2024). The Delaware Supreme Court upheld the Court of Chancery’s refusal to enter a preliminary injunction against Sunder Energy, LLC’s (“Sunder”) co-founder and former head of sales, Tyler Jackson, enjoining him from breach the restrictive covenants contained in Sunder’s LLC Agreement, on the grounds that the covenants were overbroad, unduly restrictive and not reasonably tailored to Sunder’s needs. The Supreme Court additionally upheld the trial court’s refusal to blue-pencil the overbroad restrictive covenants despite the existence of a provision requiring a court to blue pencil the covenants if found to be unenforceable as written.
In Fall 2019, two of Sunder’s co-founders had a law firm draft an LLC agreement that included broad restrictive covenants without involving the other co-founders in the process. The operating agreement contained restrictive covenants prohibiting Jackson from: (1) engaging in competitive activities; (2) soliciting Sunder’s current and former employees and contractors; (3) engaging with Sunder’s customers; and (4) influencing Sunder stakeholders to terminate their relationship with Sunder (together, the “Restrictive Covenants”). The LLC agreement was presented to the minority members on New Year’s Eve without proper disclosures noting that the LLC agreement would alter their rights and internal governance dramatically. Nevertheless, Sunder sought to enjoin Jackson pursuant to the LLC agreement’s terms.
The Supreme Court upheld the Court of Chancery’s determination that it would be inequitable to blue pencil the restrictive covenants where the restricted party had no bargaining power, received minimal-to-no separate consideration in exchange for the restriction, and the provision was not negotiated in any substantive way. The existence of the “blue penciling” provision in the agreement further could not compel the court to rewrite the provision because doing so is an exercise of the court’s equitable powers. In this case, blue penciling would have required a wholesale reformation of the contract to which neither side agreed. Finally, the Supreme Court declined to elucidate a brightline rule delineating when it is proper for a court to blue pencil a provision, instead holding that balancing the well-known Delawarean contractarian principles against restraints on trade requires a nuance approach that does not lend itself to bright-line rules.
§ 6.5.3. Illinois
Barriga v. Ivanova, 2025 IL App (1st) 232209-U. This case arises from a business dispute between former spouses Andres Barriga and Dragana Ivanova, who continued to co-own three closely held companies after their 2022 divorce: Windy City Medical Specialists LLC, Windy City BillPro Inc., and Windy City Injury Care, Inc. Each party owned a 50% interest. The companies sold medical equipment and provided case management and related services to law firms and medical professionals. In June 2024, Barriga sued Ivanova, alleging she had started a competing business, diverted employees and customers, and fraudulently concealed her conduct. Ivanova answered and, in October 2024, filed an amended verified counterclaim alleging that Barriga had opened his own competing business, improperly closed the companies’ office, and engaged in a fraudulent scheme with an attorney to underpay customers. Ivanova sought dissolution of the jointly owned companies and monetary relief. Barriga moved to dismiss the counterclaim. In February 2025, Barriga filed a second amended complaint asserting numerous claims against Ivanova, including fraud, conspiracy, shareholder oppression, breach of fiduciary duty, breach of contract, and trade secret violations. Shortly thereafter, Barriga sent Ivanova a letter stating that he had removed her as a member of the companies, terminated her monthly distributions, removed her from the companies’ bank accounts, and denied her access to company records.
Ivanova responded by filing an emergency motion for a temporary restraining order, seeking to preserve the status quo pending further proceedings. She alleged that Barriga’s unilateral actions stripped her of her membership rights, access to financial information, and equitable distributions. After briefing and argument, the circuit court entered a temporary restraining order requiring Barriga to reinstate Ivanova as a member and to resume her monthly distributions, including payments withheld beginning in March 2025, until a preliminary injunction hearing could be held.
The trial court found that Ivanova had a clearly ascertainable right in need of protection, namely her membership interest in the companies, and that her removal posed a risk of irreparable harm without an adequate remedy at law, particularly given the difficulty of reconstructing prior revenue streams for damages. The court also found a likelihood of success on the merits based on Ivanova’s allegations of fraud and her request for dissolution. The court emphasized that it was not deciding the merits of the parties’ claims but relied heavily on the undisputed fact that Barriga had unilaterally removed Ivanova as a member while the litigation was pending. The court defined the status quo as the parties’ relationship before that removal and ordered a return to that condition.
On interlocutory appeal under Rule 307, Barriga argued that the temporary restraining order was improper because Ivanova’s counterclaim was legally deficient and because the order impermissibly remedied past conduct by requiring payment of withheld distributions. The appellate court rejected both arguments. Even assuming pleading deficiencies in the counterclaim, the trial court acted within its discretion because the order was justified by Barriga’s unilateral alteration of the parties’ ownership relationship and was aimed at preserving the last peaceable, uncontested status pending resolution of the merits. The court further held that the order was not compensatory in nature but properly restored the status quo, distinguishing cases in which injunctive relief merely addresses future conduct.
The appellate court affirmed, holding that Ivanova demonstrated a protectable right, irreparable injury, no adequate remedy at law, and a likelihood of success sufficient to support the temporary restraining order, and that the circuit court did not abuse its discretion in granting temporary injunctive relief.
O’Toole v. Gregory, 2024 IL App (5th) 231054-U. Joshua O’Toole and Raymond Gregory formed Legacy Cheer, LLC, a gymnastics facility, in June 2020 and executed an operating agreement giving each a 50% membership interest. The agreement designated O’Toole as the Operational Manager responsible for day-to-day gym operations and coaching oversight, and Gregory as the Financial Manager responsible for the company’s finances. Each member could independently make purchases up to $5,000. If they deadlocked, operational decisions defaulted to O’Toole and back-office decisions defaulted to Gregory. Their relationship deteriorated in September 2021. Buyout discussions failed, and O’Toole sued in October 2022, alleging Gregory withheld records, breached the operating agreement, made it impracticable to carry on the business, and breached duties owed to the company or members. O’Toole sought to expel Gregory. O’Toole then sought emergency injunctive relief, alleging Gregory slashed O’Toole’s compensation from an agreed $60,000 salary to $20,000, made deductions for expenses, moved the business checking account to a new bank without approval, denied O’Toole access to the new account, and restricted O’Toole’s ability to make purchases, all allegedly to pressure a forced sale of O’Toole’s interest. Gregory opposed O’Toole’s motion and sought his own temporary and preliminary injunctive relief to bar O’Toole from acting as Operational Manager. Gregory alleged O’Toole harmed the business, failed to work at the gym, and used company funds for personal expenses. Gregory also filed counterclaims and sought dissociation of O’Toole under the Limited Liability Company Act.
In August 2023, after the gym temporarily closed, Gregory filed a renewed motion for a preliminary injunction, claiming O’Toole diverted funds and interfered with operations. The dispute centered on access and control of the iClass system and other communication platforms used to schedule classes and contact families. After the office manager resigned, Gregory revoked or limited certain access permissions. O’Toole contended that the resulting inability to communicate with parents created a safety issue that required a temporary closure. The parties offered conflicting testimony about who caused the closure and who could promptly reopen the gym.
After a three-day evidentiary hearing, the circuit court granted Gregory’s requested preliminary injunction. It found Gregory showed a clear right as a 50% owner, irreparable harm from continued closure and loss of goodwill, no adequate remedy at law given ongoing expenses and obligations, and a likelihood of success. The court rejected O’Toole’s safety rationale for the closure and characterized O’Toole’s unilateral decision to shut down operations as egregious. It enjoined O’Toole from participating in the operational management of the business, allowed Gregory to run both operations and finances, and denied O’Toole’s request to appoint a trustee. The court later denied reconsideration, while clarifying that O’Toole could work at the gym only at Gregory’s discretion.
The appellate court reversed. It reiterated that the purpose of a preliminary injunction is to preserve the status quo and that courts should not decide contested facts or the merits at the preliminary stage. The status quo here was the operating agreement’s division of roles, with O’Toole running operations and Gregory running finances. By awarding Gregory full control and excluding O’Toole from management, the circuit court disrupted that status quo and effectively punished O’Toole based on disputed factual determinations. The appellate court emphasized that O’Toole proposed an alternative that would preserve the status quo while protecting the business, namely appointing a trustee to serve as an intermediary so the gym could remain open while the merits were litigated. Relying on the Limited Liability Company Act and the circuit court’s broad equitable authority in disputes where it is not reasonably practical to carry on the company’s business, the appellate court held that injunctive relief could be appropriate, but the form of relief entered was not. The circuit court abused its discretion by denying the trustee option and instead granting Gregory complete control contrary to the operating agreement. The appellate court reversed and remanded with directions to appoint a trustee to oversee operations and to reinstate the terms of the operating agreement, with reporting mechanisms to preserve the status quo pending a final decision on the merits.
§ 6.5.4. Michigan
Pero v. Edwards, No. 368897, 2025 WL 2147466 (Mich. Ct. App. July 29, 2025). The plaintiff and the individual defendants were corporate directors and shareholders of The Land Company (TLC), a corporation formed to hold real property used in operating Cedar Lodge. It operated largely informally and rarely produced a profit. Over several decades, ownership interests and shareholder loans shifted informally as shareholders died, sold their shares back to the corporation, or made internal transfers, often with minimal recordkeeping. Due to gaps in the records, several shareholder loans could not be attributed to specific shareholders. As a result, TLC’s accountant allocated shareholder debt proportionally based on ownership percentages, using financial information provided by TLC’s treasurer. Tensions escalated when disputes arose among the parties over share ownership, loan balances, and use of company property. The conflict culminated in a shareholders’ meeting held without the plaintiff, at which he was removed as president after nearly twenty years in that role and denied the opportunity to vote, including electing officers and directors. The defendants also approved a resolution to issue shares in exchange for sweat equity, a proposal the plaintiff previously opposed.
The plaintiff filed suit against the directors and other shareholders, alleging shareholder oppression under Mich. Comp. Laws § 450.1489(1). After a bench trial, the trial court found that the defendants engaged in oppression by excluding the plaintiff from the governance process, removing him from management, and reducing his ownership interest without proper participation or consent but found no cause of action on the plaintiff’s other allegations of oppression. On appeal, the plaintiff argued that the trial court misapplied the shareholder oppression standard, erred by failing to find oppression based on defendants’ failure to generate profits or make distributions, and failed to address whether the manipulation of shareholder debt owed to him constituted oppression.
The Michigan Court of Appeals held that the trial court applied the correct statutory oppression standard under Mich. Comp. Laws § 450.1489 and properly rejected the plaintiff’s oppression claim based on lack of profits or distributions, explaining that corporate directors’ duties to generate returns and issue distributions arise under fiduciary duty principles rather than the shareholder oppression statute. However, the appellate court determined that the trial court erred by failing to address whether post-litigation manipulation of shareholder debt by TLC’s treasurer constituted shareholder oppression and remanded for further proceedings. The record below showed that, although changes to loan balances between the 2020 and 2021 tax years resulted from rounding methodology rather than misconduct, TLC’s treasurer later undertook a post-suit forensic reallocation of shares and shareholder loans in the 2022 tax return based on unclear records, leaving unresolved disputes over the accuracy and fairness of those reallocations.
§ 6.5.5. Missouri
Blaylock v. Blaylock, 715 S.W.3d 206 (Mo. Ct. App. May 20, 2025). Four siblings, Thomas, Steven, Charles, and Nancy, jointly inherited a 265-acre family farm following their mother’s death. The siblings formed an informal, unwritten partnership to continue farming the property, which included crop land, pasture, timber, and the family homestead. From 2013 to 2016, Thomas was paid for his labor on the farm, while the other siblings took draws from the estate checking account without informing him. In 2016, after a breakdown in family relations, Thomas stopped receiving payments and later attempted to purchase the entire farm. When the other siblings declined, Thomas and his wife filed suit seeking partition by sale, alleging the property could not be fairly divided. Defendants counterclaimed, seeking partition in kind, dissolution of the partnership, and an accounting.
After a bench trial, the trial court ordered partition in kind, awarding Thomas the “horseshoe” tract, valued at $250,074, and granting him a $16,295 owelty to equalize value. The remaining land was awarded to the other siblings as tenants in common. The court dissolved the partnership effective June 2016, ordered an accounting, and allocated proceeds from crop sales to cover attorney fees and individual distributions. It found that both sides had unclean hands, Thomas for attempting to depress land value by restricting access to the horseshoe, and defendants for taking unauthorized draws. The trial court awarded $18,808 in attorney fees to Thomas’s counsel, to be paid from the partnership’s crop revenue, and rejected defendants’ claims of fraud, negligence, and breach of fiduciary duty. It also found that payments made to Thomas prior to 2016 were compensation, not draws.
The Missouri Court of Appeals affirmed the trial court’s judgment in full. It held that partition in kind was supported by substantial evidence, emphasizing that the horseshoe contained 40% of the farm’s most valuable crop land and that Thomas was granted an easement to access the landlocked parcel. It rejected the argument that the owelty award proved great prejudice, noting that owelty is a traditional tool in equity to balance partition values. It also upheld the attorney fee award, finding that the legal work benefited all parties and that the trial court did not abuse its discretion. The Court of Appeals further rejected claims that fees should not have been paid from partnership funds, finding no prejudice since both sides requested accounting and distribution from those proceeds. Finally, it agreed with the trial court’s determination that pre-2016 payments to Thomas constituted compensation for services rendered rather than partnership draws.
§ 6.5.6. New Jersey
Rappaport v. Pasternak, 260 N.J. 230, 332 A.3d 713, reconsideration denied, 260 N.J. 356, 333 A.3d 1211 (2025). This case involves a dispute among members of several limited liability companies (“LLCs”) known as the KBR entities. Laurence J. Rappaport, a former managing member, filed a complaint against other members after being removed from his position asserting claims for declaratory relief and seeking a remedy “other than dissolution.” The parties agreed to dismiss the complaint without prejudice according to the companies’ operating agreements and submitted the same claims to arbitration. Following hearings over fourteen days, the arbitrator found that the defendants lacked cause for terminating Rappaport as a manager and had breached the implied covenant of good faith and fair dealing. However, the arbitrator declined to reinstate Rappaport as a manager because of the “toxic” atmosphere in the KABR entities while he remained there. The arbitrator also denied Rappaport’s claims for declaratory relief, which included a claim that Rappaport was entitled to future compensation under the operating agreements. In his discretion, the arbitrator also denied “the requested $25M in carried interest.”
Rappaport then filed a second complaint in the Chancery Division, claiming he was entitled to future distributions of “carried interest,” arguing the arbitrator did not hold that he was “not a member or was dissociated as a member” of the LLCs. Defendants moved to confirm the arbitration award. The Chancery Court confirmed the arbitration awards and dismissed Rappaport’s complaint. On appeal, the Appellate Division modified the award and reversed the decision, reinstating Rappaport’s complaint and ruling that Rappaport was entitled to carried interest going forward under the operating agreements.
The Supreme Court of New Jersey granted defendants’ petition for certification, reversed the Appellate Division’s judgment, and reinstated the Chancery Division’s decision. The defendants argued that the Appellate Division misapplied the standard of deference to arbitration awards and argued that the question of carried interest was within the scope of the arbitration agreement. Further, defendants asserted that the Appellate Division’s modification of the awards affected the merits of the decision and misapplied the statute providing grounds for modification of an arbitration award.
The court held that the issue of carried interest was indeed submitted to the arbitrator, and the arbitrator did not exceed his authority in ruling on it. The court emphasized the limited scope of judicial review of arbitration awards, noting that they cannot be vacated or modified absent meeting specific statutory requirements, such as fraud or corruption by arbitrators. Furthermore, the Appellate Division’s decision remedy fundamentally affected the merits of the arbitration decision by requiring the parties to maintain a business relationship that the arbitrator called “toxic.” The Supreme Court found that the arbitration decision clearly intended to grant a business divorce so that Rappaport could not participate in the KABR entities, and the arbitrator was within his discretion to deny carried interest.
Parke Bank v. Voorhees Diner Corp., 480 N.J. Super. 254, 328 A.3d 440 (App. Div. 2024). This case clarified the obligations of a court-appointed receiver to manage the assets of an insolvent company under New Jersey law. This case involves the discharge of Alan I. Gould, Esq., a court appointed statutory receiver in a post-judgment action related to a commercial loan default by Vorhees Diner Corporation (“VDC”). The Appellant Division reversed the discharge of the receiver, noting that not every deficiency under receivership statutes would preclude discharge, but at minimum, court rules and the statute require notice to creditors, inventory, and a final accounting. The court also noted that in limited situations where the dissolving corporation lacks sufficient funds to pay for the costs and fees incurred by the receiver, the party that requests the receiver may be ordered to incur the liability for such payments. In this case, Gould was reinstated as a receiver to fulfill unmet obligations, and the court found that the Law Division had the authority to order the creditor to incur the costs if VDC lacked the funds.
§ 6.6. Derivative Action Issues
§ 6.6.1. California
Norman v. Strateman, 112 Cal. App. 5th 92, 333 Cal. Rptr. 3d 706 (2025). CEO of cryptocurrency exchange company filed derivative complaint on behalf of company against members of company for breach of fiduciary duty, aiding and abetting breach of fiduciary duty, conversion, aiding and abetting conversion, unjust enrichment, accounting, and concealment. One of the members filed derivative cross-complaint against CEO for breach of fiduciary duty, conversion, unjust enrichment/restitution, and accounting. The parties entered into a settlement agreement, which was read into the record but never memorialized into a separate written agreement. Over a year after agreeing to settle, the CEO filed a motion to set aside the settlement. The members filed a motion to enforce the settlement, which the trial court granted. The CEO appealed, claiming the settlement was not enforceable because the trial court had not approved the settlement terms and was required to do so because the action was a derivative one.
Courts may consider shareholder derivative plaintiffs as trustees or guardians ad litem to the corporation’s right of action. Thus, such plaintiffs have no power to settle or compromise the corporation’s action absent court approval. Courts must ensure that derivative settlements are fair and reasonable to the corporation and its shareholders, and the settlements are not a product of fraud, overreaching, or collusion by the settling parties. Simply requiring the parties to enter the terms of the settlement into the record does not satisfy this obligation.
The court remanded the case for the trial court to consider whether the settlement is fair and reasonable and not the product of fraud, overreaching or collusion. The court also instructed that all shareholders should be provided notice of such hearing to the extent practicable.
§ 6.7. Statute of Limitations
§ 6.7.1. Delaware
Tilton v. Stila Styles, LLC, 2025 WL 2355090 (Del. Super. July 22, 2025). Lynn Tilton (“Tilton”) and Octaluna III, LLC (“Octaluna”) sued Stila Styles, LLC (the “Company”), alleging breach of the LLC Agreement for failure to pay $21.8 million in deferred tax distributions for the years 2009–2015. Tilton, as manager of both Octaluna and Stila, claimed to have entered into a series of unwritten “Deferral Agreements” to postpone payment until Stila had sufficient working capital. The parties moved for summary judgment and the Court of Chancery denied the motions, holding that Tilton and Octaluna’s claims were not time-barred or extinguished by bankruptcy, but there were factual disputes that precluded summary judgment in the plaintiffs’ favor.
Tilton controlled the Company through her entity Octaluna and a fund called Zohar III Limited (“Zohar”), which owned all of the Company’s membership interests during the relevant period. As the Company’s sole manager, Tilton arranged for Octaluna to pay the Company’s income taxes from 2009–2015 because the Company was a disregarded entity for tax purposes. In return, the Company had to reimburse Octaluna for those tax payments. Tilton claimed that the parties had an oral agreement to defer repayment until the Company had enough cash.
In response to the plaintiffs’ lawsuit, the Company argued that the tax claim was untimely and, critically, that it had been wiped out by Zohar’s bankruptcy plan during its Chapter 11 bankruptcy. The Court disagreed, noting that the Company’s financial records consistently acknowledged the tax debt, which tolled the statute of limitations and kept the claim alive. Importantly, the Court found that Zohar’s bankruptcy plan did not release the Company from its contractual obligation to repay the tax reimbursements to Octaluna; rather, the plan specifically preserved claims like Octaluna’s against the Company.
Moreover, because of unresolved questions regarding the existence of an enforceable deferral agreement and the precise amount the Company owes, the Court denied summary judgment for the plaintiffs.
§ 6.7.2. Texas
Bertucci v. Watkins, 709 S.W.3d 534 (Tex. 2025). In addition to the issues discussed in the Breach of Fiduciary Duty section above, the court also addressed a statute of limitations issue. Watkins argued that Bertucci’s claims were barred by limitations because Bertucci knew or should have known of Watkins’s actions long before he filed his claims. According to Watkins, this fact was conclusively established by the evidence that Bertucci was the sole investor and an officer, director, member, or partner in the partnership (and thus, like Watkins, owed fiduciary duties to the partnership), and always had access to Watkins’s accounting records.
The court concluded that other evidence created a fact issue on this point, such as the fact that Watkins agreed that he would manage the B-W funds and handle the accounting in accordance with the partners’ agreements, that Watkins owed fiduciary duties to the partnership, that he alone had signature authority over the bank account, that he consistently assured Bertucci that he was properly managing the funds and was only taking amounts Bertucci had agreed he could take, that he, in fact, used B-W funds for his personal benefit, and that, when requested by Christopher, he refused to provide financial information regarding the bank account and made inconsistent statements about the amounts he was entitled to take for his personal use and the amounts he actually took. Thus, the court affirmed the appellate court’s holding that fact issues precluded summary judgment in favor of Watkins on the statute of limitations issue.
§ 7. Valuation and Damages
§ 7.1. Delaware
Ban v. Manheim, No. 2022-0768-JTL, 2025 Del. Ch. LEXIS 118 (Del. Ch. May 19, 2025). In this post-trial ruling, the Court of Chancery held that the controlling owner in an LLC, who unilaterally adopted a by-law providing a call right which allowed the majority owner to compel the minority owners to sell at a “fair price” that the majority sets, is self-interested and procedurally and substantively unfair, and that the defendant ultimately failed to prove the fairness of the transactions. The LLC managed investment funds. Ultimately, the call right was found statutorily invalid under Delaware law because the subject minority owner had not consented to the by-law.
Regarding valuation: as a remedy, the Court awarded monetary damages measured as the fair market value of the subject minority owner’s interests less any cash distributions received from the challenged transactions, instead of recission, considering monetary damages more practical and efficient. Expert witness testimony on valuation was preferred. The Court accepted the use of the Discounted Cash Flow valuation methodology but rejected the later use of new projections by the expert to come up with a higher valuation in a supplemental report, which it deemed less unrealistic. The Court commented “That was improper. An expert cannot come up with completely new inputs in a supplemental expert report. An expert can make adjustments to his opinions to reflect late-breaking discovery, account for the evidence stated at trial, or respond to criticisms from the other side. Here . . . went too far.”
Enhabit, Inc. v. Nautic Partners IX, L.P., 2024 WL 4929729 (Del. Ch. Dec. 2, 2024). In a post-trial Memorandum Opinion, the Delaware Court of Chancery awarded an equitable payment stream, together with mitigation damages and attorneys’ fees due to the egregious breaches of fiduciary duty by Encompass’ officers. April Anthony was the successful founder of Encompass Home Health & Hospice. After becoming disillusioned by the management of her company following its acquisition, she formed a competing business together with two fellow officers. In the course of competing directly with Encompass, they took opportunities, resources and information belonging to Encompass and also induced Encompass employees to join the new, competing company. All of the foregoing was carefully concealed.
Encompass sought rescissory damages in the amount of $462 million or, in the alternative, $157 million in compensatory damages. However, the damages amounts were based solely on projections while the competing company remained profitless. Due to the egregious nature of the breaches of duty, the Court imposed a constructive trust against a fixed portion of the future payment streams in the amount of 43%, together with mitigation damages and attorneys’ fees and costs.
§ 7.2. Illinois
Wolfson v. Dugout Northbrook, LLC, 2025 IL App (1st) 232257. In 2014, Ross Wolfson, Matt Mahay, and Kent Knebelkamp formed Play Ball USA–Northbrook/Glenview, LLC, a member-managed LLC providing youth baseball and training services. Wolfson and Mahay (together, plaintiffs) collectively owned 50% of Play Ball, while Knebelkamp owned the other 50%. The business operated out of a facility leased from GK Holste, LLC, an entity partly owned and managed by Knebelkamp. By 2016, management disputes arose and Knebelkamp took control of Play Ball’s accounting and finances. The owners discussed a separation and wind-up arrangement under which plaintiffs would step back from management, Knebelkamp would run the business under a different name (“The Dugout”), plaintiffs would retain rights to the “Play Ball” name, and the parties would divide Play Ball’s assets. Plaintiffs stopped managing day-to-day operations in late 2016, but Knebelkamp allegedly refused to divide assets and instead attempted to reduce Wolfson’s ownership interest.
In early 2017, plaintiffs demanded formal dissolution. Knebelkamp ignored the demand and continued operating. He then formed Dugout Northbrook, LLC, ran an essentially identical business, and, according to plaintiffs, transferred Play Ball’s assets and operations to Dugout. Plaintiffs also alleged that Knebelkamp used Holste to lease Dugout the entire property (rather than the smaller portion Play Ball had leased), dramatically increased the rent and utilities paid to Holste, and thereby funneled money to himself through related-party transactions. Plaintiffs also alleged that Play Ball’s 2017 tax return showed distributable income to Wolfson that was never paid.
Plaintiffs filed suit seeking (among other relief) dissolution and asserting claims for conversion (count II), breach of fiduciary duty (count III), and unjust enrichment (count IV). Plaintiffs moved for summary judgment and supported the motion with extensive documentary evidence, including bank records, deposition testimony, leases, correspondence, and an expert valuation of Dugout. Knebelkamp largely responded with denials unsupported by counteraffidavits or documentary evidence. The circuit court granted summary judgment for plaintiffs on counts II–IV. It found undisputed evidence that Knebelkamp transferred funds from Play Ball to Dugout, retained or used Play Ball property (including at least a computer and customer lists), and refused repeated demands to divide assets, establishing conversion. On fiduciary duty, the court held Knebelkamp’s duties extended through dissolution and wind up, and that his conduct diverted Play Ball assets for his and Dugout’s benefit. The court also found unjust enrichment based on Knebelkamp’s wrongful retention of Play Ball’s assets and benefits to plaintiffs’ detriment. After summary judgment, the circuit court awarded plaintiffs $513,010.31 in compensatory damages, calculated primarily as 50% of (1) the increased rent paid by Dugout to Holste compared to Play Ball’s rent, (2) utilities paid under Dugout’s lease that Play Ball had not paid, (3) cash distributions Dugout made to Knebelkamp, and (4) 50% of Dugout’s fair market value as of September 30, 2020, based on plaintiffs’ unrebutted expert report. The circuit court also awarded $187,119.67 in attorney fees as punitive damages (50% of the requested fees), finding Knebelkamp’s fiduciary breaches willful and egregious and concluding fees could be imposed as punitive damages.
On appeal, Knebelkamp challenged the summary judgment rulings and the compensatory and punitive awards. The appellate court affirmed. It held Knebelkamp failed to create genuine issues of material fact because he did not support his denials with counteraffidavits or record citations, waived certain arguments by not raising them below, and could not rely on new evidence first presented on reconsideration without a reasonable explanation. The court also rejected Knebelkamp’s dissociation/valuation theory, noting plaintiffs withdrew from management, not membership, and that tax filings continued to treat them as members. Finally, the court held punitive damages (including attorney fees as an element of punitive damages) are available for breach of fiduciary duty and conversion, and it found no abuse of discretion in the punitive award. The appellate court affirmed the circuit court’s summary judgment order and both the compensatory and punitive damages awards.
§ 7.3. Maryland
Maxisiq, Inc. v. Hurysh, No. 22-0314 PJM, 2024 U.S. Dist. LEXIS 201767 *; 2024 WL 4680325 (D. Md. Nov. 5, 2024). This case arose as a buy/sell agreement contract dispute between a corporation in the communications and computer services business and a former member-employee with a 10% ownership interest. The company filed a declaratory judgment action seeking termination of the employee, removal as a member, and valuation and repurchase of his shares. A dispute arose regarding whether the proffered valuation for the company was done in good faith, and the former employee claimed rights to examine the company’s books and records. The US District Court determined that the member-employee had a right to examine books as a litigant, but not as a member.
Regarding the valuation of the membership interest, the court determined that a genuine dispute of material fact existed regarding whether it was conducted in good faith. Although the appraiser retained by the company followed the procedures in the company’s operating agreement, the court found that material issues of fact needed to be determined at trial about the appraiser’s methodology and reliability.
Nevertheless, the court also determined that the 10% member was properly removed from the company and no longer had accounting and inspection rights as a member. But, the court determined, as a litigant, the member would be granted access and discovery to assess the value of the shares and to investigate potential mismanagement and waste of corporate funds.
§ 7.4. Michigan
Atto v. Shammami, No. 367147, 2025 WL 1948908 (Mich. Ct. App. July 15, 2025). After the Comfort Inn in Sault Ste. Marie lost its Choice Hotels franchise flag, plaintiff and defendant formed Soo Hotels, Inc. to operate the hotel while attempting to regain authorization to operate under the Comfort Inn brand. Plaintiff later filed suit on behalf of himself and Soo Hotels, asserting claims of embezzlement, conversion, breach of fiduciary duty, breach of contract, and shareholder oppression. He alleged that defendant froze him out of corporate governance, diverted company funds for personal use, paid himself excessive management fees, and withheld financial information.
Following a bench trial, the trial court rendered a verdict in favor of plaintiffs, finding that defendant treated Soo Hotels as if he were the sole shareholder, excluded plaintiff from governance, converted corporate funds for his own use, and falsely told the corporation’s bank, accountant, and hotel manager that plaintiff no longer held an interest in Soo Hotels and should not be given information. Judgment was entered in favor of Soo Hotels in the amount of $2,029,237.35 for embezzlement and statutory and common law conversion after calculation of treble damages under Mich. Comp. Laws § 600.2919a. The trial court awarded $338,206.23 in damages to the individual plaintiff on the shareholder oppression claim but declined to dissolve the corporation, instead leaving a management company in place to operate the hotel.
On appeal, the sole issue was whether the trial court erred in its calculation of damages and improperly awarded a double recovery for a single injury. Defendant argued that the damages awarded were unsupported by the evidence, relied on flawed accounting, failed to credit his claimed contributions, and impermissibly duplicated recovery. The Michigan Court of Appeals rejected those arguments and affirmed the trial court’s decision, finding that the damages award was not clearly erroneous because it fell within the range of the evidence and was based on a correct application of the governing law and that defendant had failed to preserve the issue of double recovery for appellate review by not raising it in the trial court. Specifically, it found that the trial court’s damages award was supported by both documentary evidence and testimony, including defendant’s own admissions that he had taken substantial sums from Soo Hotels beyond his agreed-upon management fee. It also found that the trial court properly deducted authorized fees and unsupported amounts before imposing treble damages for conversion. Additionally, it noted that damages need not be calculated with mathematical precision, so long as there is a reasonable basis for the computation.
Ideal Holdings of Michigan, LLC v. High Consultants, LLC, 2024 WL 4851400 (E.D. Mich. Nov. 21, 2024). Ideal Holdings of Michigan, LLC and Done Right Properties, LLC sued The High Consultants, LLC and its principal, Marc Steimer, arising out of a failed LLC venture governed by an operating agreement. The complaint asserted claims for breach of contract, breach of fiduciary duty, and member and company oppression under Mich. Comp. Laws § 450.4515. Plaintiffs alleged that High Consultants diverted company opportunities, withdrew from the venture in bad faith, interfered with member relationships, engaged in undisclosed conflicts of interest, refused to execute agreements necessary to carry out the company’s purpose, and ultimately caused the venture to fail. High Consultants failed to appear or answer, and the clerk entered default. The district court then held an evidentiary hearing on damages before ruling on plaintiffs’ motion for default judgment as to High Consultants.
Applying Federal Rule of Civil Procedure 55, the district court first analyzed whether the well-pleaded allegations established liability as to the defendant entity. It declined to enter default judgment on the breach of contract claim, finding that plaintiffs failed to connect the alleged misconduct to specific provisions of the operating agreement. It also noted that Michigan law does not recognize a freestanding claim for breach of the implied covenant of good faith and fair dealing unless the contract grants discretionary authority. However, the district court found that the same factual allegations were sufficient to establish liability for breach of fiduciary duty and LLC member oppression under Mich. Comp. Laws §§ 450.4404 (fiduciary duty) and 450.4515(1)(e) (oppression). It noted that Michigan law imposes fiduciary duties on members and managers in control of the limited liability company to act in good faith, with due care, and in a manner the manager or managing member reasonably believes to be in the best interests of the company. The admitted allegations, including improperly diverting company opportunity, interfering with relationships among the members, and engaging in impermissible conflicts of interest, satisfied these standards and sufficiently established causation of damages.
With respect to damages, the district court emphasized that under Rule 54(c), default judgment relief is limited to the amount demanded in the pleadings, and plaintiffs may not recover more than once for overlapping claims. Based on expert testimony presented at the evidentiary hearing regarding past and future lost profits, the district court found that plaintiffs had established that High Consultants’ conduct caused plaintiffs to incur damages of $5 million, which fell within the range pleaded. Accordingly, the district court entered default judgment against High Consultants on the breach of fiduciary duty and oppression claims in the amount of $5,000,000, denying recovery on the breach of contract claim and declining to award duplicative damages.
Ideal Holdings of Michigan, LLC v. High Consultants, LLC, 2025 WL 786613 (E.D. Mich. Mar. 12, 2025). After obtaining a default judgment against The High Consultants, LLC, plaintiffs sought a default judgment against its principal, Marc Steimer, after he failed to answer the complaint following the district court’s denial of his motion to dismiss. In ruling on the default judgment against High Consultants, the district court had previously held that plaintiffs’ recoverable damages were capped at $5 million, the amount pleaded in the complaint. In their motion for default judgment against Steimer, plaintiffs asked the court to rule differently and award damages exceeding $5 million.
The district court granted default judgment against Steimer under Rule 55, finding that the well-pleaded allegations established his liability for breach of the operating agreement, breach of fiduciary duty, and member oppression under Mich. Comp. Laws § 450.4515. However, the court rejected plaintiffs’ request for damages exceeding $5 million and declined to amend the prior default judgment against High Consultants. The district court determined that all three claims arose from the same underlying conduct and held that plaintiffs were entitled to a single recovery capped at the amount disclosed in the complaint, precluding any double or triple recovery.
§ 7.5. New York
LeVine v. Platzer, Index No. 652616/2021, 2025 N.Y. Misc. LEXIS 8520, 2025 NY Slip Op 34050(U), 2025 LX 487106 (Oct. 17, 2025). In this case, the value of the plaintiff’s ownership interest in an LLP law firm as of the date of judicial dissolution was at issue. The experts agreed to some extent on the selection of the general valuation approach but had divergent opinions regarding the value of accounts receivable, work-in-progress, contingency/flat-fee cases, and its lease.
Regarding valuation of accounts receivable, the court rejected both sides’ expert opinions stating that plaintiff’s expert used arbitrary collectability percentages and the defendant’s expert’s views were unpersuasive. Instead, the court developed its own valuation for accounts receivable by cross-checking it against actual historical collections. Regarding work-in-progress, the court rejected the defendant’s attempt to avoid using a previous stipulation.
Regarding valuation of contingency fees, the court rejected the defendant’s assertion that the contingency and flat-fee cases were impossible to value. Instead, the court adopted and applied an approximation based upon five years of historical revenues. For the lease, the parties disputed whether or not the lease was a liability of the LLP which reduced value. Nevertheless, the court found that the evidence showed that all of the partners planned to continue practicing in the new space under a new firm, with the same employees, and clients. The court also found that the new firm intended to take over the lease and pay it and that there was no evidence that the lease terms were above or below market. The court concluded that lease was not an economic liability of the LLP for valuation purposes.
Segal v. Rethink Capital Partners, Index No. 74512/2024, 2025 N.Y. Misc. LEXIS 2517, 2025 NY Slip Op 50566(U) (Apr. 10, 2025). This case involved a limited liability company and a mandatory buyout of a minority owner pursuant to an operating agreement. The company operated as an investment manager. The plaintiff minority owner asserted that the majority owners engaged in a “scheme” to “artificially depress” value to spur an artificially low buyout price. In addition, the minority owner asserted that the valuation firm engaged by the company participated in the scheme and sued the valuation firm, asserting aiding and abetting of fiduciary duty breaches, civil conspiracy, and breach of contract, plus asking for a declaratory judgment that the valuation is invalid.
Regarding the claims against the valuation firm: the trial court ruled that the valuation firm could not be sued because of a procedural failure. Nevertheless, the court also ruled that the valuation firm was hired unilaterally by the company and, therefore, the valuation was invalid because the operating agreement required mutual agreement by both parties on the selection of an independent valuation firm. Furthermore, the procedural failure is because the defendant valuation firm is not the valuation firm “retained” under the operating agreement, because the defendant valuation firm was not properly retained. Therefore, the court also dismissed the part of the plaintiff’s action against the appraisal firm.
§ 7.6. Virginia
Kirdassi v. White, 913 S.E.2d 311 (Va. Ct. App. 2025). The owners of a Delaware corporation were in business divorce litigation involving multiple claims and the related valuation implications. Claims of breach of fiduciary duty, breach of contract, conversion, and statutory business conspiracy under multiple states’ laws were asserted. The corporation is in the business of medical provider and wellness therapy services. At trial, the court rejected expert opinion regarding valuation because of what the court deemed to be unreliable financial information.
On appeal, regarding valuation and damages, the Appellate Court found that the trial court misconstrued the shareholders’ agreement regarding the required valuation terms, that the trial court’s valuation finding lacked support, and that led to incorrect quantification of damages. The Appellate Court remanded the case to the trial court to redetermine liability and damages to quantify contractual damages consistent with the shareholders’ agreement’s language and the plaintiff’s documented investment.
Directors’ and officers’ liability insurance only protects boards, executives, and other individuals for claims challenging conduct undertaken in an official capacity on behalf of the insured company. Given the importance of the specific role, status, or official function held when the alleged wrongdoing occurred, so-called “capacity” issues are a recurring source of coverage disputes and denials.
The sources of capacity limitations range from conspicuous—like outside-capacity exclusions—to more nuanced—like embedded requirements in definitions or allocation methodologies. In all instances, small wording differences can determine whether an insurer must defend or advance costs for a claim involving overlapping corporate, personal, or outside-entity roles.
Policyholders should therefore resist treating “capacity” as a single exclusion to check at renewal. The better approach is to assess the issue across the entire policy and compare the wording against the company’s actual organization, governance, and business practices. Here are four places where capacity problems can arise.
1. Who Qualifies as an “Insured Person”?
Almost all D&O policies define insured persons to include past, present, and future “duly appointed or elected” directors and officers, which can create coverage hurdles for nonelected and nonappointed officers, including chief information security officers (“CISOs”) who may find themselves under intense scrutiny following security incidents. Qualifying as an insured persons can also negate coverage if, for example, an individual’s status as a duly elected or appointed member of the board brings a claim within a D&O policy’s insured-versus-insured exclusion.[1]
Insured person coverage also extends to individuals only when they are acting in capacities on behalf of insured entities. While a superficial assessment of coverage for all appointed officers and directors may seem broad, securing coverage for individuals on boards of the company’s subsidiaries, affiliates, or joint ventures can lead to surprise denials if those entities are not also insured under the company’s D&O policy. Tracking coverage up and down the organizational chart, especially for executives wearing multiple hats across affiliated entities, can avoid uninsured entities leading to material gaps in coverage.
Broader coverage in private company D&O forms can extend to employees and, in some cases, even independent contractors. Specialized private equity policies can also include partners, managers, and other parties at different affiliated entities. While such broad definitions of insured persons may be comforting, that doesn’t necessarily mean coverage is always preserved. For example, expanded coverage may be dependent on additional requirements being met, like having proper indemnification agreements in place that are at least as broad as those in place with regularly appointed officers or directors. Where no such agreements exist, coverage may be denied.
2. Understand Capacity Limitations in the Definition of “Wrongful Act”
The policy’s definition of “wrongful act” can also serve as another barrier to coverage. Some policies define wrongful act to include any error, misstatement, misleading statement, act, omission, neglect, or breach of duty actually or allegedly committed or attempted by an insured person “solely in their capacity as such.”
When a policy limits coverage to only acts committed “solely” in an insured capacity, that limitation can be used to bar coverage for so-called “mixed” claims alleging acts committed in both covered and uncovered capacities. To demonstrate the problematic nature of such a policy requirement, consider the following claim examples.
A company is sued by a current employee’s former employer in a suit alleging breach of employment agreements (at the prior company) and theft of trade secrets in a course of conduct that allegedly occurred before, during, and after the employee was hired.
Minority shareholders allege that a founder CEO structured a transaction to increase the value of the CEO’s personal holdings at the expense of other shareholders, challenging his conduct in managing the company, as well as in personally enriching himself as a key shareholder.
A portfolio company board member who was appointed by a private equity sponsor is sued by creditors in a suit alleging that the outside director favored the sponsor’s interests over those of the company.
These scenarios are not hypothetical. In Liberty Insurance Underwriters, Inc. v. Cocrystal Pharma, Inc., No. 22-2242, 2023 WL 3067498 (3d Cir. Apr. 25, 2023), for example, the parties disputed whether a Securities and Exchange Commission investigation concerned wrongful acts committed by the insured company’s directors and officers, which required acts by insured persons “in their capacities as such,” or whether the investigation involved acts of the predecessor company that fell outside of coverage. The Third Circuit concluded the SEC’s subpoena reasonably indicated that the investigation involved wrongdoing by the insured company, which created fact issues for trial.
If wrongful-act definitions insure only conduct taken “solely” in covered capacities, or if the policy is not structured in a way to account for dual- or multi-capacities (e.g., allocation, outside directorships), the D&O policy may not respond as intended.
3. Beware of Capacity Exclusions
Perhaps most problematic of all are capacity exclusions, which often explicitly bar coverage for claims arising in whole or in part out of acts allegedly done in an uninsured capacity. One version of that exclusionary language bars coverage for
payment for Loss in connection with any Claim made against an Insured Person based upon, arising out of, directly or indirectly resulting from, or in any way involving any wrongful act while serving in the capacity as a director, officer, trustee, employee, or member of any other entity other than the Insured Company.
Entities implicating capacity exclusions include affiliated companies, joint ventures, subsidiaries, and venture capital or private equity portfolio companies, to name a few. In Mist Pharmaceuticals, LLC v. Berkley Insurance Co., 355 A.3d 253 (N.J. 2026), the New Jersey Supreme Court applied a capacity exclusion for claims “in any way involving” service for an uninsured entity to bar coverage for self-dealing claims implicating the insured person’s overlapping roles with insured and uninsured entities. Other courts have taken similar views when interpreting broadly worded capacity exclusions.[2]
Broad lead-in language like “based upon,” “arising out of,” or “in any way involving” can make express capacity exclusions even more consequential, reaching entire claims that combine insured and uninsured roles, rather than only the portion attributable to outside service.
4. Consider Capacity Issues in Business Transactions
Contracts themselves can also serve as a barrier to coverage. Certain loans, such as those found in real estate “bad boy” carve-outs, can often involve personal guarantees, requiring the corporate officers to sign as a guarantor. Directors and officers may operate under the assumption that such guarantees were entered into as part of their duties on behalf of the company, given that the loans in question are pursued for business interests.
Insurers, and sometimes courts, may not view them as favorably when assessing D&O coverage for claims arising from contracts executed in personal capacities. The manner in which contracts are signed may also be brought into question. Contracts that directors and officers sign in their individual names (without mention of an executive role) are even more likely to be viewed as personal contracts and uninsurable by a D&O policy. In Hanover Insurance Co. v. Larson, No. 25-2543, 2026 WL 2295457 (8th Cir. Aug. 10, 2026), for example, executives signed loan documents associated with the company, but they also signed separate guaranty agreements identifying themselves as guarantors without referencing their executive titles in the signature blocks.
When lenders later sought payment from the executives individually, the D&O insurer denied coverage. The policy covered former executives only while acting solely in their insured capacities, and the court concluded that the guarantees reflected an intent to assume personal liability. The restrictive definition of insured person removed the guaranty claims from the scope of coverage under the company’s D&O policy.
Takeaways
Capacity questions abound in D&O policies. Coverage may turn not only on nuanced policy wording but also on the specifics of corporate appointments, the entities involved in the alleged conduct, the underlying transaction, and the facts alleged in each claim.
Policyholders should evaluate capacity risk against how executives actually operate, particularly where individuals serve multiple affiliated entities. At renewal, policyholders should seek wording that accommodates mixed capacities, limits capacity exclusions to loss attributable to uninsured roles, and avoids “solely” requirements that can convert an otherwise covered role into a complete bar to coverage.
See, e.g., Divinia Water, Inc. v. Clear Blue Specialty Ins. Co., No. 4:23-mc-00095-AKB, 2024 WL 1131291 (D. Idaho Mar. 15, 2024) (holding under Idaho law that the company’s ratification of procedurally deficient board appointments rendered the individuals “duly elected or appointed” directors, making them “insureds” that triggered the D&O policy’s insured-versus-insured exclusion). ↑
See, e.g., Sec. Nat’l Ins. Co. v. Hendrik Uiterwyk, P.A., 725 F. Supp. 3d 1308, 1321–23 (M.D. Fla. 2024) (barring coverage under capacity exclusion in professional liability policy where underlying claims involved joint venture that was a separate business enterprise from the insured law firm); Goggin v. Nat’l Union Fire Ins. Co. of Pittsburgh, No. N17C-10-083 PRW CCLD, 2018 WL 6266195, at *4–5 (Del. Super. Ct. Nov. 30, 2018) (affirming insurer denial for claims against directors where alleged wrongdoing was not “solely by reason of their status” as executives of the insured). ↑
Alternative Dispute Resolution (“ADR”) processes such as arbitration and mediation have emerged as the preferred framework for resolving financial disputes across industries: from complex banking litigation and securities controversies to commercial lending conflicts and insurance coverage battles. For business attorneys advising clients with financial stakes, ADR offers a compelling array of procedural advantages that might not be available in litigation.
Nowhere are the advantages of ADR more apparent than in financial disputes. Cost efficiency, one of ADR’s most touted advantages, is one of the main reasons. Financial disputes routinely involve voluminous document discovery, expert witnesses, and extended pretrial proceedings, each adding costs. Using ADR compresses this timeline, often resolving disputes in months rather than years, delivering proportionate outcomes without disproportionate legal spend. Beyond cost, the confidentiality offered by ADR is also a key consideration: Unlike public court proceedings, ADR outcomes and proceedings remain private, protecting sensitive financial data, proprietary methodologies, and reputational standing, all concerns of paramount importance for institutional clients, investment firms, and high net worth individuals. ADR also provides litigants with the ability to select neutrals with financial expertise from a deep well of experts who have often practiced in the very area at issue in the dispute. By doing so, parties retain greater control over the process; selection of arbitrators and mediators, coupled with the ability to choose procedural rules and provide substantial input on scheduling, offers a degree of autonomy that litigants do not enjoy in court. Finally, ADR agreements are broadly enforceable under domestic and international frameworks, including the Federal Arbitration Act and the New York Convention, giving awards a reliability that often rivals, and in cross-border matters, surpasses, court judgments.
Understanding these benefits is key for parties wishing to effectively use ADR for financial disputes.
Key Considerations Before Choosing ADR
While the benefits of ADR for financial disputes are numerous, not every financial dispute is equally well suited to every ADR mechanism. Business attorneys must evaluate several threshold considerations before recommending a path.
Nature and Complexity of the Dispute: High-stakes securities fraud or complex derivatives disputes may benefit from arbitration panels with specialized financial credentials, while commercial disagreements may be better served by mediation’s relationship-preserving aspect.
Discovery Needs: ADR typically allows limited discovery. If a party’s case depends on extensive document production or depositions, ADR’s streamlined process may prove a constraint rather than a benefit. Careful consideration of exactly how much discovery you want in the dispute is warranted.
Enforceability and Appeals: Arbitral awards are final with very narrow grounds for appeal. Parties seeking appellate review of legal errors should weigh this carefully. Arbitration provides options for appeals, but these must be agreed to at the outset of the proceeding or in the ADR clause, and even then, grounds for appeal are often narrower than those provided in court. Additionally, mediation is only as binding as the parties’ commitment to comply with the settlement agreement, unless the parties appoint an arbitrator to execute the agreement as a consent award.
Contractual Obligations: Review all underlying agreements for existing ADR clauses—including their scope, chosen rules, seat, and governing law—as these provisions are generally binding and shape available options. Parties can always agree to submit their disputes to arbitration or mediation, modify the ADR clause by agreement, or provide tiered or step-by-step escalating ADR options; the customization is limited only by the parties’ imagination. Still, ensuring these dispute resolution clauses are drafted to both parties’ satisfaction up front is necessary, as once a dispute arises, further agreement (especially modifying existing ADR provisions) between the parties may be difficult.
What Business Attorneys Need to Know
Drafting robust and thoughtfully considered ADR clauses at the contract stage is the most underutilized form of dispute risk management available to business attorneys. Every financial services agreement should include a carefully tailored ADR provision specifying the mechanism, administering institution, seat, applicable rules, number and qualifications of neutrals, and the governing law. Use discretion when drafting a custom ADR provision: Beyond the basic requirements, more detail is not always useful or needed. When in doubt, all major ADR providers have standard model ADR clauses that will address many of these issues.
In financial disputes—loan syndications, hedge fund management disputes, purchase price adjustments, M&A earnouts, insurance coverage battles—the neutral’s industry knowledge is essential for a streamlined process, allowing the parties to focus on presenting their case rather than educating the neutral on the subject matter. For example, CPR Dispute Resolution Services maintains a vetted panel specifically for banking, accounting, and financial services disputes, comprising attorneys and professionals with deep subject matter experience in exactly these areas. The American Arbitration Association’s Commercial Panel includes experienced arbitrators and mediators with extensive backgrounds in the financial sector. And the neutrals of the JAMS Financial Markets Group are experienced in resolving complex securities and financial markets disputes. Using a provider with a dedicated financial services panel removes the substantial risk of educating a generalist neutral at the parties’ time and expense.
Attorneys must also remain current on institutional rule changes. The AAA Commercial Rules, JAMS Financial Industry Arbitration Rules, Financial Industry Regulatory Authority Arbitration Code, and CPR Administered Arbitration Rules are periodically updated and materially affect procedural rights, discovery scope, and costs.[1] Understanding FINRA’s mandatory arbitration requirements is essential for broker-dealer and investment adviser disputes, where it displaces court jurisdiction almost entirely.
Privacy and privilege considerations also deserve careful attention. The confidentiality protections of mediation communications vary by jurisdiction under applicable mediation privilege statutes. In arbitration, ex parte communication with arbitrators is generally prohibited; in mediation, ex parte communication with mediators is common, such as in the form of mediation statements. And arbitration rules treat confidentiality differently depending on the ADR provider selected. Attorneys should advise clients on the limits of confidentiality and the importance of preserving privilege throughout the process, especially when the use of artificial intelligence is involved.
Modern ADR Strategies
The ADR landscape has evolved considerably, and sophisticated practitioners are deploying a new generation of strategies particularly well-suited to financial disputes. There are many options available to the parties to a dispute beyond just mediation or arbitration.
Med-Arb and Other Hybrid Models: These hybrid models combine the flexibility of mediation with the finality of arbitration. In a med-arb structure, parties first attempt mediation; if unsuccessful, the same or a different neutral then holds a hearing and issues a binding arbitration award, preserving settlement opportunity while guaranteeing resolution. With CPR’s Concurrent Arbitration-Mediation Protocol, for example, parties agree they will attempt to settle any dispute that is the subject of arbitration by participating in a confidential mediation conducted during the pendency of the arbitration. This process was developed to encourage the availability of mediation to parties in a more flexible manner than is provided under standard multistep dispute resolution provisions and creates an opportunity for parties to continue to explore settlement options based on what they learn during the arbitration proceeding and without delaying those proceedings.
Early Neutral Evaluation (“ENE”): An experienced financial professional provides a nonbinding assessment of the merits and likely damages range early in the dispute. ENE dramatically accelerates settlement by aligning expectations and surfacing weaknesses before positions harden. Parties can use this information to steer settlement discussions or have a more realistic view of potential outcomes in an arbitration or litigation process.
Expedited and Emergency Arbitration: Most major arbitral institutions now offer expedited rules with even more expeditious timelines and emergency arbitration procedures, enabling parties to obtain interim relief to freeze assets or to be granted injunctions in urgent financial scenarios.
Dispute Prevention: Parties entering into joint financial ventures may wish to incorporate dispute prevention mechanisms to assist in resolving minor conflicts before they become full-blown disputes. This can be achieved by enlisting a standing neutral or a dispute resolution board (“DRB”) to check in with the key stakeholders throughout the venture. Some institutions have created formalized procedures for this process to help parties set up and manage a DRB.
Conclusion
Ultimately, mastery of ADR in financial disputes is no longer optional for business attorneys—it is a core competency that directly determines the quality and cost-effectiveness of outcomes for clients navigating today’s complex financial landscape. The most effective practitioners approach ADR as a strategic process that can be tailored to the commercial realities, procedural needs, and risk tolerance of the parties involved.
By drafting thoughtful dispute resolution clauses, selecting neutrals with genuine financial expertise, and using tools such as mediation, expedited arbitration, emergency relief, and dispute prevention mechanisms, attorneys can help clients avoid and resolve conflicts with greater precision and predictability. In an environment where financial disputes often involve sensitive information, ongoing business relationships, and significant reputational concerns, ADR offers a practical framework for achieving durable resolutions while preserving confidentiality and control. For clients and counsel alike, the future of financial dispute resolution will belong to those who use ADR deliberately, creatively, and with a clear understanding of its evolving possibilities.
Introduction: A Landmark Decision, Still Unfolding
The intersection of artificial intelligence and copyright law continues to be a legal gray area, and it has only grown more layered since courts first began weighing in. On February 11, 2025, Judge Stephanos Bibas of the U.S. Court of Appeals for the Third Circuit (sitting by designation in the U.S. District Court for the District of Delaware) issued the first U.S. federal court decision addressing fair use in the context of AI training data. In Thomson Reuters Enter. Ctr. GmbH v. Ross Intel. Inc., 765 F. Supp. 3d 382 (D. Del. 2025), the court ruled that Ross Intelligence’s use of Thomson Reuters’s Westlaw headnotes to train a nongenerative AI tool was not protected by fair use.
That ruling is not the end of the story. The Third Circuit granted Ross permission to pursue an interlocutory appeal, heard oral argument on June 11, 2026, and has not yet issued a decision as of this writing. District court proceedings remain stayed pending that appeal. Any assessment of Thomson Reuters v. Ross today has to account for the fact that its final scope is still being decided, and reporting from the argument suggests at least some appellate skepticism toward Ross’s transformative-use theory, though the outcome remains genuinely open.
At the time of the district court’s ruling, the decision sparked widespread media coverage, with many commentators suggesting it set a precedent for the flood of AI-related copyright lawsuits then pending. However, despite its significance, the Thomson Reuters v. Ross ruling has had a narrower applicability than some headlines suggested, and rulings issued in other cases just months later reinforced that point directly. Key differences, such as the nature of Ross’s product, access to the copyrighted works, and the type of AI involved, limited the breadth of the case’s influence even before the appeal was granted.
This article revisits those distinctions, examines how they have already played out in other courts, and offers practical takeaways for creators and companies navigating the evolving legal landscape of AI and copyright.
1. Competing Products Make All the Difference
Why Ross’s AI Tool Was Seen as a Direct Market Substitute
A central reason Ross lost on fair use’s fourth factor, effect on the market, was that its AI tool directly competed with Thomson Reuters’s Westlaw platform. Ross used Westlaw’s copyrighted headnotes to develop a similar legal research product, creating a clear market substitute. Even if Ross’s AI didn’t replicate Westlaw’s user interface, the underlying use harmed Thomson Reuters’s potential market, including the market for licensing training data.
By contrast, many AI copyright cases involve generative AI systems trained on publicly available online articles, where the content owners aren’t developing competing AI tools. Without direct market competition, courts may reach different conclusions on fair use’s market-effect factor—and as discussed below, they already have.
2. Paywalls Matter: Access Restrictions Shaped the Court’s View
Why Westlaw’s Paywall Strengthened Thomson Reuters’s Case
Westlaw’s headnotes aren’t publicly accessible; they’re behind a paywall available only to subscribers. Although copyright protection doesn’t require restricted access, Thomson Reuters’s paywall and user agreements signaled its intent to control how the headnotes were used. Ross’s unauthorized access and use of this content, possibly in violation of Westlaw’s terms of service, further undermined its fair use argument.
This contrasts with other AI lawsuits that involve freely accessible online materials. When content is publicly available, especially without paywalls or usage restrictions, courts might weigh fair use factors differently, particularly if the AI tool’s use is more transformative. As a later section of this article shows, access alone is not the whole picture. How the underlying copies were obtained matters just as much.
3. Generative vs. Nongenerative AI: Why That Distinction Matters
Ross’s Tool Didn’t “Transform” the Original Work
One of the most critical factors in the court’s decision was the type of AI at issue. Fair use’s first factor looks to the purpose and character of the use of the copyrighted material, particularly whether the use was “transformative.” Ross’s technology was nongenerative. It used the headnotes to enhance a legal research tool that performed the same basic function as Westlaw: providing legal information. Because the use was not transformative, the court found against Ross on fair use’s first factor.
Many AI copyright cases, however, involve generative AI models that synthesize training data into entirely new outputs (such as original text, images, or code) that differ from the purposes of the original works. When the authors first began to draft this article, courts had yet to address how these transformative uses fit into the fair use framework. That has since changed.
4. The Generative AI Test Has Already Arrived: Bartz and Kadrey
This article’s central prediction, that generative AI training might fare differently than Ross’s nongenerative tool, did not stay hypothetical for long. Within weeks of the Thomson Reuters decision, two Northern District of California judges ruled on closely related questions involving large language models trained on copyrighted books.
In Bartz v. Anthropic, 787 F. Supp. 3d 1007 (N.D. Cal. 2025), the court held that training Anthropic’s models on lawfully acquired copyrighted books was fair use, finding the training process highly transformative. The same court reached the opposite conclusion for a different category of inputs: books Anthropic had obtained from pirate libraries and retained in a general-purpose corpus, which the court found infringing regardless of how the resulting models were later trained. Just days later, in Kadrey v. Meta (788 F. Supp. 3d 1026 (N.D. Cal. 2025), a different judge reached a broadly similar split on comparable facts involving Meta’s Llama models.
Bartz went on to settle for $1.5 billion, the largest copyright class action settlement on record, with final court approval entered in July 2026. Kadrey remains active on the claims the court did not resolve on summary judgment, including issues tied to how the underlying training copies were acquired.
Together, these rulings sharpen, rather than simply confirm, the distinction this article draws. The line that matters most is not only generative versus nongenerative AI. It is also lawful acquisition versus unlawful acquisition of the underlying training data. A company that trains a generative model on copyrighted works it never had the right to possess in the first place may find fair use unavailable regardless of how transformative the resulting model is. That has direct, practical implications for how companies vet the provenance of training data, and the tools built on it, not just how they classify the type of AI involved.
5. Protecting Your Creative Work While Legal Uncertainty Persists
What Content Owners Can Do Now, Without Waiting for Courts to Decide
While the legal landscape evolves, creators and businesses don’t have to stand still. There are proactive steps that can be taken to protect intellectual property in the face of AI-related challenges.
Use strong contracts: Clear licensing terms and usage restrictions can prevent unauthorized use of your content, even for AI training purposes.
Diversify your IP protections: Patents, trademarks, and trade secrets can complement copyright protection, covering aspects that copyright doesn’t.
Develop licensing strategies: Creating licensing models for AI training data can turn potential risks into revenue opportunities while maintaining control over how your content is used.
Scrutinize provenance, not just purpose: As Bartz and Kadrey show, courts are drawing a sharp line between lawfully acquired and pirated training data. Companies licensing or deploying AI tools should ask how the underlying training data was sourced, not only what the AI does with it.
Conclusion: One Decision, Fewer Open Questions Than a Year Ago
The Thomson Reuters v. Ross ruling marked a pivotal moment in the evolving relationship between copyright law and artificial intelligence, but it was never a catchall precedent, and the year since has proven that out. Bartz v. Anthropic and Kadrey v. Meta already show that generative AI cases can and do come out differently, particularly where training data was lawfully acquired. At the same time, Thomson Reuters v. Ross itself remains unresolved on appeal, and the Third Circuit’s ruling, whenever it is issued, will be the first federal appellate word on fair use and AI training of any kind.
For content creators, technology companies, and legal professionals, the key takeaway is unchanged in substance but sharper in focus: Don’t assume any single decision, including this one, answers every question about AI and copyright. Stay informed, be proactive about how training data is sourced and licensed, and prepare for a legal landscape that is still being actively written, one appellate ruling at a time.
The views expressed here are the authors’ own and do not necessarily reflect the positions of their respective employers or firms.
Connect with a global network of over 30,000 business law professionals