Many people believe the American dream of owning a home is becoming further and further out of reach. Market data paints a striking picture. As home prices rapidly rose in the wake of the COVID-19 pandemic, increases in median income failed to keep pace. Whereas a market standard is that homeownership costs generally should not exceed a 30 percent share of income, Federal Reserve Bank of Atlanta data suggests that the median household income share of median homeownership costs is now approximately 43 percent. The contributing drivers have ebbed and flowed: high interest rates on mortgage loans peaked as a key affordability factor in 2023, but rates have begun moderating, with Freddie Mac reporting in its Primary Mortgage Market Survey in July 2026 a 6.55 percent weekly average, 0.20 percentage points down from a fifty-two-week high. However, the S&P Cotality Case-Shiller U.S. National Home Price Index continues to climb.
The rise in home price appreciation is significantly driven by an imbalance of supply. Data published by the Joint Center for Housing Studies of Harvard University shows that home inventories for sale have modestly risen since the pandemic, but recent upticks in inventory are partially attributable to average time on the market for sale increasing as well. In any event, existing home inventory for sale remains below pre-pandemic levels. New housing starts likewise have increased modestly but not above the levels prior to the 2008 financial crisis. At the same time, current homeowners are staying in their homes longer. Redfin data placed the average time U.S. homeowners stay in their homes at 12 years in 2025, almost double the length before the financial crisis of 6.5 years. Furthermore, homeowner turnover (i.e., home sales per 1,000 homes) measured only 2.77 percent, one of the lowest levels since the mid-1990s. Factors contributing to longer tenure and lower turnover may include home price affordability, retaining lower interests on existing mortgage loans, and economic uncertainty.
Existing housing policy is likely driving these trends and can also be tailored to address them. For example, in California, Proposition 13 amended the state constitution to limit year-over-year increases in property taxes, and for nearly fifty years, these increases have not kept pace with the market value of the properties. Instead, Proposition 13 generally limits reassessment to the time a home sells, creating an incentive for established homeowners to stay. This is consistent with observed homeowner tenure patterns; whereas the national average homeowner tenure is about twelve years, California’s average is about twenty years. On the other hand, numerous proposals have aimed to combat supply-side housing constraints, including the Trump administration’s executive order to prevent “large institutional investors” from acquiring single-family homes, efforts to “upzone” existing neighborhoods to allow for more density, local neighborhood stabilization programs to address blight, and housing subsidized through nonprofit community land trusts and low-income housing tax credits.
The housing finance industry and agencies are also addressing affordability through demand-side affordability products. The proposal that has gotten the most public attention in the last year has been the Trump administration’s fifty-year fixed rate mortgage. Although the true affordability of a fifty-year mortgage product can be scrutinized, lenders and government agencies have other tools to make homeownership more affordable. These include assumable mortgages securing FHA (Federal Housing Administration), VA (U.S. Department of Veterans Affairs), and other loans that need not be paid off at sale; loans that have low down payment requirements (such as the Fannie Mae HomeReady program) or no down payment (such as VA and U.S. Department of Agriculture loans); down payment assistance grants such as those offered by Federal Home Loan Banks and local nonprofits; and “piggyback” second mortgage programs (such as the Freddie Mac Affordable Seconds program) that allow borrowers to take a first mortgage at a loan to value ratio low enough to avoid private mortgage insurance and a simultaneous second mortgage to fund a portion of the down payment.
There are potential policy-based solutions to address both supply- and demand-related challenges in housing affordability, including the expansive reforms in the 21st Century ROAD to Housing Act enacted in July 2026. While these reforms will take time to implement, the Act includes initiatives to study and expand access to small-dollar mortgage loans, raise awareness of federally backed programs like VA lending, increase housing supply, and support public welfare investments in affordable housing. On the other hand, existing law also includes guardrails to limit features that might potentially harm borrowers. These guardrails include the requirement that creditors assess borrowers’ ability to repay their mortgage loans. Many lenders comply with the ability-to-repay rules by originating only so-called “qualified mortgages,” which cannot include features such as negative amortization, interest-only payments, balloon payments, terms in excess of thirty years, or points and fees in excess of 3 percent of the loan amount. Furthermore, both the Home Ownership and Equity Protection Act and the Dodd-Frank Wall Street Reform and Consumer Protection Act include additional restrictions on “higher-priced mortgage loans” and “high-cost mortgages.”
Another consideration is whether affordability products are offered where they are needed most. Federal and state credit and housing discrimination laws, such as the Equal Credit Opportunity Act and the Fair Housing Act, are designed not just to increase access to credit but also to prevent predatory lending affecting protected classes. Key exceptions include special purpose credit programs (“SPCPs”), which historically could be targeted to benefit certain identified classes who might not otherwise obtain credit on favorable terms and have previously been applied to make housing more affordable. Recent rulemaking by the Consumer Financial Protection Bureau, however, limits SPCPs as an option for certain protected classes. And for banks that are subject to the Community Reinvestment Act, their penetration into low- and moderate-income neighborhoods through home lending, community development investments in housing-related programs, and flexible and innovative products all contribute to the evaluation of whether they are meeting the needs of their communities. Affordable housing is poised to remain at the forefront of policy debate for years to come.
This article is related to a CLE program that took place during the ABA Business Law Section’s 2026 Spring Meeting. The panelists have diverse viewpoints, so not all opinions expressed here are attributable to all panelists. To learn more about this topic, listen to a recording of the program, free for members.
Litigation funding involves someone (a dedicated litigation funder, a hedge or private equity fund, or a private party) handing over funds to a lawyer, a plaintiff, or both. In a sense, the funder is making a bet on the eventual success of the litigation. The money is almost invariably offered on a nonrecourse basis, so if the litigation is a bust, the plaintiff or lawyer does not owe the funder anything.
In the early days of litigation funding, plaintiffs were the usual recipients of these funds. They still can be today, either alone or in concert with their lawyer. In the latter case, both plaintiff and lawyer might obtain funding together. However, in recent years, lawyers and law firms, including some very large firms that you might not think of as typical plaintiff lawyers, have emerged as some of the biggest consumers of litigation funding.
The funder may be betting on a single case from which the lawyer anticipates a healthy contingent fee. Alternatively, the funder may be investing in a whole bevy of cases that the law firm has underway. They may all be similar or related cases, or they could be unrelated cases. The funder gets additional spreading of its risk in these so-called portfolio funding transactions.
Loan, Sale, or Prepaid Forward Sale
How are these transactions taxed? To answer, one first should look at the documents. You cannot assess how a transaction will be taxed without seeing the underlying documentation. Some transactions, albeit a minority, are documented as nonrecourse loans. The funder loans money, and the lawyer must repay it plus a healthy amount of interest if the case is successful.
If the documents support treating the arrangement as a loan for tax purposes, the loan proceeds are not income to the lawyer. However, the tax treatment that both the funder and the lawyer receive from a loan is generally disadvantageous. This is one major reason that few transactions are documented as loans. A transaction could be documented as a current purchase and sale of an interest in the case, but that too is uncommon, because of the poor tax treatment to one or both sides.
Instead, for at least the last fifteen years, litigation funding transactions have typically been documented with prepaid forward purchase agreements (“PFPAs”) rather than via loan or sale agreements. The PFPA is not a debt instrument and has no interest payments, and given its terms, it is impossible to tell how much the plaintiff or lawyer contracting with the funder will ultimately pay. This is one reason that the litigation funding industry uses PFPAs, which are a form of variable prepaid forward contract.
The tax authorities say that a taxpayer who receives an advance payment of the purchase price of property under a properly structured PFPA is not taxable on receipt of the advance payment. Instead, the transaction is held open until the contract is settled. The IRS approved this treatment in Revenue Ruling 2003-7, consistent with the fundamental principle that gross income includes gains derived from dealings in property, not gross sale proceeds, per Section 61(a)(3) of the tax code.
In a litigation funding contract involving a law firm, the funder makes one or more cash advances to the law firm. The advances are in exchange for the law firm’s promise to sell the funder a variable portion of the attorney fees and costs that the law firm hopes to receive under its contingent fee agreement with its client.
Single-Case Funding
The PFPA may relate to the law firm’s representation of a single client in a single case. The law firm agrees to sell the funder a variable portion of whatever tangible or intangible property it recovers from its representation of that particular client in that single case. The law firm’s right to payment does not accrue until the case is resolved, whether by settlement or by a nonappealable final judgment.
Once the law firm’s payment right accrues, two things happen. First, the law firm should report its recovery as compensation in accordance with its method of accounting. The basic tax principle that compensation income is taxed when earned is unaffected by whether the law firm has made a side bet with a funder.
Second, the accrual of the law firm’s payment right entitles the funder to a portion of the recovery under the PFPA. When the law firm settles its obligation, the PFPA provides that the law firm’s payment terminates the parties’ rights and obligations under the contract. When the PFPA is terminated, the law firm calculates and reports its gain or loss under the contract.
This is generally equal to the difference between (1) the advances the law firm received and the sum of the law firm’s payments to the funder and (2) the law firm’s basis in the PFPA. Section 1234A of the tax code requires taxpayers to report capital gain or loss from certain terminations of sale contracts. However, because the property that is the subject of the sale is the law firm’s right to fees, the law firm’s gain or loss is ordinary gain or loss under the substitute-for-ordinary-income doctrine, consistent with United States v. Midland–Ross Corp., 381 U.S. 54 (1965).
Hence, the resolution of the case should result in the law firm reporting ordinary compensation income equal to the gross amount of its recovery, and ordinary gain or loss from the termination of the PFPA. In that way, the law firm is paying tax only on the funds that it gets to keep from the case, not on the amount it owes the funder.
Portfolio Funding
In a portfolio funding transaction, the law firm enters into a single PFPA requiring it to sell the funder a portion of its recoveries from multiple cases. The PFPA requires the law firm to make payments to the funder whenever any case in the portfolio is resolved as specified in the contract. A taxpayer who sells a collection of assets should generally treat the transaction as a collection of separate sales, rather than as the sale of a single asset, consistent with Williams v. McGowan, 152 F.2d 570 (2d Cir. 1945).
Applying this principle to portfolio funding, the law firm should generally report the results of settling its obligations with respect to any particular case in the year that case is resolved. To calculate the law firm’s gain or loss, an appropriate portion of the funder’s advances should be allocated to the case in question as the amount realized in that sale.
Novoselsky Case
This tax case does not apply in this context, but its notoriety makes it worth a few paragraphs. Novoselsky, TC Memo. 2020-68, was a 2020 Tax Court case that caused some people to worry that it could apply to commercial litigation funding. The case involved a lawyer’s do-it-yourself loans from interested parties that have no bearing on commercial litigation funding.
Novoselsky tried to borrow money on a nonrecourse basis using self-drafted “litigation support agreements.” His agreements were so poorly written that the IRS argued—and the Tax Court held—that they failed to create debt for tax purposes, so he had to report the payments he received in his income. Novoselsky even argued that the payments should be classified as nontaxable gifts or amounts he received in trust.
Not surprisingly, the Tax Court sided with the IRS. The case has no application to properly drafted litigation funding documents. The case did not discuss prepaid forward contracts.
Conclusion
Litigation is expensive and involves uncertainty. For clients and lawyers, litigation funding can help to reduce risk, albeit with a cost of funding that is usually commensurate with the degree of risk the funder is taking on. From a tax viewpoint, most recipients of funds want to delay the event of taxation, and to be sure that when they pay taxes, they are paying taxes on their net recoveries, not on any of the money that is being paid to the funder.
Properly structured, the unique prepaid forward purchase agreements typical in this context can achieve both goals. Funders like them too because the lawyers and plaintiffs they deal with want and expect these agreements, and because of the tax advantages that the funders and their investors can often achieve.
Consumer fraud is often described as a compliance issue, a consumer protection problem, or a law enforcement priority. Those descriptions are accurate, but they can make the problem sound abstract. Several government agencies, as well as nonprofits, in the United States educate, inform, and track consumer fraud, including the Federal Trade Commission (“FTC”), which maintains a Consumer Sentinel Network, a database of fraud reports made directly to the FTC as well as reports made to law enforcement agencies and the Better Business Bureau. This secure data is made available to law enforcement. An aggregated data file called the Consumer Sentinel Network Data Book (“Consumer Sentinel”) is published yearly containing fraud reports by type, state, consumer, etc., making the harm more concrete: consumers reported more than $12.5 billion in fraud losses in 2024 (the most recent year for which a data book has been released), and the Consumer Sentinel Network received 6.5 million reports across fraud, identity theft, and other consumer protection categories.[1] The data is especially useful for business lawyers because it shows where consumer-facing representations, digital contact methods, and payment pathways meet measurable financial harm.
This article uses the FTC’s public Consumer Sentinel data files to look at deceptive marketing and consumer fraud through a business-law lens.[2] The central point is simple: deceptive marketing is not limited to false advertising copy. In a digital marketplace, the consumer’s path to loss can begin with a social media message, website, app, phone call, email, text, or online advertisement. The legal risk is not only whether the first statement was misleading but also whether the full consumer pathway predictably moved people from contact to payment.
The Complaint Categories Show the Breadth of Consumer-Facing Risk
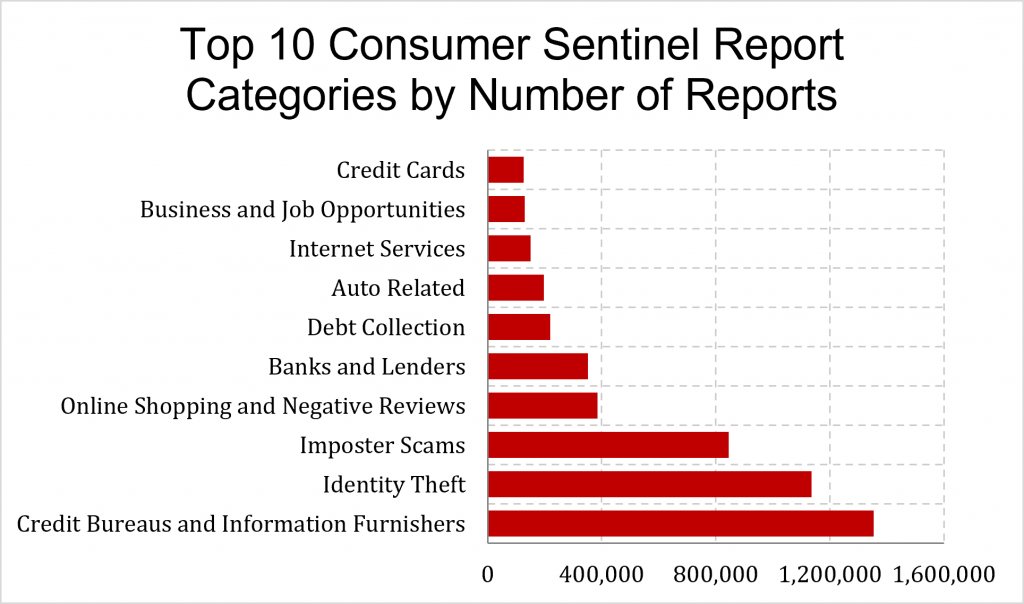
As shown in figure 1 below, the largest Consumer Sentinel report category is credit bureaus and information furnishers, with more than 1.35 million reports. Identity theft follows with more than 1.13 million reports, and imposter scams account for 845,806 reports. Online shopping and negative reviews, banks and lenders, debt collection, auto-related complaints, internet services, business and job opportunities, and credit cards round out the top ten categories. Those categories are not all “marketing” in the narrow advertising-law sense. But many involve the same basic commercial problem: consumers receive information, form trust, act on a representation, and sometimes suffer financial harm. The data shows that consumer protection risk appears across credit reporting, identity misuse, online purchasing, financial services, debt collection, job opportunities, and consumer credit.
Figure 1. Top 10 Consumer Sentinel Report Categories by Number of Reports, 2024
Credit bureaus and information furnishers, identity theft, and imposter scams were the top categories of Consumer Sentinel fraud reports in 2024.
The legal hook is familiar. Section 5 of the FTC Act declares unfair or deceptive acts or practices in or affecting commerce unlawful.[3] The FTC’s deception framework focuses on whether a representation, omission, or practice is likely to mislead consumers acting reasonably under the circumstances and whether it is material.[4] Consumer Sentinel data does not prove that every report is unlawful, but it helps identify areas where consumer-facing practices generate enough friction or harm to deserve legal attention.
Payment Method Is Where the Loss Becomes Real
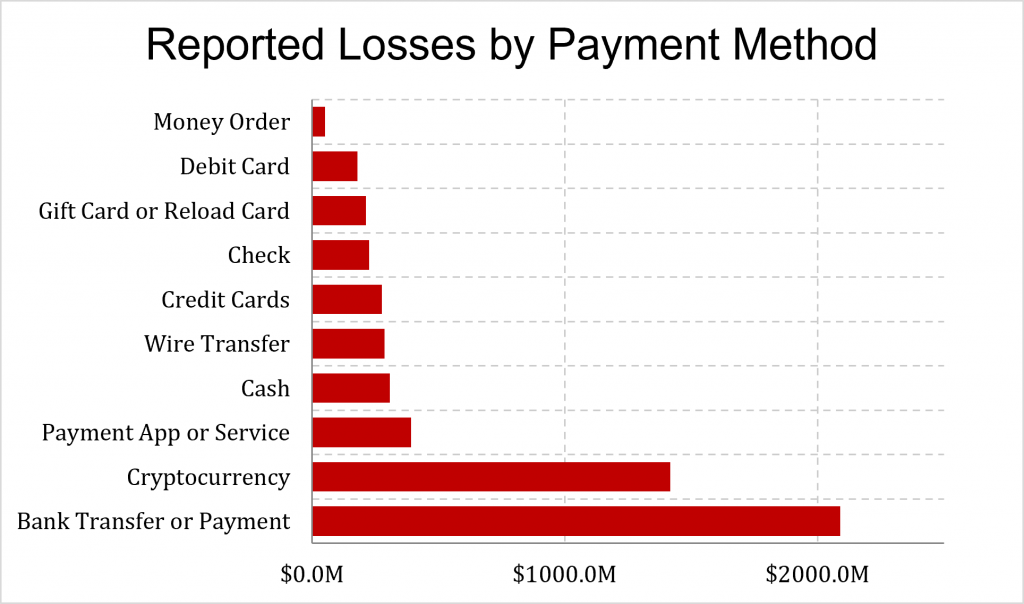
As shown in figure 2 below, in 2024, bank transfers or payments accounted for approximately $2.089 billion in reported losses, the largest payment category in the dataset. Cryptocurrency followed at approximately $1.417 billion. Payment apps and services accounted for approximately $391 million; cash, $308 million; wire transfers, $287 million; credit cards, $275 million; checks, $225 million; gift cards or reload cards, $212 million; debit cards, $180 million; and money orders, $51 million.
Figure 2. Reported Consumer Fraud Losses by Payment Method, 2024
Bank transfers or payments and cryptocurrency were the payment methods for the vast majority of consumer fraud losses in 2024 Consumer Sentinel data.
This ranking should matter to lawyers advising companies, platforms, financial institutions, fintech providers, and payment intermediaries. Consumer protection analysis often begins with the front end of the transaction: what was said, what was omitted, and whether the overall impression was misleading. The payment data shows that the back end of the transaction is just as important. Once money moves through a bank transfer, cryptocurrency transfer, wire transfer, payment app, or similar mechanism, recovery can be difficult.
The FTC has separately reported that consumers in 2024 lost more money to scams paid through bank transfers or cryptocurrency than through all other payment methods combined.[5] If a consumer-facing pathway uses urgency, impersonation, scarcity, or fear to move a person toward a hard-to-reverse payment method, the risk is not merely reputational; it becomes a financial-harm problem with legal consequences.
The Marketing Channel Is Often the Entry Point
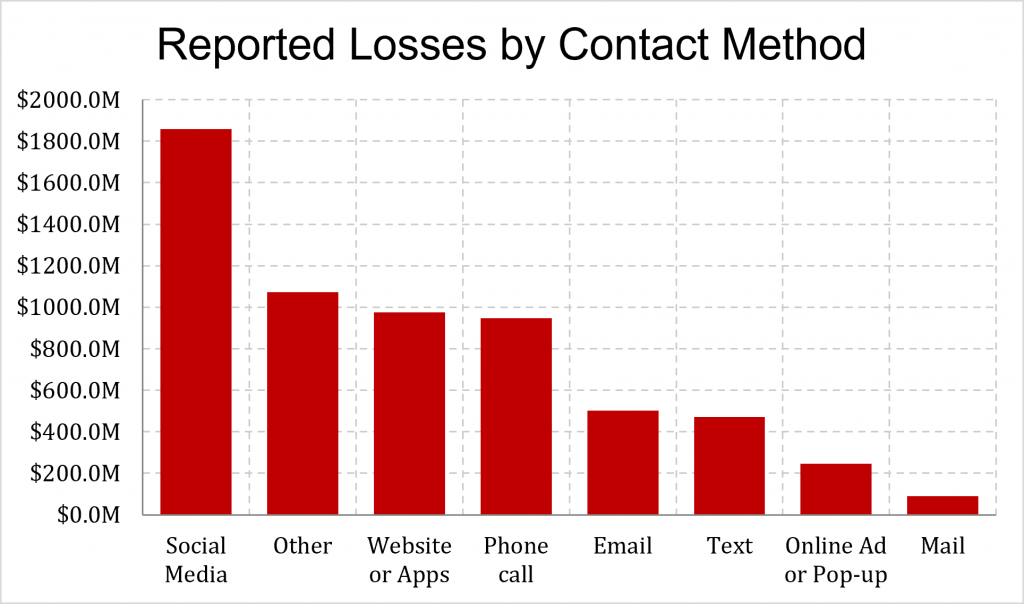
The contact-method chart, shown in figure 3, brings the marketing side into focus. Social media was associated with approximately $1.858 billion in reported losses, the highest amount among the listed contact methods. Websites or apps accounted for approximately $976 million; phone calls, $948 million; emails, $502 million; text messages, $470 million; online ads or pop-ups, $246 million; and mail, $90 million. The “other” category accounted for approximately $1.072 billion.
Deceptive marketing is nearly as old as marketing itself. The familiar image of the traveling snake-oil salesman reflects a long-standing form of commercial opportunism: taking advantage of limited information, consumer trust, urgency, or the difficulty of verifying a claim before a purchase is made. The basic strategy has not disappeared, but the delivery methods have changed. What once occurred through personal demonstrations, printed advertisements, or door-to-door sales can now be carried out through social media, websites, apps, text messages, and other digital channels.
From a marketing perspective, opportunism helps explain how legitimate tools of persuasion can be redirected toward deception. Scarcity, social proof, authority, personalization, and urgency can help consumers evaluate legitimate products, but they can also be used to discourage careful review or accelerate payment before a claim can be verified. Digital platforms increase the potential scale of that conduct by allowing a deceptive message to reach large numbers of consumers quickly, at relatively low cost, and with increasingly precise targeting.
Figure 3. Reported Consumer Fraud Losses by Contact Method, 2024
Social media was the contact method for almost $1.86 billion in consumer fraud losses in 2024, the highest amount of any contact method by far.
These numbers show that modern consumer fraud often begins in ordinary marketing environments. Cialdini’s Principles of Influence[6]describe several methods of influence widely used in the marketing environment, including reciprocity, social proof, and scarcity, that, while not necessarily illegal, do capitalize on consumers’ use of heuristics or mental shortcuts, resulting in purchasing decisions less than beneficial.
Other theories in the areas of cognition, decision-making, psychology, and sociology also help explain why consumers engage in faulty decision-making and fall prey to fraudulent activities. Social media, apps, websites, emails, texts, and online ads are not merely communication tools; they are consumer access points. A deceptive message on social media may not look like a traditional advertisement. A fake website may mimic a legitimate business. A text message may imply urgency. A phone call may create fear. Each channel can move a consumer closer to a financial decision.
That point aligns with the FTC’s concern over digital “dark patterns,” which the agency has described as design practices that can trick or manipulate consumers into buying products or services or giving up personal information.[7]Consumer Sentinel data does not measure dark patterns directly, but it supports the same broader concern: digital design, contact channels, and consumer decision-making cannot be separated from the legal analysis of deception.
The Harm Is Not Limited to One Age Group
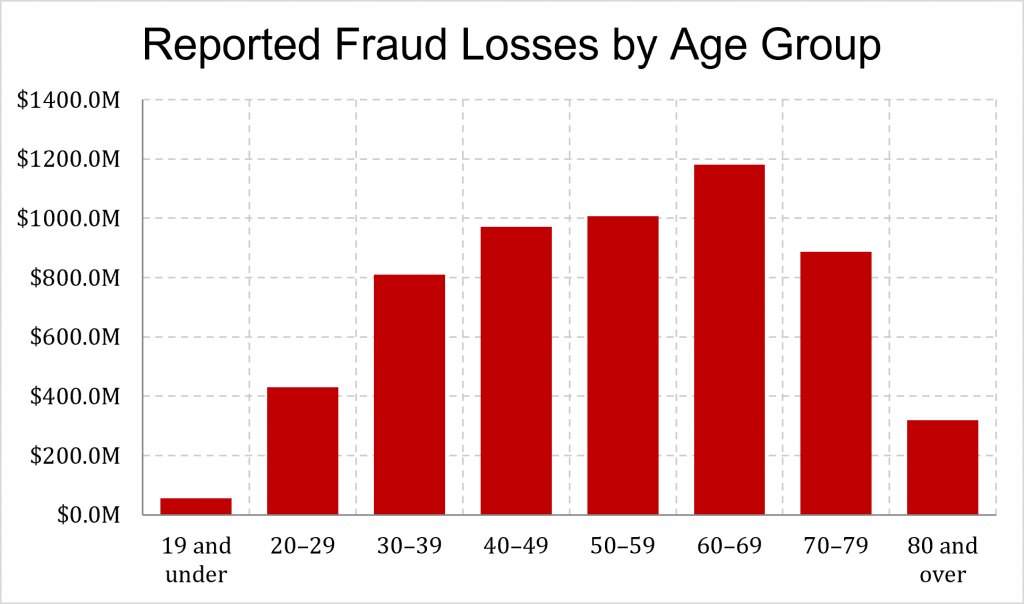
The age data shown in figure 4 complicates the simple narrative that consumer fraud is only a problem for one demographic group. Reported losses were highest among consumers ages sixty to sixty-nine, at approximately $1.18 billion. Consumers ages fifty to fifty-nine reported approximately $1.006 billion in losses, followed by ages forty to forty-nine, approximately $971 million; ages seventy to seventy-nine, approximately $887 million; ages thirty to thirty-nine, approximately $810 million; ages twenty to twenty-nine, approximately $430 million; ages eighty and over, approximately $319 million; and ages nineteen and under, approximately $55 million.
Figure 4. Reported Consumer Fraud Losses by Age Group, 2024
Consumer fraud is a problem for all age groups, with consumers in age groups 30–39 to 70–79 all reporting over $800 million in losses in 2024.
The chart does not prove why loss levels differ by age group. It may reflect differences in assets, savings, reporting behavior, channel exposure, scam type, or willingness to engage with certain communications. Still, the pattern is useful. It suggests that consumer education and compliance controls should not be generic. The warning needed for a twenty-five-year-old using payment apps and social media may not be the same warning needed for a sixty-five-year-old responding to a bank message, investment offer, technical support contact, or government imposter communication.
Geography Can Help Target Enforcement and Compliance
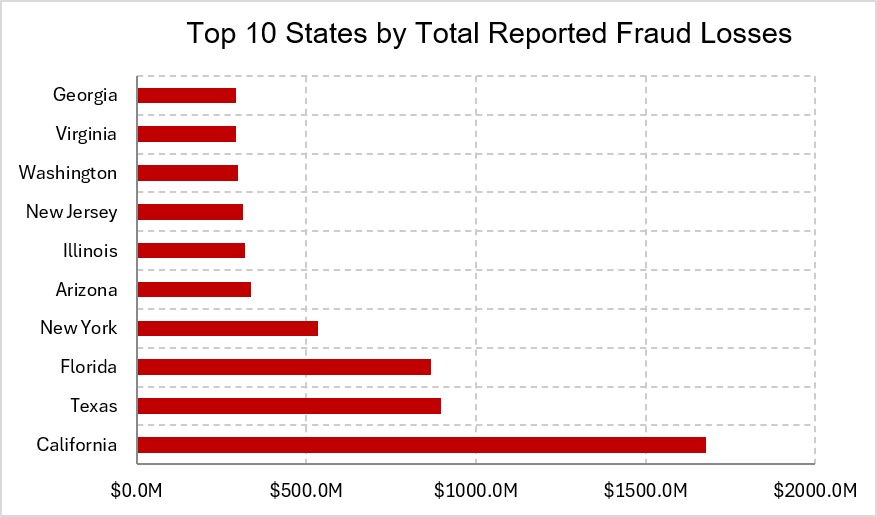
The state chart, shown in figure 5 below, shows the largest reported fraud losses in California, Texas, Florida, New York, Arizona, Illinois, New Jersey, Washington, Virginia, and Georgia. California alone accounted for approximately $1.679 billion in reported fraud losses. Texas reported approximately $898 million; Florida, approximately $866 million; and New York, approximately $534 million.
Figure 5. Top 10 States by Total Reported Consumer Fraud Losses, 2024
California, Texas, and Florida, the states with the largest populations, were the states with the most total reported consumer fraud losses in 2024.
Large states will naturally show large aggregate losses, so Table 1 below details per capita total fraud losses for each of the top ten aggregate state losses. State attorneys general, consumer protection offices, financial institutions, and national companies can use geographic data to decide where education, monitoring, and enforcement resources may be most needed. For corporate counsel, geographic concentration can be an issue-spotting tool. If a product, campaign, platform feature, or payment pathway generates disproportionate complaints or losses in a state, that pattern should trigger review.
Table 1: Per Capita Reported Fraud Losses in States with Largest Aggregate Losses, 2024
Consumer Sentinel data supports a simple framework for evaluating deceptive marketing and consumer fraud risk. First, ask how the consumer was reached. Second, ask what representation or impression was created. Third, ask how payment was requested or processed. Fourth, ask which consumers appear most exposed. Fifth, ask where the losses are concentrated. Those questions move the analysis from isolated advertising review to a broader review of the consumer journey.
This approach is useful because a social media message, website, app screen, text, phone call, or online ad may be only one part of the transaction. The more important question may be whether the full pathway creates foreseeable financial harm. That pathway can include the claim, the timing, the call to action, the payment method, the consumer segment, and the post-payment recovery process.
For corporate counsel, the lesson is operational. Advertising review, user-experience review, payment-risk review, complaint monitoring, and fraud prevention should not be separate silos. If the same consumer journey creates marketing conversion, payment movement, and complaint risk, it should be reviewed as one legal and business process. Consumer Sentinel data gives lawyers a way to explain that point to boards and executives in concrete terms: risk can be measured in reports, dollars, channels, payment methods, age groups, and states.
Conclusion
The most useful insight from the 2024 Consumer Sentinel data is not simply that consumer fraud exists—it is that the harm can be mapped in a way that business lawyers understand. The contact method shows how the consumer enters the funnel. The payment method shows how the loss occurs. The age and state data show who and where the harm affects. The report categories show the parts of the marketplace where consumer trust is breaking down.
That makes deceptive marketing a business law problem as much as a consumer protection problem. It involves legal representations, platform design, payment systems, compliance controls, customer trust, and measurable financial loss. The data does not establish liability in any individual case, but it does provide an early warning system. Public complaint data can help lawyers and businesses see where consumer-facing conduct is most likely to produce financial harm—and where compliance attention should go before the next enforcement action, lawsuit, or reputational crisis.
Fed. Trade Comm’n, Consumer Sentinel Network Data Book 2024 (2025). The FTC states that the 2024 data book is based on unverified reports filed by consumers, not a consumer survey. ↑
Id. data files (CSV files). The figures in this article are based on author analysis of the public data files. ↑
Annual Estimates of the Resident Population for the United States, Regions, States, District of Columbia, and Puerto Rico: April 1, 2020 to July 1, 2024 (NST-EST2024-POP), in Vintage 2024 National and State Population Estimates, U.S. Census Bureau (Dec. 2024). ↑
The Federal Trade Commission (“FTC”) announced on July 13, 2026, that it imposed penalties, totaling $12 million, in a failure-to-file settlement with Edwards Lifesciences Corp. (“Edwards”) and Genesis MedTech Group Limited (“Genesis MedTech”). The FTC complaint alleges that the companies violated the Hart-Scott-Rodino Act (“HSR Act”) when they closed an acquisition in July 2024 without submission of the required premerger notification and observation of the required waiting period. This enforcement action shows the FTC’s continued commitment to HSR Act compliance and its belief that substantial penalties are needed to deter parties seeking to avoid the HSR Act’s requirements.
The HSR Act requires parties of a certain size, contemplating transactions of a certain size, to notify both the FTC and the Department of Justice, Antitrust Division, and observe a waiting period (typically thirty days) before consummation. Relevant here, acquisitions of nonvoting securities are generally not reportable, and the value of nonvoting securities would not be included in the size-of-transaction threshold under the HSR Act. Advance notification of significant transactions, and adherence to the waiting period, provide the federal antitrust agencies with an opportunity to review and, when necessary, to seek an injunction to prevent the consummation of acquisitions that may substantially lessen competition. Currently, failure to make a filing carries penalties of up to $53,088 per day.
The regulations promulgated under the HSR Act make clear that the FTC will disregard “devices . . . employed to avoid” the obligation to make a filing. The FTC’s complaint alleges that the companies intentionally structured Genesis MedTech’s sale of its subsidiary to Edwards to avoid triggering a filing. Specifically, the FTC claims that Genesis MedTech would not accept a valuation below the then-applicable HSR threshold of $119.5 million, and alleges that Edwards did not want agency review to delay the transaction. The FTC alleges that the buyer contemporaneously purchased $25 million of Genesis nonvoting securities in order to reduce the valuation of the voting securities to below the HSR Act’s threshold.
Another factor in the instant case is the FTC’s successful challenge in January 2026 to Edwards’ attempted acquisition of another company in the same business as the Genesis MedTech subsidiary acquired by Edwards. The FTC alleges that this earlier unsuccessful acquisition was under consideration when Edwards proposed to Genesis MedTech its purchase of the nonvoting stock. The complaint also states that documents and testimony “show that . . . Edwards wanted to avoid filing under HSR.”
The parties settled for a combined $12 million. As part of the settlement, Edwards will also be subject to additional requirements, including prior notice for certain U.S. acquisitions for five years and maintenance of an antitrust compliance program.
FTC Chairman Andrew Ferguson warned, in the FTC’s press release announcing the settlement, that “[t]he FTC will be vigilant in enforcing the requirements of the Hart-Scott-Rodino Act and we will not hesitate to seek penalties for its violation.” Although allocation of purchase price to nonvoting securities can be entirely legitimate, doing so solely for the purpose of avoiding an HSR filing is not permitted under the regulations.
Noncompliance with the HSR Act continues to carry serious penalties, as fines continue to mount for each day that a party is in violation of the act. Even though the regulations task buyers with the responsibility for valuation, sellers should take great care when agreeing to structures or artifices that appear to avoid an HSR filing, particularly when the selling company will continue to exist post-closing and when the transaction could present substantive antitrust concerns. Importantly, some state “mini-HSR” statutes laws, including those in California (effective January 1, 2027), Colorado, and Washington also provide for their own “failure-to-file” penalties, up to $25,000 per day in California and up to $10,000 per day in Washington and Colorado. Consultation with experienced counsel early in a transaction and well in advance of any purchase agreement can assist with mitigating such risks.
The Department of Justice (“DOJ”), Antitrust Division, and the attorney general of Ohio notched a win with a recent settlement (Exhibit B: [Proposed] Final Judgment: U.S. and State of Ohio v. OhioHealth Corporation) barring an Ohio health care system from attempting to obtain any insurance contract provisions that prohibit, deter, prevent, or penalize steering.
In February, the DOJ and Ohio sued OhioHealth Corporation (“OhioHealth”), claiming that the health care system abused its market power by negotiating for contract provisions frequently referred to as “anti-steering” and “gag rules.” The complaint also alleges that OhioHealth requires an insurer that wants any of OhioHealth’s providers in its network to include all of OhioHealth’s providers in the network. The DOJ further claims that OhioHealth is the largest hospital system in Columbus, Ohio, and that the contracts it holds with commercial health insurers account for at least 85 percent of the commercial health insurance business in the Columbus area.
OhioHealth’s contracts allegedly “insulate it from price competition and help to maintain its extremely high prices” and violate Section 1 of the Sherman Act and Ohio’s Valentine Act, the state’s primary antitrust law, by blocking insurers from offering “health insurance plans that feature lower-cost hospitals and other providers and even from informing patients that lower-cost options are available.” The DOJ contends that patients are harmed by OhioHealth’s conduct because it “deprive[s] patients of a choice among a full spectrum of competitive health insurance plans, where patients could decide for themselves whether going to OhioHealth for care is worth the high prices it charges.”
While the complaint does not quote the contractual provisions at issue, it claims that they restrict several key features needed for budget-conscious health plans, including the following:
“Narrow network plans” that “include a relatively limited set of cost-effective providers”
“Tiered network plans” that allow members “to secure healthcare from the lower-priced favored tier of providers or to pay more for care from the more expensive tier of providers”
“Centers for excellence,” which payors can create by identifying “specific high-quality, cost-effective programs—such as orthopedic surgery or oncology programs—at specific providers and encourage their members to choose care at those facilities by reducing or waiving the fees that the patient must pay”
“Site of service steering,” which can save patients money by incentivizing them “to have procedures done in a lower-cost site of service”
“Reference-based pricing” that fixes reimbursement rates for certain procedures, “often pegged to some reference point like a market average price”
“Active transparency” by which payors share pricing information to help inform a patient’s choice of health care provider
The complaint pegged OhioHealth’s market share at only approximately 35 percent, despite the fact that courts typically require a market share of at least 40–50 percent in similar cases.
Though denied by OhioHealth, the DOJ claims that commercial health insurers attempted to negotiate with OhioHealth to remove these restrictive contract provisions, but OhioHealth consistently refused. The health system’s response to the agencies’ challenge was that it competes with two other hospital systems for patient volume by competing for favorable insurance contracts and that this “competition for the contract” occurs regularly when contracts expire or are rebid and results in lower prices and other benefits to consumers. OhioHealth also countered that, to the extent it negotiated favorable contracts, it did so by being a better health system with better prices and better services.
The DOJ has obtained much of its requested relief through the settlement, which:
Voids and prohibits the health system from seeking contract provisions that prohibit or deter steering or transparency, including:
Requirements of prior approval for the introduction of new plans; or
Requirements that OhioHealth be included in the most-preferred tier of plans, though it may seek to participate in the most-preferred tier of a plan.
Bars conduct that penalizes, or threatens to penalize, an insurer for steering members to other providers or providing rate transparency to its members.
Prohibits any contract provision that prohibits or deters steering or transparency, including by requiring inclusion in the most-preferred tier.
The settlement permits OhioHealth to participate in the most-preferred tier of a plan, but it must do so under the same terms and conditions as its competitors. If OhioHealth declines participation in the most-preferred tier, it must still participate in that plan on terms and conditions that are substantially the same as the terms and conditions of then-existing broad networks.
Two days after the settlement, the White House Council of Economic Advisers issued a report on health care pricing (Effects of Banning Anti-Competitive Hospital Contracts). The report concludes that prohibiting all-or-nothing, anti-steering, and anti-tiering contracting practices would save on health care costs by reducing “hospital and affiliated-physician prices by 18 percent (with a plausible range of 11 to 26 percent), averaging ~$4,100 per inpatient admission.” The report also estimates that employer plan premiums could likewise fall by roughly 6.5 percent in markets affected by such contracting provisions, which could yield national savings of roughly $45 billion per year.
Takeaways
The OhioHealth litigation, the White House Council’s report, and the DOJ’s recent lawsuit challenging some similar contracting practices of a New York hospital system all signal to health care providers with market shares as low as 30–35 percent that historically lawful negotiation strategies need to be reviewed. Neither the litigation nor the settlement appears to take into consideration the lower rates that providers often offer in exchange for the increased volume that these types of restrictions can generate.
The settlement does make clear that regardless of the purported market power of a health care system, it is still permitted to negotiate to participate in a most-preferred tier as long as it does so under the same terms and conditions as any other provider, and it is able to restrict steering within a narrow network where it is the most prominently featured provider. In addition, the settlement allows a provider to protect disclosure of its negotiated rates to competitors or the public and to challenge the dissemination of inaccurate information.
On February 20, 2026, the U.S. Supreme Court ruled that the tariffs implemented by executive order in early 2025 under the International Emergency Economic Powers Act (“IEEPA”) were illegal.[1] Shortly after, the U.S. Court of International Trade ordered the collected IEEPA tariff revenue to be reimbursed to the importers of record, who statutorily were responsible for paying the tariff duties.[2]
Even though the importers of record paid the tariff duties to U.S. Customs and Border Protection, depending on various factors, the cost of tariff duties may or may not have been passed on to others in the supply chain or to ultimate customers. The decision to reimburse importers of record for the tariff duties that they paid has triggered litigation by downstream purchasers of imported goods against importers of record seeking reimbursement for price increases allegedly tied to the now-defunct tariffs.
Pass-through of tariff duties will likely emerge as a key issue within this new wave of litigation. Did tariff-imposed cost increases lead to price increases down the supply chain to distributors and downstream customers and, if they did, does the variation in pass-through patterns require “mini-trials” instead of a class-wide approach?
Although the IEEPA context raises novel economic issues, economists have long analyzed these types of pass-through questions, including in the context of indirect purchaser claims and class certification in antitrust matters.
Litigation Pass-Through Considerations
Across diverse contexts—such as tariffs, exchange-rate movements, input-cost shocks, tax changes, and antitrust analysis—the economic literature consistently demonstrates that pass-through is a highly product-specific phenomenon that varies significantly across industries, products, and regions.[3] Studies find a wide range of pass-through rates,[4] indicating that quantification in IEEPA-related litigation is likely to be challenging and may show a high degree of variance.
Courts have closely reviewed the robustness of economic methodologies, including their handling of the relevant market structure, in reaching a variety of conclusions in cases involving pass-through. For example, in the antitrust context, courts have sometimes rejected pass-through models and denied indirect purchaser class certification, as seen in In re Graphics Processing Units Antitrust Litigation and In re Flash Memory Antitrust Litigation,[5] while in other cases courts have granted indirect purchaser class certification, such as in In re TFT-LCD (Flat Panel) Antitrust Litigation.[6] Pass-through rates are also contested in international trade proceedings: World Trade Organization (“WTO”) disputes and International Trade Commission (“ITC”) investigations often need to reach pass-through estimates when evaluating how tariffs, antidumping duties, or countervailing measures impact downstream domestic market prices.[7]
Purchaser Dynamics and Cost Pass-Through
Determining pass-through, if any, is fundamentally an empirical question. The actual scope of pass-through is dictated by the specifics of demand/supply conditions, market competition, and the mechanics of how a market operates. The extent of seller/buyer bargaining power, demand/supply elasticities throughout a product’s supply chain, and availability of substitutes can be critical determinants of cost pass-through. For example, in markets where consumer demand is relatively inelastic (i.e., low sensitivity to price increases) and there are no close substitutes, pass-through can be relatively high.[8] Conversely, if large downstream purchasers have high elasticity of demand and there are many substitutes (or many firms selling similar products), upstream suppliers may be forced to absorb the tariff costs into their own margins rather than passing them on.[9]
The extent of cost pass-through can often depend on the negotiating leverage of the buyer. For instance, direct purchasers or large institutional indirect purchasers—such as national retail chains or corporate distributors—may possess significant bargaining power.[10] This may allow them to push back on price increases, negotiate favorable rebates, or pressure suppliers into absorbing the increased costs. In contrast, individual retail consumers generally lack this bargaining power and usually must take prices as given. However, because these individual consumers can be highly price-sensitive, attempting to pass 100 percent of the cost increase down to the retail level might result in a sharp drop in consumer demand.[11] Consequently, retailers may be forced to absorb a portion of the margin hit rather than risk alienating their customer base.
The extent of cost pass-through also depends on the time horizon. In the short run, pass-through tends to be mostly incomplete.[12] At longer time horizons, other determinants of price can further complicate an analysis of pass-through: In response to sustained cost increases, suppliers can readjust supply chains, retailers can readjust purchasing plans, and consumers can adjust spending habits if prices increase.
To evaluate pass-through dynamics, economists rely on a variety of methods:
Regression models can estimate the relationship between upstream costs and downstream prices while controlling for other supply and demand factors that could influence the relationship. While flexible and generalized to multiple questions with moderate data requirements, these models are sensitive to specification choices and can be limited to estimating average effects rather than isolating effects for a single firm within an industry. They can also be limited in capturing detailed market structures, complex supply chains, and multiproduct firms.
Quasi-experimental designs, such as difference-in-differences, can estimate pass-through by comparing price changes of affected downstream products relative to price changes of similar but unaffected products. This approach requires that the product markets used as benchmarks are sufficiently similar to the market being evaluated in terms of demand, supply, and competitive conditions. In the context of IEEPA tariffs, finding an appropriate control group may be challenging given the economy-wide effects of tariffs.
Structural models, commonly used in merger reviews,[13] can be used to simulate the effects of a policy change such as tariffs on an industry or firm. These models allow economists to capture complex international supply chains and market structures, although this approach has high data requirements and can be sensitive to model parameters like elasticities and assumptions by the researcher. Structural models are also frequently employed to assess the impact of trade policies, including tariffs. For example, in WTO arbitration, economists use industry-specific structural models to quantify the effects of antidumping and countervailing duties, aggregated to the industry level.[14]
Tariff Pass-Through Complexities: Border Versus Retail
The context of international trade introduces distinct issues in pass-through estimation. The unprecedented scale of the IEEPA tariffs introduced rapid, exogenous shocks that may have caused shifts in supply chain bargaining power and dynamic adjustments in sourcing. Understanding how to adapt traditional empirical frameworks to account for these shifts can be critical for measuring downstream impact accurately. At a high level, tariff pass-through can be broken down into two main components: border pass-through and retail pass-through.
Border pass-through refers to the pass-through of costs imposed by tariffs to the importers of record. Depending on the product, market dynamics, and competitive pressure, foreign exporters might absorb a portion of the tariff costs by lowering their pre-tariff export prices, meaning that a portion of the economic cost of the tariff may be borne by exporters.[15]
Retail pass-through refers to the pass-through of the costs imposed by the tariffs from the importers of record to downstream purchasers of intermediate and final goods. Determining exactly which products are impacted by IEEPA tariffs at the consumer level is further complicated by inventory lag: Because retailers may hold stock that was imported prior to the tariff’s implementation date, there may be a significant delay before the cost of the tariff actually materializes in the broader market. The research into retail pass-through has shown high variability in rates between products and industries. There is little consensus on exact rates other than that retail pass-through appears to be mostly incomplete, with estimated pass-through rates covering a wide range.[16]
Other Empirical Challenges in Estimating Pass-Through of IEEPA Tariff Duties
Empirically estimating the pass-through of IEEPA tariffs poses even more unique complexities for economists, including other changes in tariff policy, tariff avoidance, and confounding macroeconomic factors.
Other changes in tariff policy: The IEEPA was not the only mechanism by which tariffs were enacted. For example, other tariffs were imposed around the same time as the IEEPA tariffs, such as Section 232 steel and aluminum tariffs and Section 301 China tariffs.[17] U.S. industries that rely on intermediate inputs subject to these tariffs may have experienced cost increases, which in turn may have influenced their pricing decisions. Economists would have to disentangle cost increases due to IEEPA tariffs from these other tariffs to assess their impact. For example, the U.S. automotive industry relies on imported parts that are subject to Section 232 and 301 tariffs, rules of origin requirements, and IEEPA tariffs, all of which impose separate costs that may be passed on to consumers.[18]
Tariff avoidance: Firms may engage in behavior that mitigates the high costs of IEEPA tariffs but increases costs for other reasons. IEEPA tariffs are country specific and vary widely, which may lead to diversion of sourcing to lower-tariff countries.[19] However, such production shifting may increase production or shipping costs. For example, Apple has started to move its iPhone production from China to India, which has relatively lower tariffs but may have higher labor and production costs.[20] Researchers will need to consider how much of price increases are due to tariffs versus increases in production and sourcing costs.
Confounding macroeconomic factors: Any evaluation of pass-through from IEEPA tariffs must account for shifting macroeconomic conditions to isolate the impact of the tariffs. For example, price changes due to tariffs must be untangled from global inflationary pressures and fluctuating exchange rates. Furthermore, the analysis must appropriately account for any concurrent policy interventions occurring in either the products’ country of origin or the U.S. to ensure an accurate assessment of price dynamics.
Conclusion
Across general academic research, litigation, and trade-specific analyses, the extent of pass-through is not clear and highly depends on specific circumstances. Pass-through issues will likely present a challenge to a class-wide approach in “double recovery” litigation.
The views expressed herein are those of the authors and do not necessarily reflect the views of Cornerstone Research.
Learning Res. Inc. v. Trump, No. 24-1287 (U.S. Feb. 20, 2026); Exec. Order No. 14257 (Apr. 2, 2025) (“Regulating Imports with a Reciprocal Tariff to Rectify Trade Practices That Contribute to Large and Persistent Annual United States Goods Trade Deficits”). ↑
Atmus Filtration Inc. v. United States, No. 26-01259 (Ct. Int’l Trade Mar. 4, 2026); Goodyear Tire & Rubber Co. v. U.S. Customs & Border Prot., No. 25-00498 (Ct. Int’l Trade Dec. 10, 2025); Costco Wholesale Corp. v. U.S. Customs & Border Prot., No. 25-00316 (Ct. Int’l Trade Nov. 28, 2025). ↑
Cavallo et al. found mixed evidence of retail pass-through of the 2018 tariffs across countries and products, including brand-level heterogeneity. Alberto Cavallo et al., Tariff Pass-Through at the Border and at the Store: Evidence from US Trade Policy, 3 Am. Econ. Rev.: Insights 19 (2021). Ganapati et al. found that 70 percent of energy input cost increases in the U.S. manufacturing industry are passed through to consumers. Sharat Ganapati, Joseph Sharpiro & Reed Walker, Energy Cost Pass-Through in U.S. Manufacturing: Estimates and Implications for Carbon Taxes, 12 Am. Econ. J.: Applied Econ. 303 (2020). Lillard and Sfekas found cigarette prices increased by more than the sum of federal and state taxes and escrow payments. Dean R. Lillard & Andrew Sfekas, Just Passing Through: The Effect of the Master Settlement Agreement on Estimated Cigarette Tax Price Pass-Through, 20 Applied Econ. Letters 353 (2013). ↑
Cavallo et al. found pass-through rates of the 2025 tariffs to be between 14 and 20 percent. Alberto Cavallo, Paola Llamas & Franco Vazquez, Tracking the Short-Run Price Impact of U.S. Tariffs (Nat’l Bureau of Econ. Rsch., Working Paper No. 34496, 2025). Flaaen et al. found tariff pass-through to consumers from wine tariffs to be over 100 percent. Aaron Flaaen et al., Who Pays for Tariffs Along the Supply Chain? Evidence from European Wine Tariffs (Nat’l Bureau of Econ. Rsch., Working Paper No. 34392, 2026). ↑
In re Graphics Processing Units Antitrust Litig., 253 F.R.D. 478 (N.D. Cal. 2008); In re Flash Memory Antitrust Litig., No. C 07-0086 SBA (N.D. Cal. June 9, 2010); see also Rachel Slajda, 9th Circ. Nixes Cert. Appeal in Toshiba Antitrust Action, Law360 (June 30, 2011). ↑
In re TFT-LCD (Flat Panel) Antitrust Litig., 935 F. Supp. 2d 1107 (N.D. Cal. Mar. 29, 2013) (MDL No. 1827). ↑
See, e.g., Lillard & Sfekas, supra note 3; E. Glen Weyl & Michal Fabinger, Pass-Through as an Economic Tool: Principles of Incidence Under Imperfect Competition, 121 J. Pol. Econ. 528 (2013). ↑
Rubens found evidence of a monopsonistic Chinese tobacco market and cited to other examples of vertically structured industries with buyer power, like book publishing and beef processing in the U.S. Michael Rubens, Market Structure, Oligopsony Power and Productivity, 13 Am. Econ. Rev. 2382 (Sept. 2023). ↑
Weyl and Fabinger showed that the pass-through rate is determined by the relative elasticity of supply and demand, where higher elasticity of demand would lead to a decrease in pass-through. Weyl and Fabinger, supra note 8. ↑
See, e.g., Justin McCrary & Daniel L. Rubinfeld, Measuring Benchmark Damages in Antitrust Litigation, 3 J. Econometric Methods 63 (2014); Daniel L. Rubinfeld, Quantitative Methods in Antitrust, inIssues in Competition Law and Policy 723 (ABA Section of Antitrust Law 2008). ↑
World Trade Org., supra note 7. The U.S. International Trade Commission uses similar models to quantify the impact of trade policies in fact-finding investigations for the executive branch and Congress. SeeU.S. Int’l Trade Comm’n, USMCA Automotive Rules of Origin, supra note 7; U.S. Int’l Trade Comm’n, Rice: Global Competitiveness, supra note 7. ↑
Amiti et al. found that border pass-through rates of the 2025 U.S. tariffs average between 86 and 94 percent, depending on the time period. Mary Amiti et al., Who Is Paying for the 2025 U.S. Tariffs?, Liberty St. Econ. (Feb. 12, 2026). Gopinath and Neiman similarly found pass-through rates of the 2025 U.S. tariffs to be between 80 and 100 percent. Gita Gopinath & Brent Neiman, The Incidence of Tariffs: Rates and Reality (Nat’l Bureau of Econ. Rsch., Working Paper No. 34620, 2026). ↑
Cavallo et al. found average pass-through rates of the 2025 tariffs to be between 14 and 20 percent. See Cavallo et al., supra note 4. Flaaen et al. found tariff pass-through to consumers from wine tariffs to be over 100 percent. See Flaaen et al., supra note 4. ↑
U.S. Int’l Trade Comm’n, USMCA Automotive Rules of Origin, supra note 7. ↑
Aaron Flaaen, Ali Hortaçsu & Felix Tintelnot, The Production Relocation and Price Effects of US Trade Policy: The Case of Washing Machines, 110 Am. Econ. Rev. 2103 (2020). ↑
Cell phone location data and location history are usually turned on by most cell phone users. In a recent U.S. Supreme Court decision, the Court considered how the Fourth Amendment applies to a geofence warrant requesting cell site location information (“CSLI,” i.e., cell phone location data and location history).
In its June 29, 2026, decision in Chatrie v. United States, the Court commented on the ubiquitousness of cell phones: “Modern cell phones, we observed a dozen years ago, are ‘such a pervasive and insistent part of daily life that the proverbial visitor from Mars might conclude they were an important feature of human anatomy.’”[1] These mobile technological wonders (which many people take for granted because of how they have become so integrated into their daily lives) collect and store a tremendous amount of detailed information about their owners’ lives. Some of that information is stored locally on the phone, and some in the “cloud” (e.g., the remote physical servers owned by the provider(s) of the location service functionality).
There are a lot of good reasons why most users activate location data and location history on their cell phones. This includes, without limitation, use of location-based functionalities on the phone such as using mapping/directions services, real-time updates on your daily commute, relevant location information of services near your location, and awareness of the location of loved ones who have consented to your knowing their location.
In Chatrie, local police in Virginia were trying to solve a crime involving a man robbing a credit union. As described in the syllabus, the police “learned from witness interviews and surveillance footage that the robber had approached the credit union from a corner of an adjacent church while appearing to talk on a cell phone, but they could not find out anything more, and the robber remained at large.”[2] The police applied to the local court for a geofence warrant directed to Google requesting CSLI within a certain radius of the credit union (the geofence) that Google collects through its Location History service, and described a three-step process that the police would follow: “[S]tep one, Google would produce anonymized location data for all cell phones within the geofence 30 minutes before to 30 minutes after the robbery; at step two, officers would attempt to narrow the list, and Google would provide additional anonymized data for that narrowed list, consisting of cell-phone locations both inside and outside the geofence during a two-hour period surrounding the robbery; and at step three, officers would further narrow the list, and Google would turn over identifying information, including names and phone numbers, for users on the final list.”[3] Based on that process, the federal government charged Okello Chatrie, petitioner, one of the individuals identified through that process, with committing the crime.
The Court was asked to consider whether the Fourth Amendment applied to (1) the use of a geofence warrant as described in the Court’s decision and, if so, (2) whether the search was reasonable given the features of the warrant they employed. The Court answered the first part of the question by holding that the police conducted a search when they gained access to Location History data, stating, “An individual has a reasonable expectation of privacy in records about his cell phone’s location, and police intrude on that constitutionally protected interest when they demand the information—even though for only a limited time, and from a third-party tech company.”[4] The Court stated further “The Fourth Amendment applies, too, when officials tap into Google’s ‘database of physical location information.’ Ibid. That database is new, but the principle covering it is not: That principle is instead the one our history has given.”[5] For the second part of the question (whether the search was reasonable given the warrant issued), the Court remanded to the Court of Appeals to determine whether the warrant issued and each of its steps were properly described with particularity and found to be supported by probable cause.
The bottom line is that the Fourth Amendment protects “against unjustified governmental intrusion on the privacy of the individual.”[6] The determination as to whether the search is reasonable depends on the facts. Nevertheless, the individual cell phone owner should read the fine print of agreements pertaining to cell phone location data and location history and knowingly exercise their freedom to choose whether to turn on or off that (and any other) cell phone functionality.
Chatrie v. United States, No. 25-112, 2026 U.S. LEXIS 2878 (U.S. June 29, 2026) (citing Riley v. California, 573 U.S. 373, 385 (2014)). ↑
The fiduciary duties of the board of directors form the cornerstone of corporate governance in the United States and most common-law jurisdictions. These duties are primarily comprised of the duty of care, the duty of loyalty, and, increasingly, the duty of good faith. Directors are legally obligated to act in the best interests of the corporation and its shareholders, exercising their responsibilities with diligence, prudence, and integrity. The legal framework governing these duties is largely shaped by state corporate statutes—most notably the Delaware General Corporation Law (“DGCL”)—and an evolving body of case law that interprets and enforces these obligations.
Duty of Care
The duty of care requires directors to make informed decisions after reasonable inquiry, relying on adequate information and deliberation. Courts typically apply the “business judgment rule,” which presumes that directors acted in good faith and in the best interests of the corporation unless there is evidence of gross negligence or misconduct. Directors are expected to stay apprised of material facts, consult with experts when necessary, and actively participate in board meetings. Failure to meet the duty of care can result in personal liability if harm to the corporation or its shareholders occurs as a result.
Duty of Loyalty
The duty of loyalty obligates directors to place the corporation’s interests above their own personal interests, avoiding conflicts of interest and self-dealing. Directors must disclose any potential conflicts and recuse themselves from decisions where their impartiality may be compromised. Breaches of the duty of loyalty are treated seriously by courts, often resulting in heightened scrutiny and potential liability. The duty of loyalty has been extended to encompass not only direct conflicts but also situations where directors may be influenced by relationships or affiliations that could impair their independent judgment.
Duty of Good Faith
Although often considered a subset of the duty of loyalty, the duty of good faith has emerged as a distinct fiduciary obligation. Directors must act with honesty and integrity, eschewing actions taken with improper motives or intent to harm the corporation. Courts have held that intentional dereliction of duty or conscious disregard for responsibilities can constitute a breach of good faith, giving rise to liability even in the absence of self-interest or negligence.
Balancing Risk, Reputation, and Long-Term Value
Modern corporate governance increasingly demands that boards of directors balance risk management, reputational concerns, and the pursuit of long-term value. Directors are expected to implement robust risk oversight mechanisms, identify and mitigate material risks, and foster a culture of compliance throughout the organization. This includes financial, operational, regulatory, cyber, and environmental risks, among others. The board’s role is not to eliminate risk but to ensure that risk-taking aligns with the corporation’s strategic objectives and risk appetite.
Reputation management has become a critical component of fiduciary duty, as public perception and stakeholder expectations can significantly impact corporate value. Directors must monitor and respond to reputational threats, including those posed by social, environmental, and governance (“ESG”) issues. Effective communication, ethical conduct, and responsiveness to stakeholder concerns are essential to safeguarding the corporation’s reputation and sustaining trust in the marketplace.
The pursuit of long-term value requires directors to look beyond short-term financial performance and consider the sustainability of corporate practices. This involves integrating ESG factors into decision-making, assessing the impact of corporate actions on employees, communities, and the environment, and promoting innovation and adaptability. Courts have recognized that boards may legitimately consider long-term interests and broader stakeholder impacts, so long as these considerations ultimately serve the best interests of the corporation and its shareholders.
Legal Trends and Practical Guidance
Recent legal developments emphasize the importance of board oversight and proactive engagement. Directors are increasingly held accountable for failures in risk oversight, particularly in areas such as cybersecurity, regulatory compliance, and crisis management. Shareholder activism and litigation have expanded the scope of potential liability, making it imperative for boards to document their decision-making processes, seek expert advice where appropriate, and maintain transparent communication with stakeholders.
In practice, boards should regularly review and update governance policies, establish clear protocols for managing conflicts of interest, and ensure that directors possess the necessary expertise and independence. Training and education on fiduciary duties, risk management, and evolving legal standards can help directors fulfill their obligations and adapt to changing expectations. Ultimately, balancing risk, reputation, and long-term value is a dynamic process that requires vigilance, integrity, and a commitment to ethical leadership.
This article is related to a CLE program that took place during the ABA Business Law Section’s 2026 Spring Meeting. To learn more about this topic, listen to a recording of the program, free for members.
The views and opinions expressed in this article are solely the author’s own and are presented in the author’s personal capacity. They do not necessarily reflect the views, positions, or policies of the author’s employer or any organization with which the author is affiliated.
Sources
Del. Code Online, tit. 8, § 141 (Board of directors; powers; number, qualifications, terms and quorum).
In a ruling handed down on November 26, 2025,[1] the Commercial Chamber of the French Cour de Cassation (Supreme Court for Judicial Matters) held that an abuse of power (abus de pouvoir) by a corporation’s board of directors may result in the board’s decisions being declared null and void. Although it did not find that such an abuse of power was established in the case before it, the French supreme court nevertheless formally recognized a new ground for nullity in corporate law. This development aligns with the well-established principle of corporate veil and serves as a reminder that the company’s interest must always guide decision-making within corporations.
Case Facts
A French société anonyme (public limited liability company) operated a casino under a public service delegation agreement and owned the buildings in which the casino was located. As the agreement was coming to an end, the company’s board of directors concluded that the corporation faced a risk of losing the buildings, as they could potentially be classified as “reversion assets” belonging to the public domain. To mitigate this risk, the board decided to separate ownership of the real estate from the operation of the casino. Acting on this decision, the company did not apply for renewal of the service contract for the casino and instead leased the premises to a newly incorporated “sister” company specially set up by the majority shareholder, which was subsequently awarded the new public service delegation by the municipality.
Minority shareholders contended that the board’s decision effectively caused the corporation to relinquish a profitable line of business in favor of a newly formed entity controlled exclusively by the majority shareholder. On this basis, they initiated litigation against the corporation and its controlling shareholder, seeking annulment of the corporate decision and related agreements on the ground of abuse of majority power.
Statement of Principle
The court set forth the following principle:
[I]n accordance with Article 1833 of the French Civil Code, a decision of the board of directors of a limited company may be declared null and void for abuse of power only if it is demonstrated that such decision is contrary to the company’s interests and was taken for the exclusive benefit of members of the board of directors or any other specific person, in particular shareholders. The existence of an abuse of power is assessed as of the date on which the challenged decision was made.[2]
In this case, the Commercial Chamber dismissed the appeal, declining to find that abuse of power had occurred. Even though the restructuring adopted by the board resulted in lower corporate profits and benefited the controlling shareholder, it was not demonstrated that the decision was contrary to the corporation’s interest, since it enabled the company to protect a strategic asset.
Scope of the Ruling
This ruling establishes a new ground for declaring corporate decisions null and void. The scope of the ruling extends beyond the mere board of directors of the French société anonyme. The broadened reach of the abuse-of-power doctrine therefore calls for heightened vigilance from corporate managers and their advisers, including where decision-making rules are governed by shareholder agreements or voting agreements. However, the concept remains difficult to establish in practice, as the case at hand illustrates. While the court’s confirmation that an abuse of power may give rise to nullity is unsurprising, the decision raises significant questions, particularly in light of the recent legislative reform governing the nullity of corporate decisions under French law.
Definition of Abuse of Power in a Board of Directors: Substantive Conditions and Terminology
In this ruling, the Cour de Cassation draws on terminology from criminal law[3] to establish a new concept, as evidenced by the extensive publicity given to its decision. The ruling’s statement of principle clearly sets out two cumulative conditions for a board decision to be characterized as abusive. The decision must be
contrary to the corporation’s interest (intérêt social); and
taken for the exclusive benefit of certain persons, such as directors or shareholders.
This definition is close to that of the concept of abuse of majority power (abus de majorité), though it is not identical.
Abuse of Majority Power
In the well-known principle laid down in the judgment of April 18, 1961,[4] the court defined the conditions required to characterize an abuse of majority power: a decision taken (i) for the exclusive benefit of the majority shareholder, (ii) to the detriment of the company’s interest.
In the past, French case law has used the concept of abuse of majority power to examine decisions made by a board of directors,[5] or even by a noncollegial body such as a managing partner,[6] and determine whether such decisions should be declared null and void.
In substance, the conditions for abuse of power closely parallel those of abuse of majority power. It should be noted that the claimants actually brought their case on the basis of an alleged abuse of majority power.
Abuse of Power: Clarifying the Terminology
The terminological distinction between abuse of majority power (abus de majorité) and abuse of power (abus de pouvoir) reflects the need to differentiate between decisions made by a board of directors and decisions made by shareholders. Accordingly, abuse of power refers to a decision taken in the interests of “specific persons,” with board members cited first among them.
As stated in the explanatory note to the judgment, directors “are not, legally speaking, the representatives of the shareholders who appointed them”;[7] they must exercise their mandate in the interests of the company and not in the interests of shareholders,[8] with the legal entity acting as a buffer between the board and the shareholders.
Beyond a terminological clarification, the court appears to confirm the view that directors are vested with a specific “power,” the abuse of which may lead to judicial sanction.[9]
Date of Assessment of the Abuse of Power
The court further clarifies that the abuse of power is assessed as of the date on which the challenged decision was made. This distinction is significant because it precludes the court from considering the actual consequences of the alleged abusive decision when determining whether an abuse of power occurred.
The Broad Scope of Abuse of Power: Vigilance Needed
Applicability to Other Corporate Forms
The ruling was rendered in relation to decisions made by the board of directors of a société anonyme. However, the court’s decision to provide extensive publicity for the judgment suggests that its scope may go beyond this specific context. Substantively, the reference to Article 1833 of the French Civil Code, a provision falling under the section known as “common corporate law,” reinforces the idea that the ruling on abuse of power could apply to all types of corporations.[10]
Extending Abuse of Power to Other Corporate Bodies
This shift from abuse in the exercise of a shareholder’s voting rights to abuse in the exercise of powers attached to a corporate function suggests that abuse of power could extend to all corporate bodies, whether collegial or not. Accordingly, it could apply to the decisions made by the president of a simplified joint stock company (société par actions simplifiée) or the manager of a limited liability company (société à responsabilité limitée).
Ultimately, abuse relates to the exercise of power by any corporate officer, regardless of the legal form of the corporation.
Abuse of Power: No Contractual Avoidance
The likely mandatory nature of this prohibition should serve as a warning to practitioners. Indeed, nothing appears to allow directors, or the shareholders who appoint them, to contractually shield themselves from the risk of a decision being characterized as an abuse of power. This is particularly relevant to shareholder agreements, which often reserve special rights for certain shareholders within management bodies, such as the boards or committees of sociétés par actions simplifiées, whose functions are similar to those of the board of directors of a société anonyme. It is also relevant to individual commitments, voting agreements, etc.
As such, it appears that the contractual agreements among shareholders, whose primary purpose is to protect the company itself, may not prevent a decision from being challenged as an abuse of power. A corporate decision may be challenged on the grounds of abuse of power if it meets both required conditions, even if it complies with the provisions of a shareholder agreement.
Challenges in Establishing the Concept on the Merits
Judicial Reluctance to Recognize Abuse of Majority Power
An examination of case law shows that it is rare for courts to find abuse of majority power[11] and to declare corporate decisions of a shareholder’s meeting null and void on that basis. This reluctance can be explained by the principle that judges should not interfere in the natural affairs of a company. Considering that this case addresses the validity of a decision by a management body (rather than a general meeting), one could expect even greater judicial caution.
The case at hand illustrates precisely the difficulty plaintiffs face in having abuse recognized in the context of a decision adopted by a director.
In this case, the contemplated restructuring involved ending the direct operation of the casino by the corporation that owned the premises—due to the risk to the real estate ownership—and entrusting the operation to a corporation wholly owned by the majority shareholder. The project, which was adopted by the board of directors within the framework of related party transactions, was clearly in the interests of the controlling shareholder. However, its objective was to preserve the company’s strategic real estate assets. Therefore, in the eyes of the judges, abuse of power was not established as the decision did not go against the company’s interests.
Practical Challenge: Should Any Reference to a Majority Be Abandoned?
Through its choice of the term abuse of power, the Cour de Cassation shifted the focus away from the notion of a majority and toward the exercise of an individual director’s prerogatives. In this case, it was the misuse of these prerogatives that the court sought to sanction.
Does this mean that reference to a majority is no longer necessary? That does not appear to be the case since, without the support of a majority, a collective body cannot adopt a resolution. The question of calculating a majority therefore remains in practice when assessing abuse of power. For the purpose of this calculation, the court appears to apply an individualized vote-counting approach, i.e., one vote per director.
Yet, it is legitimate to consider the board’s specific composition. For example, how should the majority of votes be calculated on a board composed partly of independent directors and/or of employee representatives? And what if the directors were pursuing their own separate interests while adopting the same resolution?
Defining the Scope of Nullity
A New Ground for Nullity Without a Statutory Basis
While rejecting the plaintiff’s arguments, the judges affirmed that a decision taken by company directors or officers could be declared null and void where an abuse of power is established. This outcome comes as no surprise, as it is consistent with prior case law related to abuse of majority power.[12] In both cases, the decision may be declared null and void without a specific statutory provision.
Abuse of Power and Reform of the Rules Governing Nullity
Although the decision was rendered under the legal framework in force prior to the entry into force of Order No. 2025-229 of March 12, 2025, which reformed the rules governing nullity of corporate decisions, nothing appears to prevent the sanction from being applied to corporate decisions under the new regime.
That said, applying the “triple test” under Article 1844-12-1 of the French Civil Code regarding the nullity of a corporate decision challenged for abuse of power raises legitimate questions:
In its preliminary review of an alleged abuse of power, the judge will have to verify, in particular, that “the consequences of nullity for the company’s interests are not excessive, as of the date of the ruling, compared to the harm to the interests it is meant to protect.”[13] Where abuse of power is established, could the judge refuse to declare the decision null and void, on the grounds that doing so would disproportionately harm the company’s interests at the time the sanction is pronounced, even though the challenged decision itself impaired those very interests at the time it was taken?
What about chains of nullities? Could a judge limit the effects of the nullity of a decision for abuse of power, in accordance with the discretionary power granted under Order No. 2025-229 of March 12, 2025?
Irrespective of how these questions may ultimately be settled by future case law, directors and officers are bound to ensure that their decisions are made solely in the interest of the company, without favoring any third party, be it shareholders or directors. The corporate interest must remain the abiding compass guiding all decision-making within the company.
The term abuse of power is not new as such. It is used to refer to several criminal offenses, including those attributable to company directors who, “in bad faith, make use of the powers they possess or the votes they hold in that capacity in a manner they know to be contrary to the interests of the company, for personal gain or to benefit another company or undertaking in which they have a direct or indirect interest.” Code de commerce [C. com.] [Commercial Code] art. L. 242-6 (Fr.). ↑
Cass. com., Apr. 18, 1961, Bull. civ. III, No. 175. The principle states that “there is abuse of majority when a resolution has been taken contrary to the general interest and with the sole aim of favoring the members of the majority to the detriment of those of the minority.” ↑
For an example of refusal to annul a board decision on the grounds of abuse of majority, see Cass. com., Feb. 24, 1975, No. 73-14.141. ↑
According to established doctrine, the prerogatives granted to company directors are based on authority whose misuse must be sanctioned. See, in this regard, Gérard Cornu, Preface to Emmanuel Gaillard, Le pouvoir en droit privé (Economica 1985). ↑
In this regard, see B. Dondero, Note on Cass. com., Nov. 26, 2025, No. 23-23363, JCP E 2025, 1345, FS-BR. ↑
See, for example, the refusal to characterize an abuse of majority power in the case of a merger. Cass. com., June 3, 2003, No. 99-18707. ↑
Nullity confirmed in the context of abuse of majority power in relation to compulsory distribution of profits. See Cass. 3e civ., Feb. 7, 2012, No. 10-17.812, F-D. ↑
This article examines a rapidly emerging wave of litigation targeting data centers on environmental, land use, nuisance, tort, and civil rights grounds and the mass tort, personal injury, and property damage claims likely to follow.
Background
The AI boom has fueled an unprecedented expansion of data centers—particularly “hyperscalers” consuming over one hundred megawatts of continuous power. As these facilities proliferate, they have drawn opposition from local residents, environmental groups, and the “Not In My Backyard” (“NIMBY”) movement, which has begun organizing community groups specifically to oppose data center development.[1] The result is a new and growing class of litigation bringing environmental, land use, nuisance, tort, and civil rights claims against data center projects.
Current Litigation Landscape
Since late 2024, lawsuits challenging data center development have increased across the country. The claims generally fall into four categories: zoning and environmental review challenges, transparency and open-records claims, nuisance and property damage claims, and Clean Air Act and emissions claims.
Zoning and Environmental Review Challenges
Beginning with Coalition for Responsible Data Center Development v. City of Farmington (December 2024), communities have challenged the approvals of data center construction.[2] The Minnesota Center for Environmental Advocacy alone filed four separate actions in 2025 alleging cities bypassed mandatory environmental review.[3] Similar zoning challenges have since been filed in California, West Virginia, New York, South Carolina, Georgia, North Carolina, and Kentucky, collectively targeting facilities ranging from 147 acres to 1,845 acres.[4]
Transparency and Open-Records Claims
A separate line of cases targets the alleged secrecy surrounding data center approvals. In Wisconsin, Midwest Environmental Advocates sued the Public Service Commission for refusing to disclose electrical load data for Meta’s AI campus.[5] In Missouri, residents filed a twelve-count Sunshine Law complaint alleging that city officials held private briefings and released a twenty-nine-page development agreement on a Friday for a vote the following Monday.[6]
Nuisance and Property Damage Claims
Post-construction claims have also emerged. In Newsom & Central VA Marine v. Amazon Data Services, plaintiffs allege that an Amazon data center caused brown water, diminished air quality, excessive noise, and constant blue light flashes.[7] In Oregon, Amazon paid $20.5 million to settle a class action alleging nitrate contamination of a county’s sole drinking water source.[8]
Clean Air Act and Emissions Claims
In a landmark April 2026 case, the Southern Environmental Law Center filed a Clean Air Act citizen suit on behalf of the NAACP against Elon Musk’s xAI, alleging that twenty-seven unpermitted gas turbines powering its Memphis-area data center have the potential to emit over 1,700 tons of nitrogen oxides, 19 tons of formaldehyde, and 180 tons of fine particulate matter annually—in an area already graded “F” for ozone pollution. The NAACP seeks injunctive relief and civil penalties of up to $124,426 per day of violation.[9]
Future Litigation Risks
Data center litigation is still in its infancy, but the claims are likely to escalate. Plaintiffs will almost certainly bring noise and light pollution claims—some residents near data centers claim a pervasive “high-pitched whine” that deters them from going outside.[10] Health-related personal injury claims are also probable, as some research links chronic noise and light exposure to hearing loss, insomnia, and diminished quality of life.[11] Nuisance, mass tort, and class action claims alleging personal injury, property damage, and/or natural resource damages from land temperature increases and contamination of surface water and groundwater from cooling water discharge represent a significant emerging risk.[12] Some research indicates that data center cooling-tower discharge may contain concentrated salts, corrosion inhibitors, biocides, heavy metals, and potentially per- and polyfluoroalkyl substances (“PFAS”). A separate study using NASA satellite data found that data centers may raise surrounding land temperatures by an average of 3.6°F—with extreme cases reaching 16.4°F—affecting over 340 million people globally.[13]
Economic harm claims—driven by the increased electricity and water demand that data centers impose on local infrastructure—are also likely to follow, with one report projecting $225 in additional annual electric costs per household in affected communities.[14] Given these increased costs, plaintiffs are likely to bring claims under utility statutes,[15] or under consumer protection statutes alleging unfair trade practices through shifting of infrastructure costs to ordinary customers.[16] A recent complaint filed before the Federal Energy Regulatory Commission (“FERC”) alleging that data centers unjustly shift electricity costs to consumers is an early indicator of the nature of these potential claims.[17]
Complaint ¶ 35, Coal. for Responsible Data Ctr. Dev. v. City of Farmington, No. 19HA-CV-24-5838 (Minn. Dist. Ct., Dakota Cnty. filed Nov. 29, 2024); Our Story, Coal. for Responsible Data Ctr. Dev. (last visited Mar. 17, 2026). ↑
Complaint, Minn. Ctr. for Env’t Advoc. v. City of Hermantown, No. 69DU‑CV‑25‑3448 (Minn. Dist. Ct., St. Louis Cnty. filed Nov. 5, 2025); Complaint, Minn. Ctr. for Env’t Advoc. v. City of Pine Island, No. 25-CV-25-2298 (Minn. Dist. Ct., Goodhue Cnty. filed Oct. 16, 2025); Complaint, Minn. Ctr. for Env’t Advoc. v. City of Lakeville, No. 19HA‑CV‑25‑5103 (Minn. Dist. Ct., Dakota Cnty. filed Aug. 5, 2025); Complaint, Minn. Ctr. for Env’t Advoc. v. City of North Mankato, No. 52‑CV‑25‑568 (Minn. Dist. Ct., Nicollet Cnty. filed Aug. 5, 2025). ↑
City of Imperial v. County of Imperial, No. ECU-004457 (Cal. Sup. Ct. filed Dec. 4, 2025); Hatfield v. TransGas Dev. Sys., LLC, No. 3:25-cv-00714 (S.D. W. Va. filed Dec. 3, 2025); In re FLX Strong v. Town of Lansing Zoning Bd. of Appeals, Index No. EF2026-0069 (N.Y. Sup. Ct., Tompkins Cnty. filed Jan. 29, 2026); Crosby v. Colleton County, No. 2026CP1500021 (S.C. Ct. C.P. filed Jan. 9, 2026); Guido v. Columbia Cnty. Bd. of Comm’rs, No. 2026ECV0297 (Ga. Super. Ct., Columbia Cnty. filed Feb. 25, 2026); Guido v. Columbia Cnty. Bd. of Comm’rs, No. 2026ECV0298 (Ga. Super. Ct., Columbia Cnty. filed Feb. 25, 2026); Hairston Clan v. Stokes Cnty., No. 26CV000198-840 (N.C. Super. Ct., Stokes Cnty. filed Mar. 12, 2026); Franklin Citizens for Responsible Dev. v. City of Franklin Planning & Zoning Comm’n, No. 26-CI-00123 (Ky. Cir. Ct. filed Apr. 2, 2026). ↑
Complaint, Midwest Env’t Advocs., Inc. v. Wis. Pub. Serv. Comm’n, No. 2025-cv-004023 (Wis. Cir. Ct. filed Dec. 9, 2025). ↑
Petition, State of Missouri ex rel. Wake Up Jeffco, LLC v. City of Festus, No. 26SL-CC03024 (Mo. Cir. Ct. filed Apr. 8, 2026). ↑
Complaint, Newsom & Cent. VA Marine v. Amazon Data Servs., Inc., No. 3:25‑cv‑00074 (W.D. Va. filed Sept. 15, 2025). ↑
For example, claims could be brought under Texas Senate Bill 6, California Senate Bill 57, or Oregon’s POWER Act, among others. ↑
See, e.g., 815 Ill. Comp. Stat. 505; Cal. Bus. & Prof. Code § 17200. ↑
Complaint, Md. Off. of People’s Couns. v. PJM Interconnection, L.L.C., FERC Docket No. EL26-63-000 (filed May 7, 2026) (“PJM’s hybrid methodology broadly socializes to all customers costs that data centers, not existing customers, are driving. That result is unjust and unreasonable and violates the cost causation principles that have long governed transmission cost allocation and that this Commission has repeatedly affirmed.”). ↑
Connect with a global network of over 30,000 business law professionals